5 Key Research Findings on Enterprise Artificial Intelligence
New research on artificial intelligence shows how CAOs and CDOs are responding to the current pandemic, economic uncertainty, and renewed focus on social justice

Hot off the press today is a FICO-commissioned research study on artificial intelligence and how Chief Analytics Officers (CAOs) and Chief Data Officers (CDOs) are responding to the current pandemic, economic uncertainty, and renewed focus on social justice. In additional to a survey, in-depth interviews with the top AI leaders at HSBC, AXA PPP, Banorte, and Chubb provides additional perspective and commentary.
The entire 24-page report is available for download; however I wanted to share some highlights from the research that I found to be particularly impactful, or perhaps even surprising given the amount of hype around AI in the market today.
1 – Many Organizations Are Not Yet Monitoring their Predictive Models for Drift
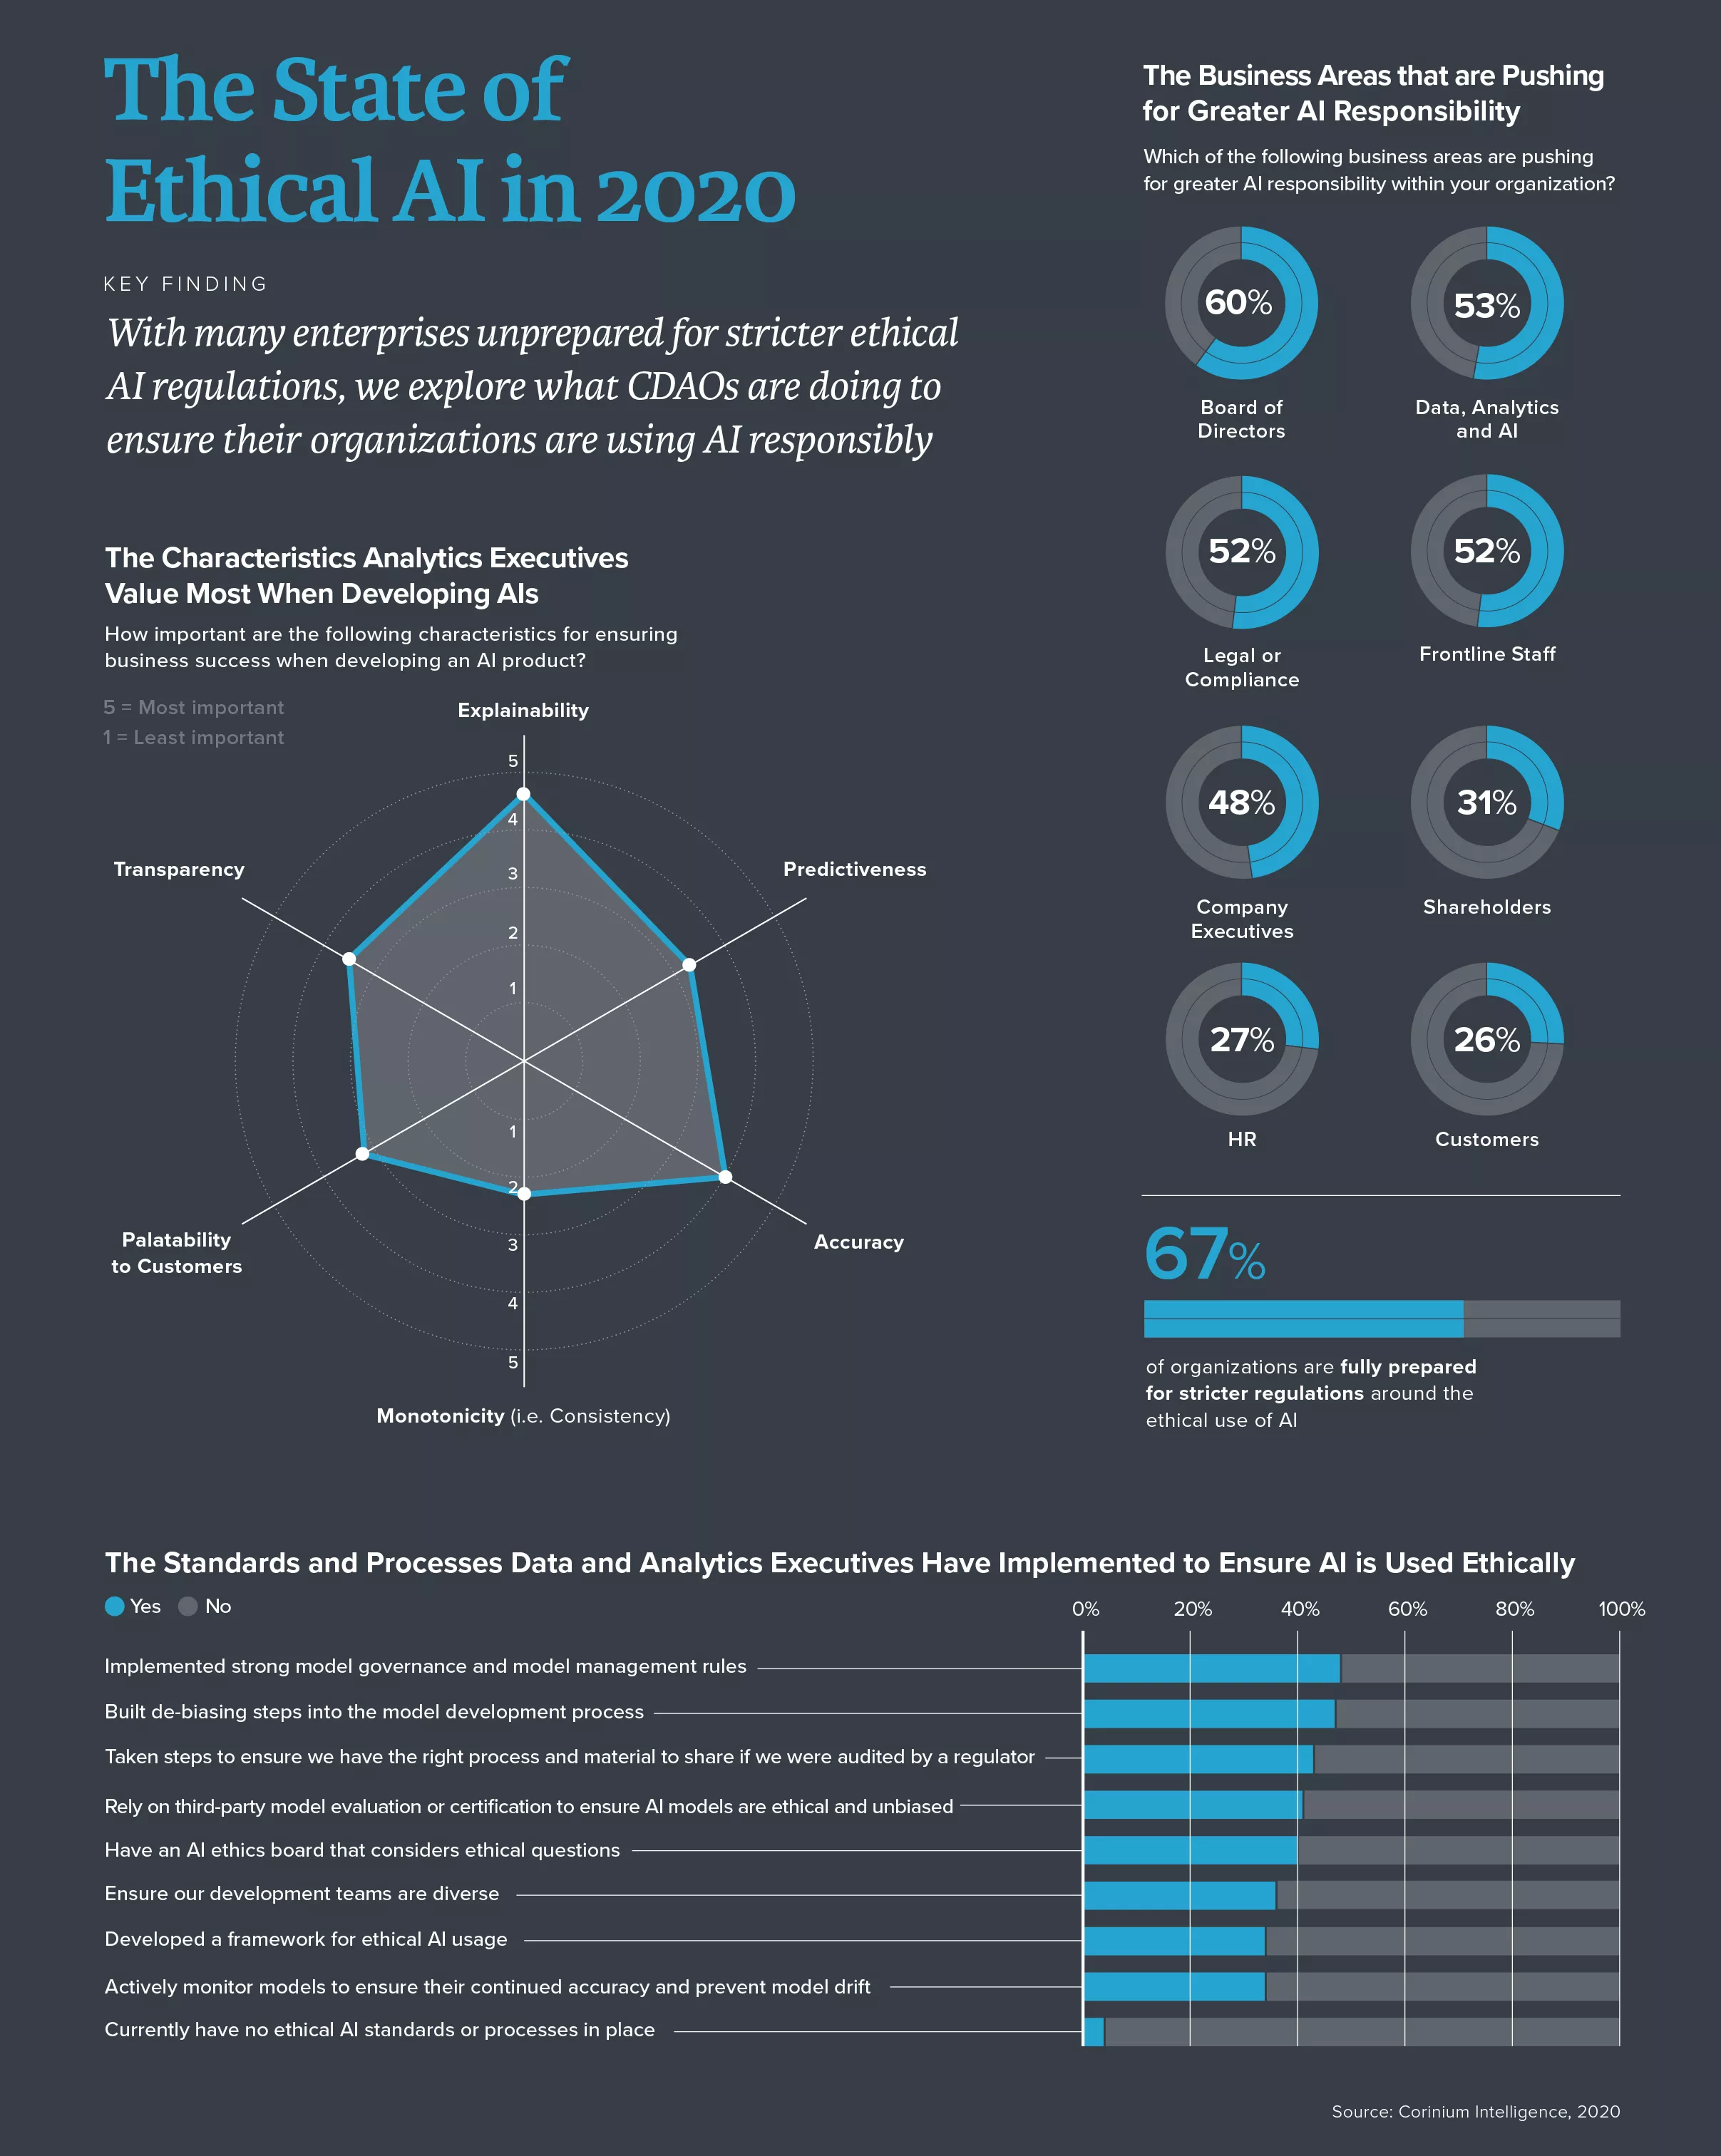
The pandemic has caused a drastic shift in consumer behavior as individuals stay at home and adjust their daily routines. Many travel, hospitality, and restaurant workers are out of work, and those fortunate to still be employed have shifted their spending patterns. This in turn has put pressure on AI and machine learning teams to ensure the accuracy of their predictive models in this changed environment, yet only 33% are monitoring their models in production.
2 – Responsible AI Has Never Been More Important
Explainable AI has been a priority for many. Explainable AI is a necessary but not sufficient condition of producing ethical AI models, and 93% of respondents report that ethical considerations must be addressed in order to drive additional AI adoption in their organization.
First, as the Black Lives Matter movement has forced many global organizations to re-examine their diversity and inclusion practices, the behavior of AI systems and predictive models are now being re-examined as well. Some key questions that must be answered include:
- Are my predictive models operating in a fair and inclusionary way?
- Has my data been property evaluated and corrected for potential data bias?
Without explainable AI (xAI) corporate standards and proper model governance and model audit trails, it’s very difficult or impossible to answer these questions confidently. As one solution to this problem, see FICO’s blockchain for an immutable model development audit log that makes answering these questions easy.
Second, as data patterns have shifted, how can organizations be sure their existing models are robust and will continue to meet their business needs? Predictive models rank-order the likelihood of outcomes, and the rank-ordering for a well-developed model is generally preserved even if the odds shift higher or lower in general. Rather than rebuilding the model during a drastically shifting non-stationary data pattern, a robust model can be wrapped with refreshed decisioning criteria or a new policy to continue to reach the desired results.
3 – Scorecards Are Dead! Long Live Scorecards!
The hype of AI can be exhausting. Some vendors would have you believe that techniques like AutoAI will eliminate the need for data scientists, and machine learning is superior to traditional statistical modeling approaches and scorecards in every way, shape and form.
In fact, the reality is that there is a spectrum of algorithms and approaches within machine learning and statistics, and the context of use and definition of the problem matter hugely for which algorithm or approach is most appropriate to each problem.
Perhaps not surprising, nearly 46% of global CAOs report that, despite the heavy daily doses of AI hype, the scorecard continues to show “potential for large impact” in their organization. It’s a proven, highly explainable approach for predictive analytics that continues to be appropriate for mission-critical and regulated use cases.
4 – The Race for AI Continues
A recent headline in Bloomberg read: Coronavirus Will Finally Give Artificial Intelligence Its Moment. Will the pandemic result in a kind of golden age for AI? Only time will tell, however we can say that the shift to digital has caused 57% of global organizations to report that COVID-19 has increased demand for AI products.
While the board of directors and C-suite almost universally appreciate the importance of AI (100% of respondents indicate is either or fully accepted as a strategic imperative), it does appear that there will be more pressure to show clear ROI and cut through the hype to provide a mature and sophisticated approach to AI.
With 65% reporting that building a team with the right skills is a medium or large barrier for success, it’s likely that teams will continue to invest in efficient processes, streamlined development to production environments, and centralized approaches to AI governance and skills and resource management. As I’ve indicated ‘its time for AI to grow up’ and meet with mature processes and governance that are appropriate to the impact these models have on our businesses and those that are served by these models.
5 – Adversarial AI Attacks Have Arrived
It’s common knowledge how easy it is to trick and subvert AI systems. Even changing a single pixel can cause an image recognition system to categorize an obvious truck as a giraffe, for example.
Organizations are waking up to the fact that these adversarial players are hard at work within their organizations. 12% of organizations have reported experiencing an adversarial AI attack and 24% report they have experienced data poisoning. These are likely happening more often than CAO/CDOs recognize and pose a serious threat to sustained long-term use of AI in the mainstream. As such, it is an area that warrants a close watch.
We hope you find the research useful as a source of industry benchmarking, and independent data source to evaluate your current investments and strategy with respect to AI, machine learning and advanced analytics.
There are many other interesting findings in the report, including how CAOs and CDOs track and report metrics for success, how global AI organizations are structured, how analytic leaders interface with their board of directors and C-suite counterparts, and how organizations are progressing in their evolution to be more mature data & analytics-focused organizations that use responsible AI to deliver compelling customer experiences, and support the business to compete and win.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.