Explainable Machine Learning for Probability of Default Calculations
How the FICO Platform can enable explainable machine learning models for more effective PD calculations

In my last post I looked at using predictive machine learning models (specifically, a boosted ensemble like xGB Boost) to improve on Probability of Default (PD) scoring and thereby reduce RWAs. The results were quite impressive at determining default rate risk – a reduction of up to 20 percent. Default prediction like this would make any balance sheet owner happy – empowering lenders to more accurately predict which borrower presents a credit risk.
To ensure accurate forecasting, we need to not only determine probability of default but also create explainable machine learning models, which is harder than with traditional scorecards. One needs to lay out how the algorithm impacts the credit risk decision, in a way that is accurate, scalable and easy to review. So let’s see how a machine learning algorithm can be managed within our FICO Business Outcome Simulator (BOS), to offer these more accurate prediction methods.
To do this, I used the xAI toolkit in FICO Analytics Workbench, part of the capabilities available on FICO Platform, and that means I can create a Python container with my machine learning model, with all its explainability, and use it elsewhere.
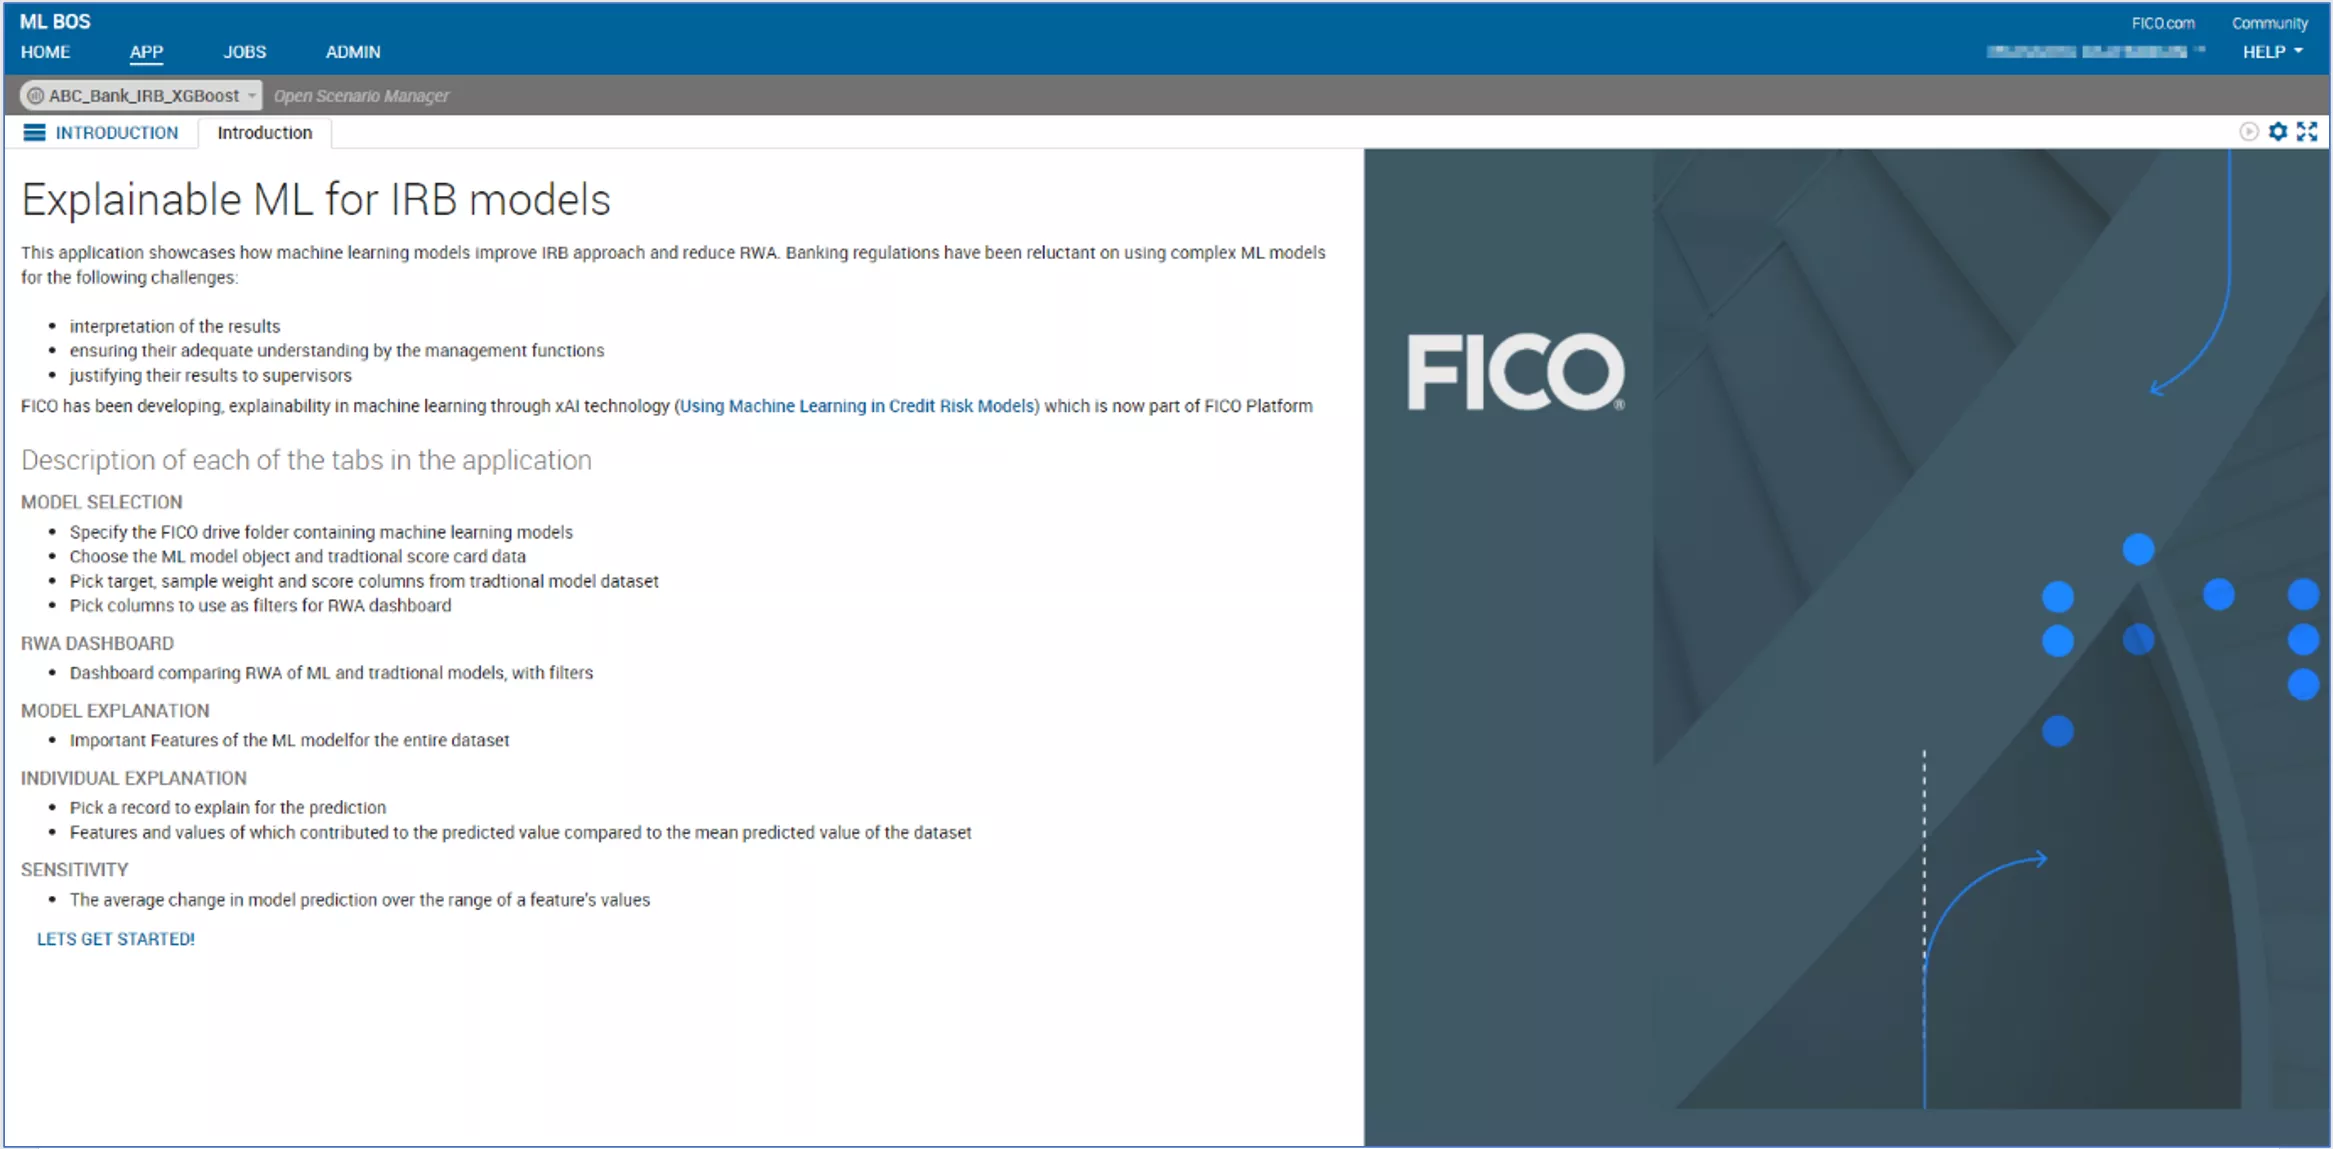
Quick Access to explainability for machine learning models
With my colleague Prasanth, we put together a toolkit in FICO Business Outcome Simulator (BOS) to allow capital model managers quick access to explainability of their new machine learning algorithms. From comparing the old to new results quickly (and allowing a deep dive into different segments) to exploring the individual records to see why they received the Probability of Default (PD) they did, the power of Xpress Insight lets us create any dashboard or report we want, and gives us the capability of executing models and explainability natively with greater accuracy and flexibility.
How does it work? We start by bringing in the current Probability of Default (PD) model and then creating a candidate model with data supplied by the client. We use Analytics Workbench to produce the machine learning Probability of Default (PD) model and add it alongside the current model on the BOS shelf. From here we can run a risk-weighted assets (RWA) comparison (as precise as possible, depending on other data supplied by the client) and show the differences in the prediction on a full portfolio basis or filtered down using any of the data fields available.
Now it gets interesting. Although we built the explainable machine learning model inside Analytics Workbench — accessing the unique FICO code libraries that are available on the FICO Platform for interpreting all kinds of tree ensemble models — because these xAI libraries are a core capability on the Platform, and because we can run Python code natively in different places as required, we can show the model interpretability details within BOS.
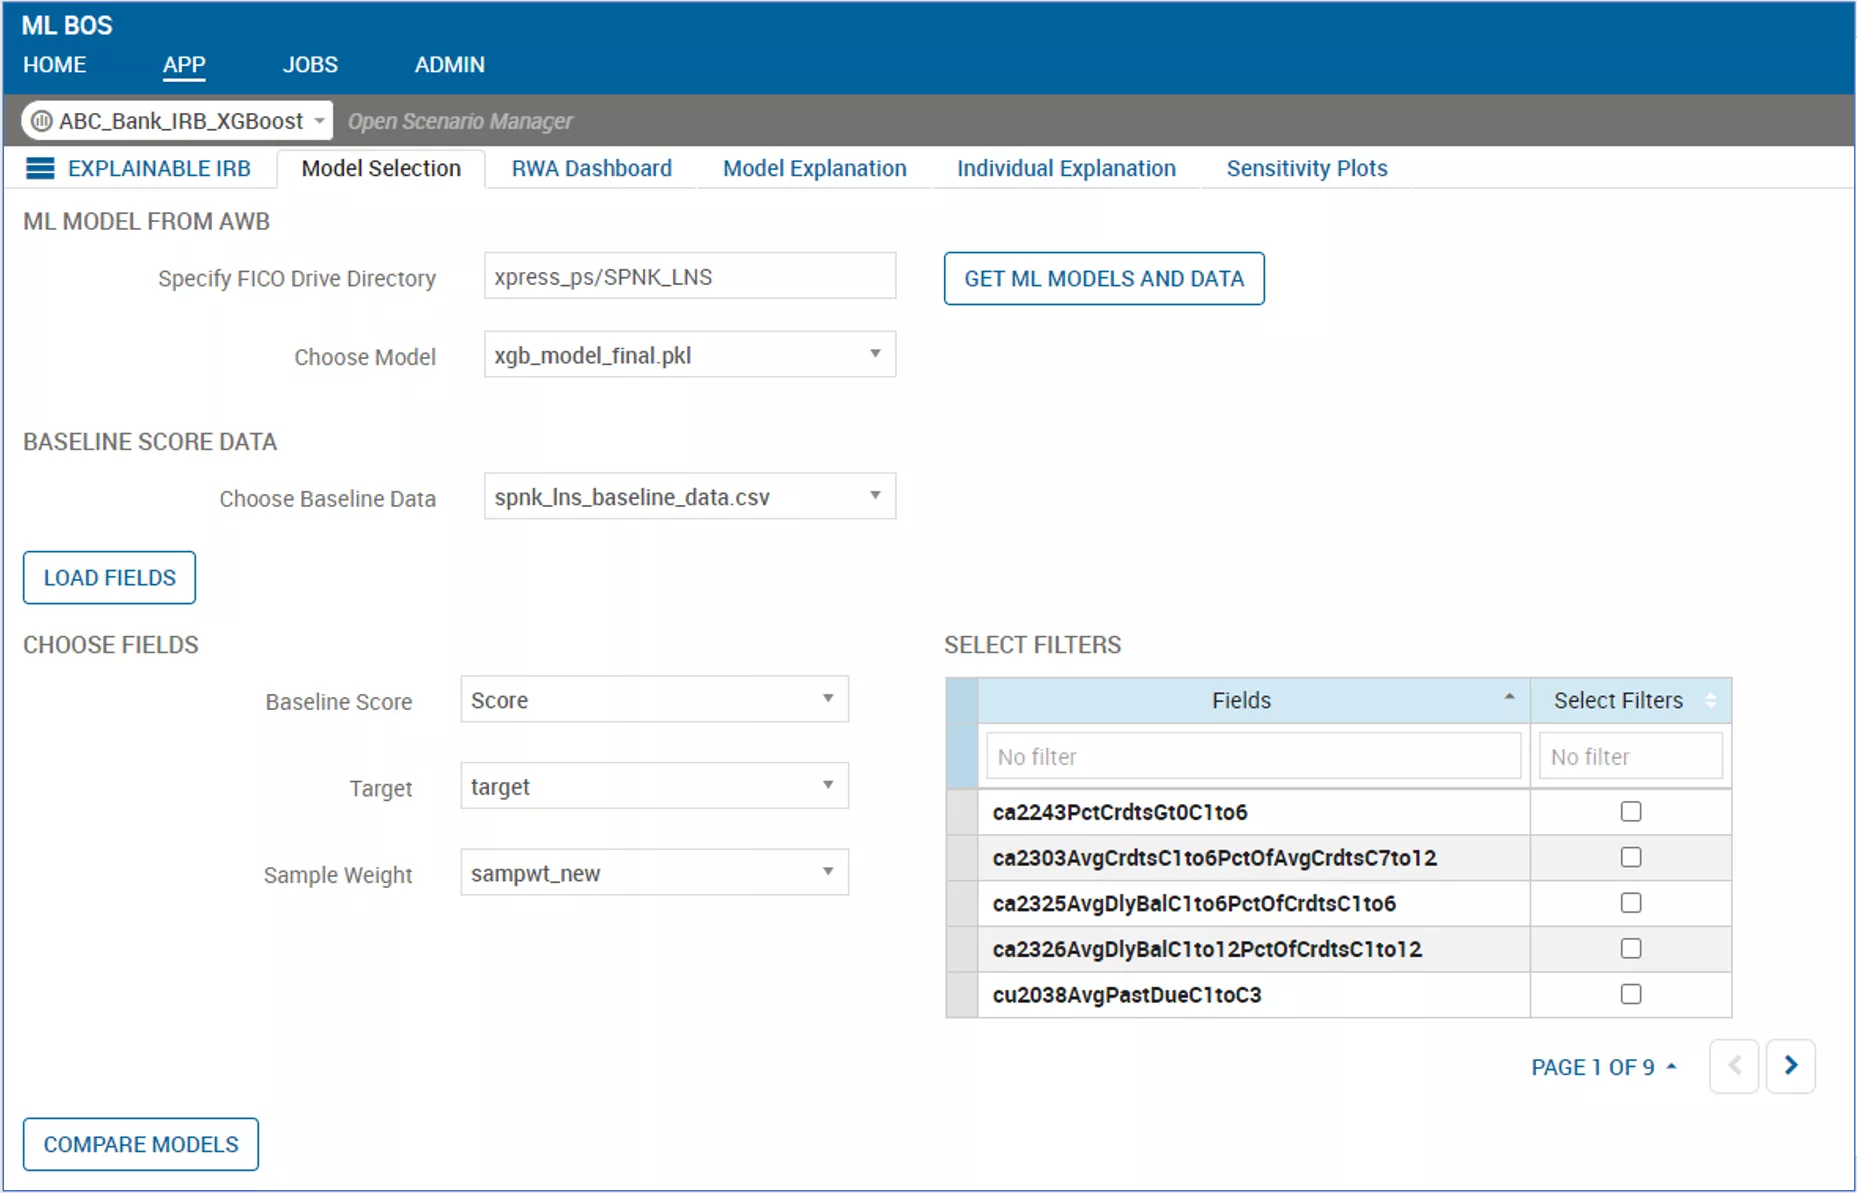
First up are the model-level variable explanations. The Feature Importance statistics are just the tip of the iceberg of what we can show here. Behind the scenes the algorithm is generating Partial Dependency Plots, Group Performance Metrics on a variable-by-variable basis, aggregated feature contribution visualisations (violin plots are popular for this), ICE plots, pairwise feature importance diagrams and more. All these things can be brought out and displayed with BOS.
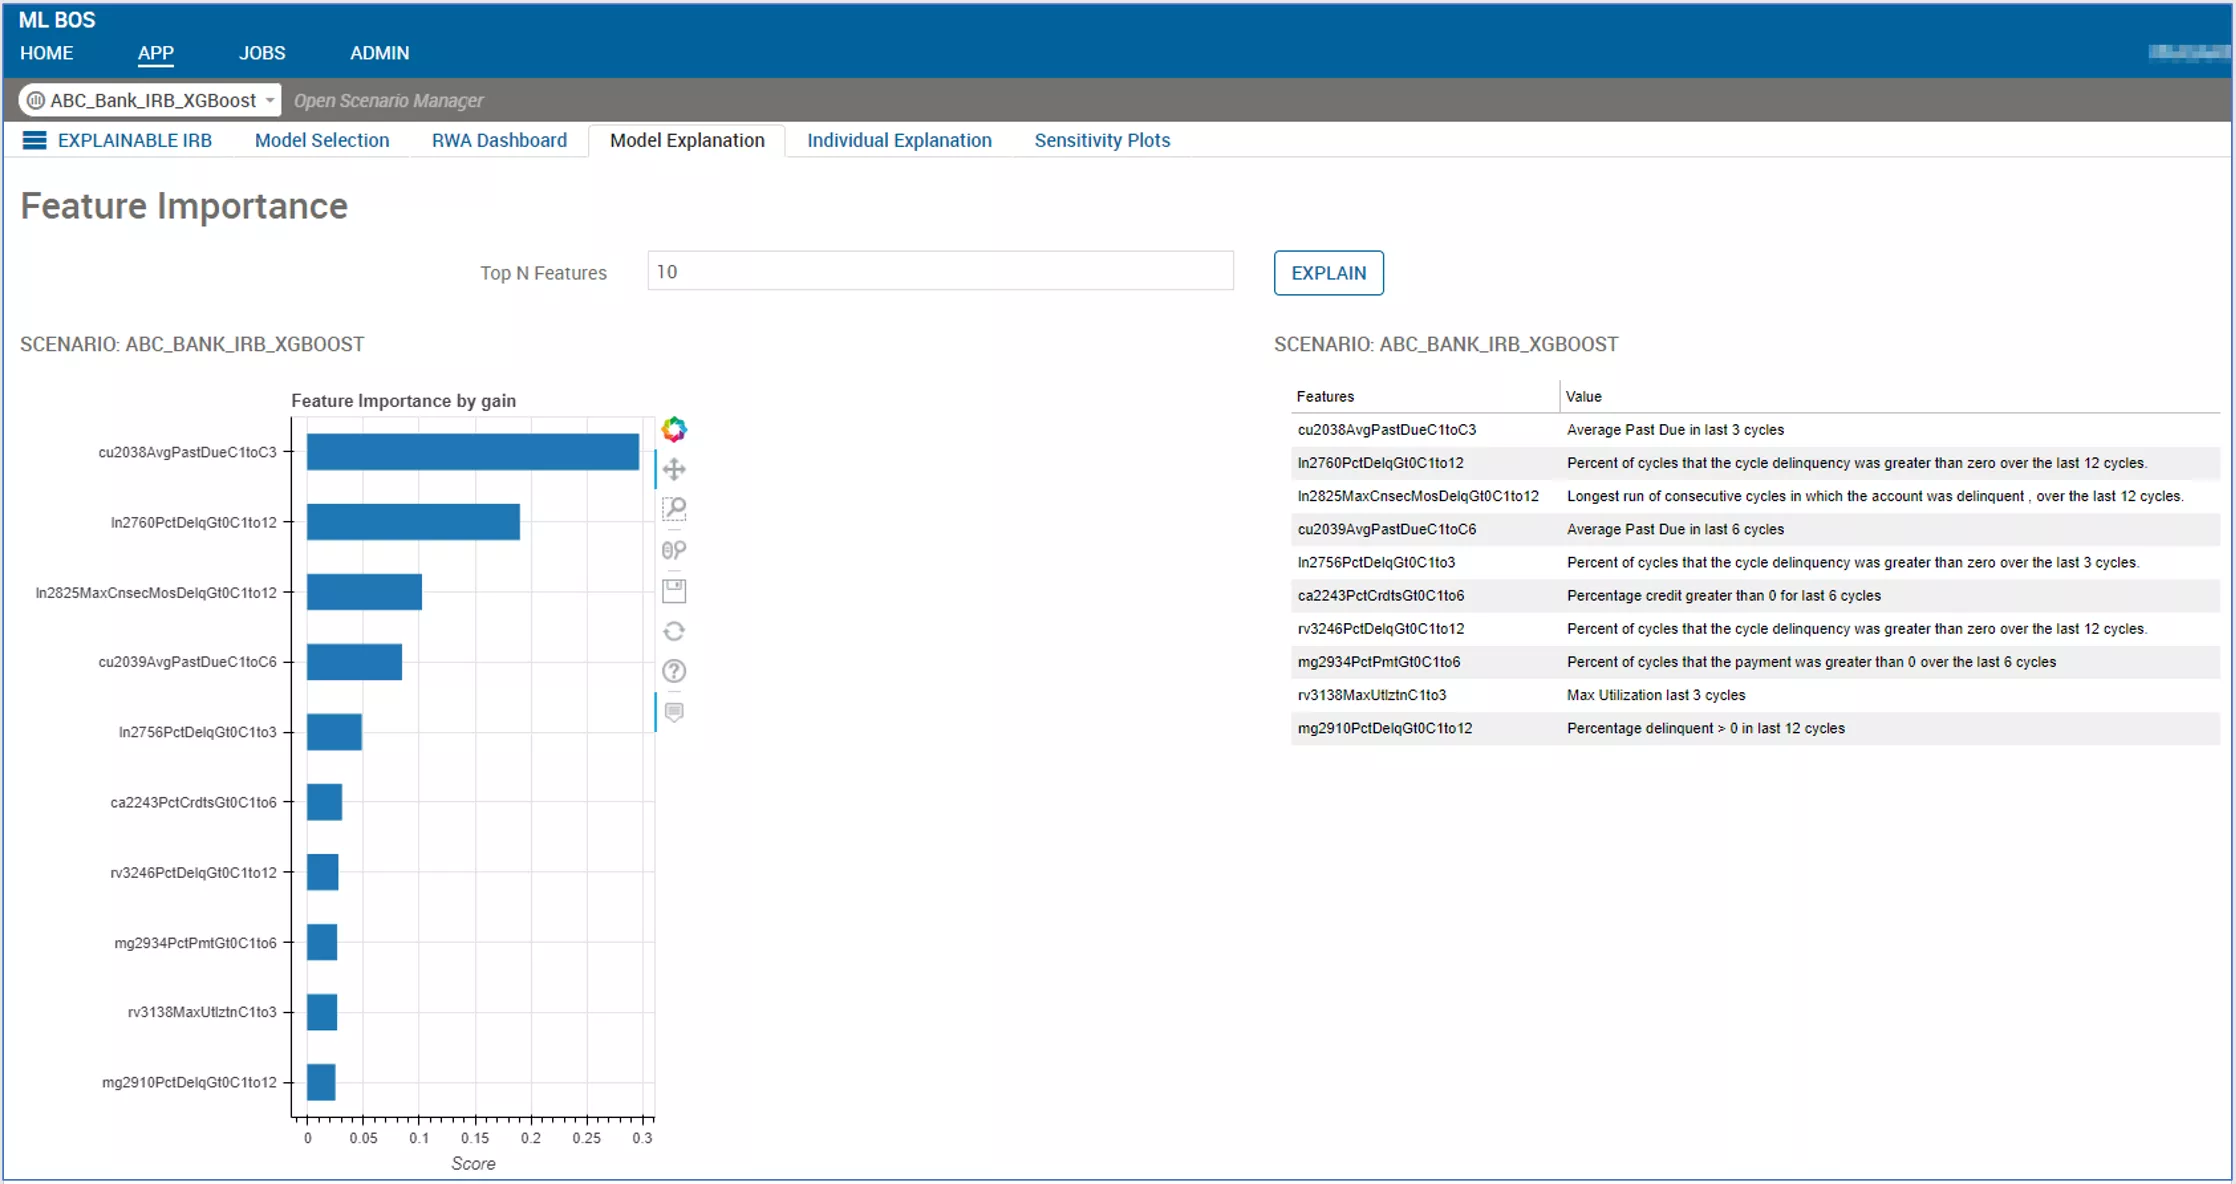
Method to get the individual default prediction of a borrower
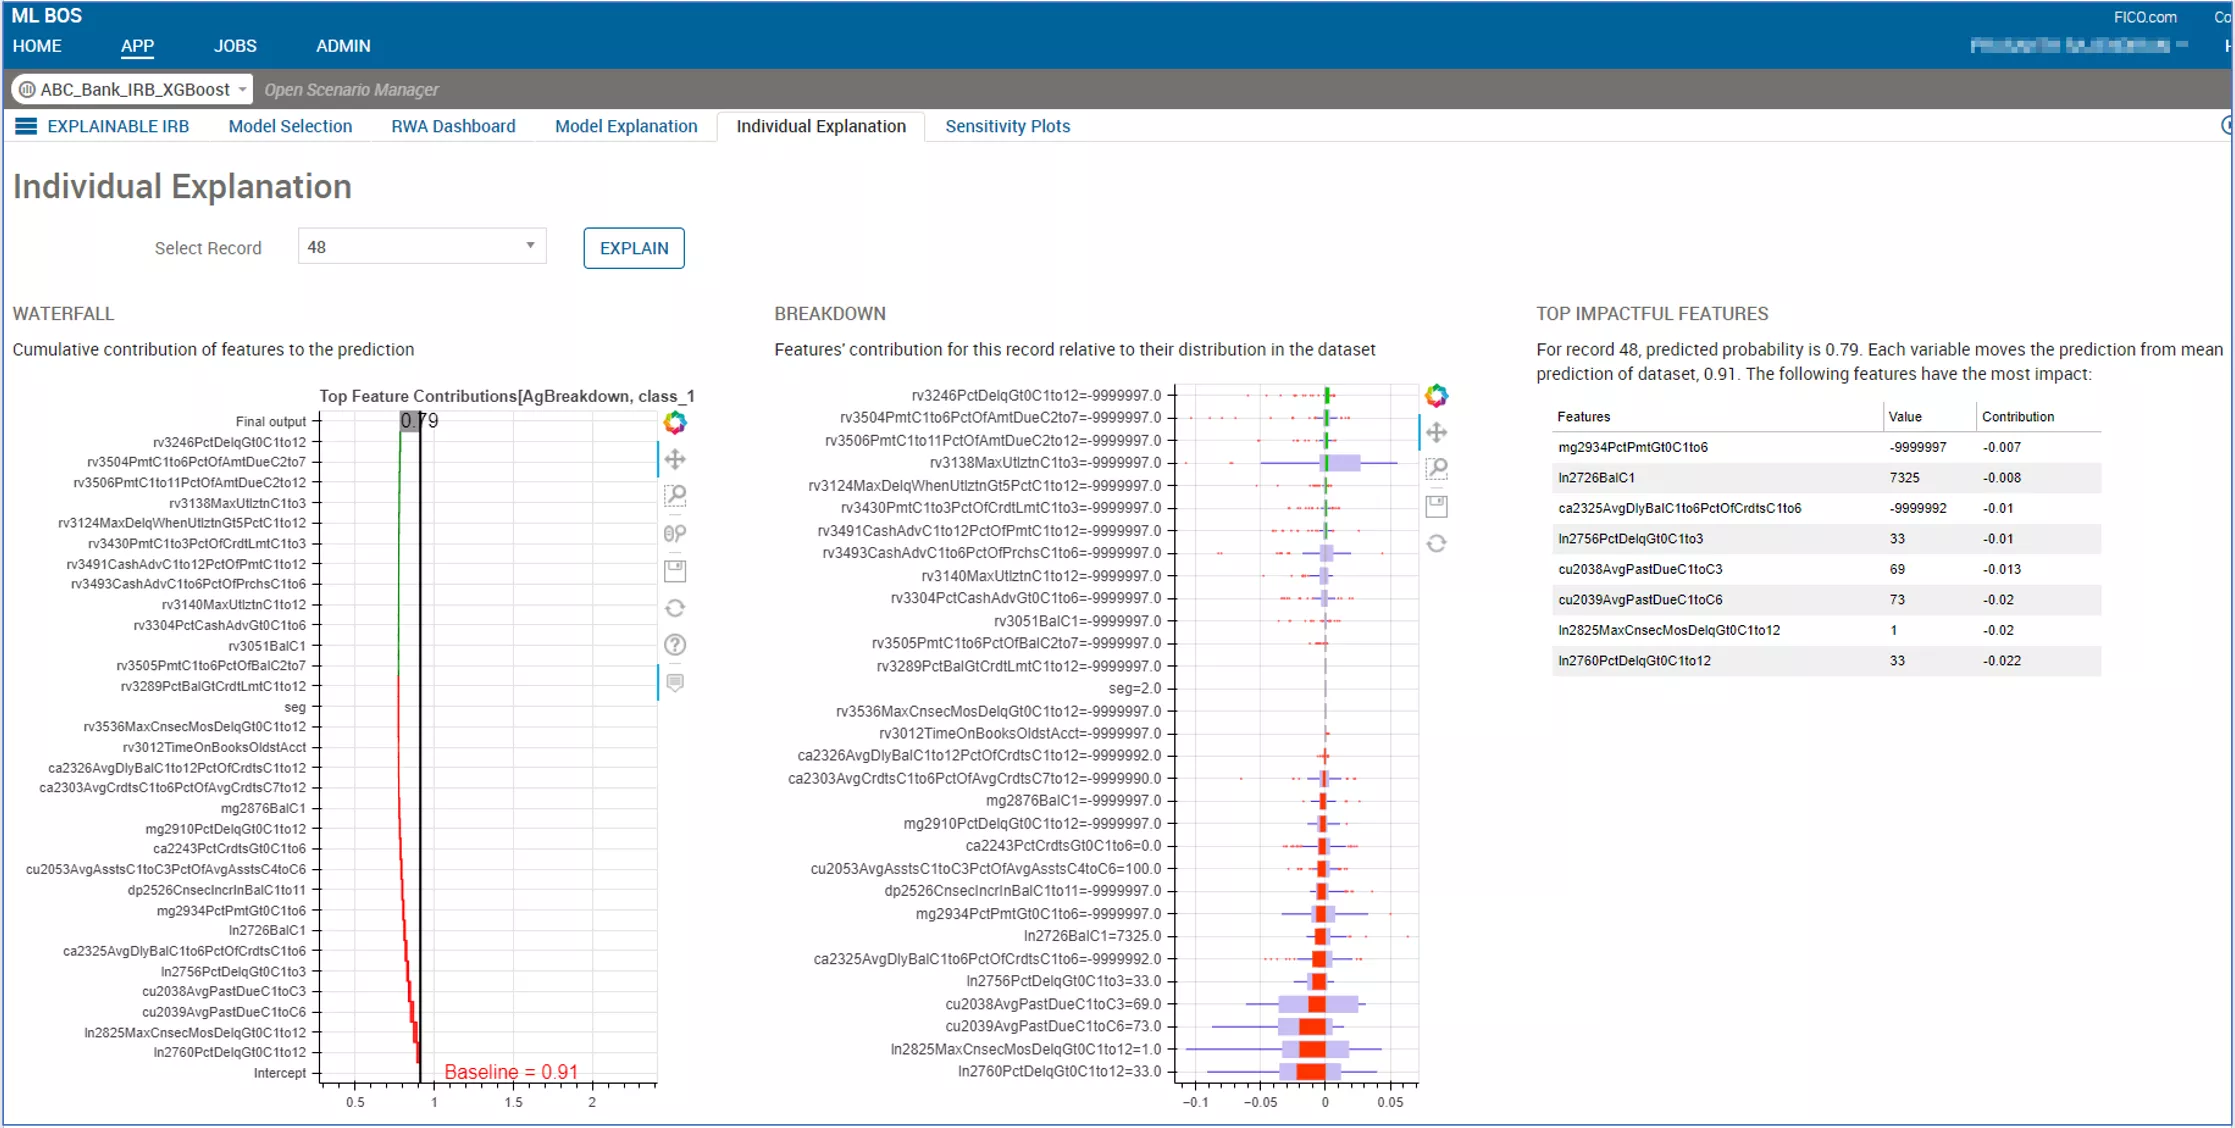
Next, we move to individual instance explanations. Here we can show how the fields for an individual account or borrower contribute to the final score and can display how those contributions compare to the broader model build dataset. Digging deeper, we can provide sensitivity curves giving a unique view for each exposure as to how their Probability of Default (PD) might change if individual variables are altered.
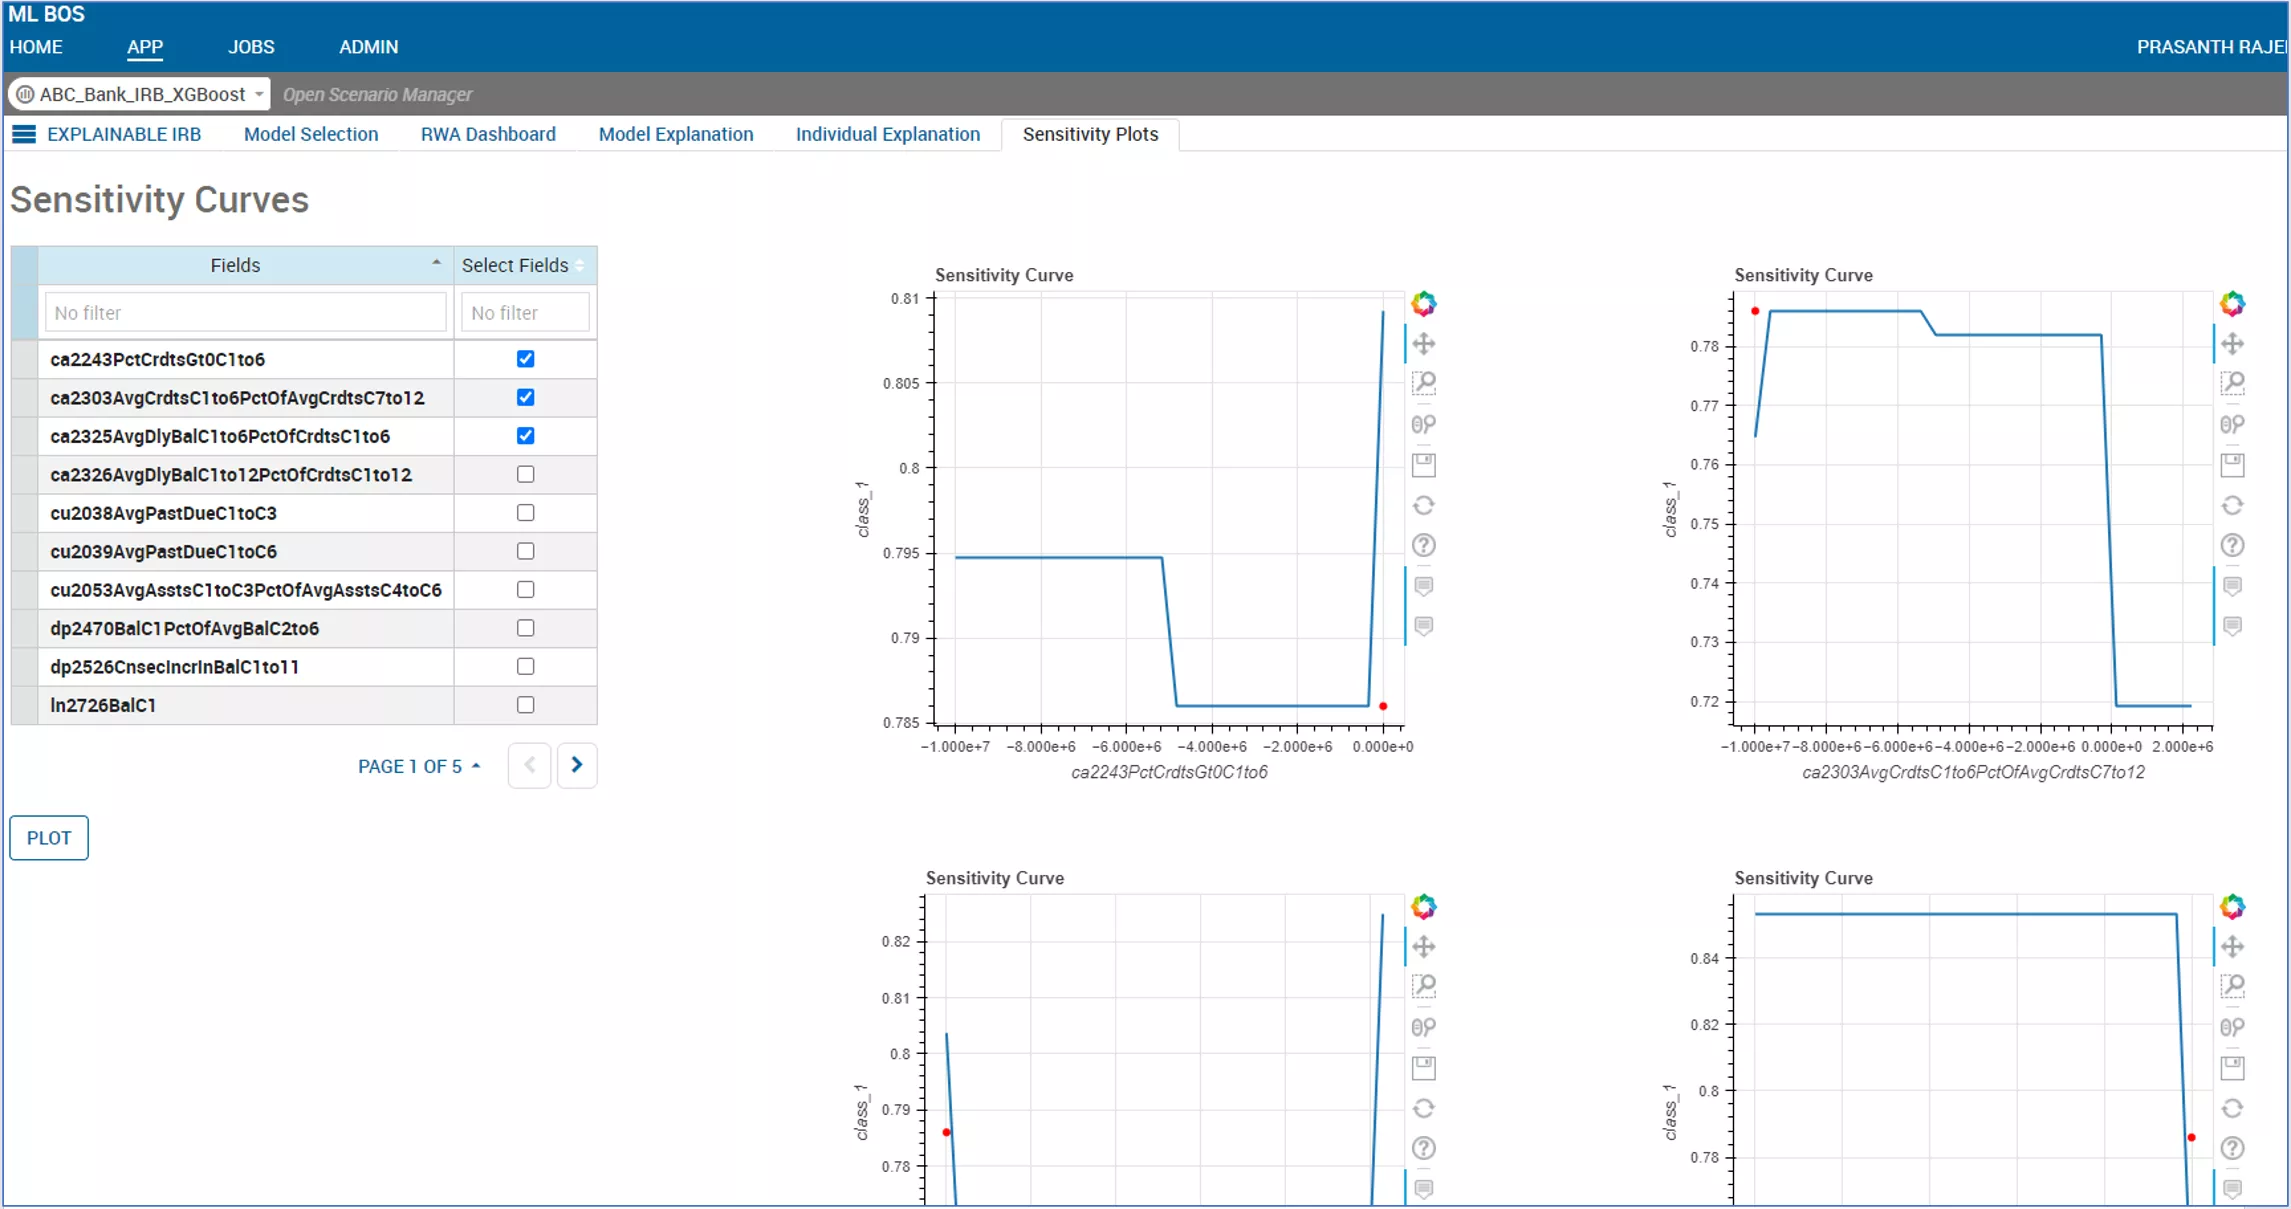
With this method, the combination of macro- and micro-level analysis provides assurance that, subject to regulatory approval, moving to machine learning Probability of Default (PD) models not only delivers RWA improvements, it means that the new machine learning models can be explained at the model and individual instance level, a necessary criterion for both internal and external audiences.
If you’re interested in finding out how FICO xAI and the power of the Decision Management Platform can enhance your life-cycle model execution or provisioning and capital calculations, do let us know. With regulators around the world increasing looking approvingly at the use of machine learning solutions in these areas, FICO can enable banks to be at the forefront of innovation for Pillar 1 and Pillar 2 RWA calculations.
With thanks to Prasanth Rajendiran and the FICO Business Outcome Simulator team
How FICO Can Help You Improve Loss Calculations
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.