Application Fraud – An Open Door for Fraudsters
Digital transformation, accelerated by the pandemic, has increased the threat of application fraud

Fraud at the point of application has long been an issue for lenders. Over the years, other sectors that needed personal data to set-up accounts and provide access to services have also fallen in the line of fire of criminals. We have seen insurance, utilities and mobile phone contracts all targeted by application fraud. This trend has grown considerably, as the pandemic forced rapid digital transformations across organizations that were far from ready.
The last few years have seen enormous demand for digital onboarding and vastly higher expectations from consumers for instant access to new credit and services. The winners and the losers during this time have been differentiated by the speed and ease of the application journey experienced by their customers. A significant proportion were (and still are) willing to switch companies for a better digital experience. During 2021, we saw the optimization of the customer experience top the agenda within organizations.
For fraudsters, this sharp and hasty shift to digital and the intense focus on customer experience has opened doors. Application fraud soared during the pandemic and continues to grow today. Evolving technology (bots, cloud infrastructure and virtual machines) has enabled criminals to submit fraudulent applications at scale to different organizations.
In most cases, fraud controls are still not taking place at the point of application. In areas, including the UK and parts of Europe, where there are some provisions in place, the application process involves rules, credit bureau data and batch processing. Fraud, however, is evolving quickly. Therefore, the way fraud has traditionally been tackled at the application stage needs to evolve too.
Trends driving the rise in fraudulent applications
Identity theft is one of the key drivers for the soaring levels of application fraud. It remains one of the top three fraud attacks, alongside phishing and card testing. In Europe specifically, organizations have seen a significant rise in identity theft over the past year. Globally, it’s expected to be the cause of losses to online payment fraud reaching $206 billion by 2025.
Another rapidly rising phenomenon that has been highlighted by financial services organizations as even more challenging to identify and address than identity theft is synthetic fraud. It’s driving a new wave of fraud rings that are fabricating hundreds of thousands of identities to apply for new accounts or credit lines, then using them to steal or move money before embarking on other types of fraud. The threat from synthetic identity fraud is amplified as the number of identities that can be created is virtually unlimited and there is no real person that owns the identity who could spot and report the misuse.
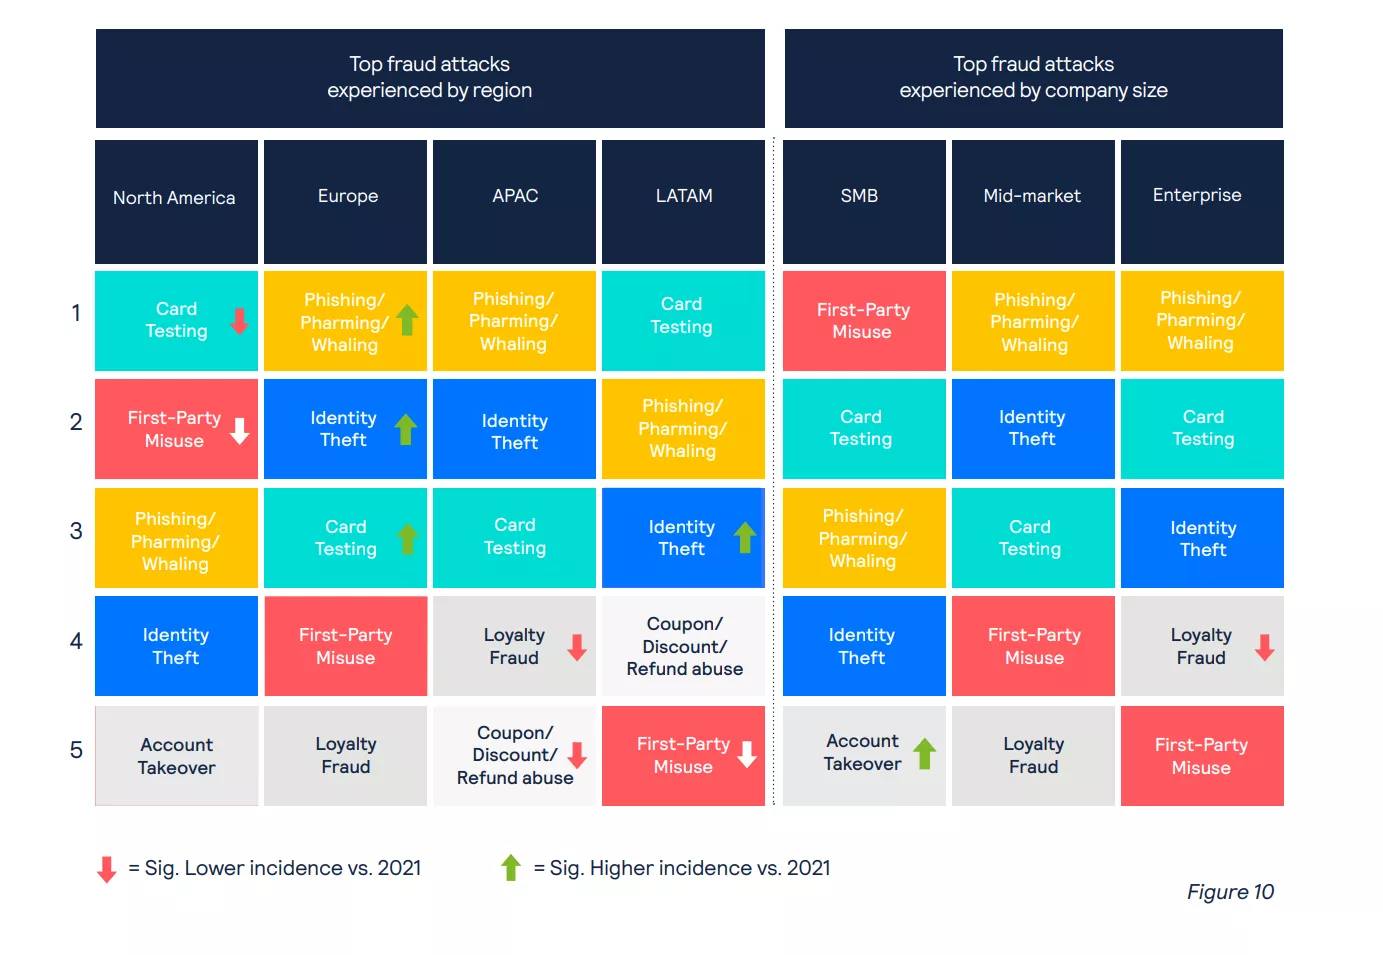
First party fraud (where genuine individuals exaggerate personal details to access new or increased lines of credit) is also on the rise, driven by challenged finances. Last year, it was the fourth biggest type of fraud attack across Europe.
(Table below from Global Fraud and Payments Survey Report 2022)
Understandably, with the rising cost of living many households are struggling with repayments and organizations are bracing themselves for higher levels of payment defaults, but how many of these will be from genuine households struggling to pay versus stolen or fabricated identities? A substantial amount of fraud gets hidden in an organization’s bad debt losses. Some estimates put fraud at between 5% to 20% of bad debt, but in cases where no payments have been made at all, it could be as high as 50%.
Signs of fraud, whether it is first or third party, can and should be spotted at an earlier stage. Instead, fraud checks are being introduced too late into the cycle, resulting in high levels of first payment defaults.
Fraudsters are attacking other sectors
While the financial services sector is, and continues to be, a key target for fraudsters, no sector is immune to fraud. The current environment means that every sector is now being hit hard with telecommunications a prime example. The high cost of smartphones has made them as valuable to fraudsters as loans and credit cards. Over the last 20 years, the cost of top-end mobile phones has soared by 490%, with some premium smartphones now costing over half of an average consumer’s monthly wage.
Telcos has become a key target for application fraud – where it is usually referred to as subscription fraud - and is seeing extremely high levels of first payment default fraud – with people applying for mobile phone contracts, then disappearing with the phones before the first payment is made. Subscription fraud is now the number one fraud type globally within the telco sector.
By 2021, total fraud losses in this sector reached 2.22% of its global revenues ($1.8 trillion USD), which were estimated to be approximately $39.89 billion USD. However, with a significant proportion of fraud incorrectly being classified as debt in this sector, losses from fraud are likely to be much higher.
Compounding the issue is the fact that sales teams are incentivised to secure the contract, rather than ensure the application is genuine. Unless fraud checks are made systemic and a vital part of the originations process, the issue will never be resolved for this sector. However, there’s a clear shift taking place, with some of the more innovative telco providers looking at solutions to tackle fraud at the point of application. We expect to see some changes in the way fraud is managed in telcos.
The customer friction factor
Organizations want to reach a balance between onboarding as many legitimate customers as possible, but making sure fraudsters are kept out. The concern is that too many overt checks could lead to consumers abandoning the process.
Fraud checks, however, require much of the same personal information as is needed to make an application, so they can, and should, be tightly integrated within the whole origination process. By making them a part of the same workflow as managing the credit checks, organizations are giving their customers a better experience as they’d only be required to go through the process once. Furthermore, fraud controls at the point of application can alert organizations to ‘suspicious circumstances’ rather than ‘confirmed fraud’, enabling them to adjust their offers more appropriately. For example, granting access to an account, but not an overdraft. More customers can be brought on board without delay and without the organization overexposing itself.
The right solution
A lot of fraud is being missed because too many organizations do not have an effective solution that looks for fraud at the point of application. Those that do have a solution often find that it is disconnected from the systems used for originations and customer management. Data valuable to a fraud decision is siloed in an originations system and vice versa. This means that either customers are inconvenienced by being asked for the same information multiple times or decision making is ill-informed.
With fraud evolving at such a rapid pace, fraud solutions must be flexible and agile to keep up. The more data sources that can be brought together, the more insight that can be gleaned, whether it’s internal or multiple external data sources. Effective fraud solutions can no longer be tied to just one data provider, and they must work in real time.
FICO Platform, for example, eliminates data silos and delivers interoperability across multiple use cases. As it is component-based, the same capabilities that manage an application fraud use case can also be used to manage customer originations. Data whether internal or from third party providers can be accessed across all use cases to deliver more informed and customer-centric decisions. It gives organizations unprecedented insight into their customers’ immediate and future needs. This is what will enable organizations to minimise customer friction and detect suspicious applications without interrupting the customer experience.
Fraud losses are burgeoning and much of it is being misclassified as bad debt. It’s time to close the door on application fraud.
How FICO’s Advanced Analytic Capabilities Can Help Your Organization Fight Fraud
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.