COVID Vaccine Fraud: Be Wary of the Scammers
Review the latest scams emerging and run through a checklist of how to protect yourself and your loved ones

Around the world, COVID vaccination campaigns are ramping up, as leaders pledge to protect their citizens from the deadliest pandemic in a century. But despite Herculean logistics efforts worldwide, in some countries (and localities within the US), the vaccine is still hard to come by.
People everywhere are anxious to get the COVID jab, and fearful of contracting the disease—two vulnerabilities that are among fraudsters’ favorites to exploit. Let’s take a look at some of the scams we’ve seen popping up, and run through a checklist of how to protect yourself and your loved ones.
Fraudulent “Buy Direct” Sites Proliferate
From the minute the pandemic struck, domain names containing COVID were snapped up; check out this Krebs Security article to see how the spikes in domain registrations and traffic early in the pandemic, as fraudsters quickly began shilling all manner of fake medical goods, from personal protective equipment (PPE) to nebulizers. Early on in the pandemic, FICO detected a 3x surge in medical equipment fraud.
Further downstream from the domain registration frenzy, a multitude of official-looking fake websites has popped up. These sites promise direct sales of vaccines, but instead take people’s money and personal data. The Wall Street Journal recently reported that as of mid-February, U.S. Department of Homeland Security investigators had seized roughly $33 million in illicit proceeds and analyzed almost 80,000 COVID-19 domain names.
The image below from The Journal, provided by the U.S. Department of Justice, shows a fraudulent website that invited the public to buy doses of Moderna's COVID-19 vaccine. Three men were charged with conspiracy to commit wire fraud in a criminal complaint filed Feb. 9 in federal court in Baltimore.
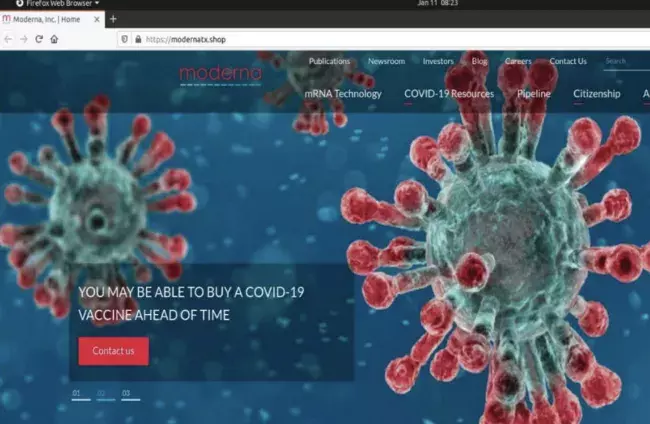
A professional-looking, yet fake website offering advance sales of vaccine.
Ads and Direct Solicitations
Meanwhile, fraudsters are also reaching out directly to an anxious public, running ads for COVID-19 vaccines on community sites like Craigslist. Some are using outbound sales teams to call consumers, offering home delivery of the vaccine after payment is made up-front.
Predatory criminals are also issuing a fleet of text messages inviting recipients to set up an appointment for a coronavirus vaccination, or urgent offers of “leftover” vaccine supposedly up for grabs. While it’s true that many clinics release unused vaccines at the end of each day, this practice is never advertised by legitimate vaccine distribution sites.
A Comprehensive Fraud Checklist
Numerous U.S. government agencies have published alerts about COVID vaccine fraud. I like this one from the U.S. Department of Health and Human Services (HHS), which is particularly useful for communicating the dangers of fake vaccine offers to elderly loved ones. Elder fraud prevention is a cause I am passionate about, and one I blog on regularly. And while it’s true that older citizens have been the U.S. government’s top vaccination priority, many fake vaccine scams are still going strong, appealing to, for example, grandparents wanting to secure COVID vaccines for younger, as-yet-ineligible family members.
The HHS alert warns that the following criteria are potential indicators of fraudulent vaccine offers:
- Advertisements or offers for early access to a vaccine upon payment of a deposit or fee.
- Requests to pay out of pocket to obtain the vaccine or to put your name on a COVID-19 vaccine waiting list.
- Offers to undergo additional medical testing or procedures when obtaining a vaccine.
- Marketers offering to sell and/or ship doses of a vaccine, domestically or internationally, in exchange for payment of a deposit or fee.
- Unsolicited emails, telephone calls or personal contact from someone claiming to be from a medical office, insurance company or COVID-19 vaccine center and requesting personal and/or medical information to determine eligibility to participate in clinical vaccine trials or obtain the vaccine.
- Claims of Food and Drug Administration (FDA) approval for a vaccine that cannot be verified.
- Advertisements for vaccines through social media platforms, emails, telephone calls, online or from unsolicited/unknown sources.
- Individuals contacting you in person, by phone or by email to tell you that government officials require you to receive a COVID-19 vaccine.
In addition, U.S. government agencies offer these tips for avoiding COVID-19 vaccine fraud:
- Consult your state's health department website for up-to-date information about authorized vaccine distribution channels. Obtain a vaccine only through such channels.
- Check the FDA's website for current information about vaccine emergency use authorizations.
- Consult your primary care physician before having any vaccination.
- Don't share your personal or health information with anyone other than known, trusted medical professionals.
- Check your medical bills and insurance explanation of benefits (EOBs) for suspicious claims, and promptly report errors to your health insurance provider.
- Follow guidance from the U.S. Centers for Disease Control and Prevention and other trusted medical professionals.
Lastly, once you have had your vaccine, don’t share a photo of your vaccine on social media! Remember, it does have personal information on it that could help thieves in an identity theft situation.
I know it’s hard to be patient. Although I was extremely lucky to track down a last-minute vaccine appointment and websites such as Dr. B are rolling out to help expand this option, I’m anxiously waiting for the green light for the rest of my family to be vaccinated. But to avoid being fleeced today, and potentially being a victim of downstream identity theft, there’s no way I’ll take the bait on a COVID vaccine scam. I know you won’t, either.
To keep up with my latest thoughts on combatting scammers, fraudsters and financial criminals, follow me on Twitter @LizFightsFraud.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.