Digitalization and Artificial Intelligence: 5 Keys to Success
Digitalization and artificial intelligence will radically change retail banking. What does this mean for banks?

Machine learning, language processing, robotics - the artificial intelligence toolbox offers a range of smart tools that enable machines to act autonomously. In order not to miss the boat of the rapid technological developments, financial institutions need to know where their digitalization journey should go and how they want to use the innovative technologies in a focused manner.
In May 2018, Google CEO Sundar Pichai presented a new technology called Duplex at the Google IO developer conference. This technology enables Google's digital assistant to call service providers or restaurants to make an appointment with a hairdresser or to book a table, in natural language. The conversations presented in the demo are indeed impressive, and the filler words inserted by the AI make the conversations sound very natural. Regardless of how market-ready one may consider such technologies: the progress in the development of automatic dialogue systems is rapid, and it is foreseeable that such systems are or will be more and more capable of taking over significant parts of the interaction with customers in banks as well. This is especially true for many standardized business transactions that do not require much consultation and do not serve conflict resolution.
Banks are facing similar upheavals in process automation: In a first wave of automation 20 to 30 years ago, we saw how certain processes were removed from the branches and transferred to new centralized units. In these units, processes were serialised and trimmed for productivity. With digitalization and AI, many processes can now be fully automated for the first time, without manual steps. This promises both significant cost advantages and faster processing and thus a better customer experience. Compared to such fully digital processes, the processes from the first wave of centralization and rationalization will appear quite manual.
This development is also supported by the fact that the decisions that are necessarily automated in digital processes are becoming better and better and regularly surpass the performance of manual decisions and decision strategies developed judgmentally. Methods from operations research such as mathematical optimization enable a quantitative understanding of the trade-offs between competing goals such as profitability, market share and risk appetite, and thus allow the targeted development of tailored decision strategies.
In order for banks to be successful with digitalization and the use of AI, a number of prerequisites must be met, which I would like to outline in this article.
Thesis 1: Digitalization Requires New Skills
New technologies always come with new requirements on skills. In addition to technical know-how, an engineering mindset is essential to be successful with automated processes.
The management of digital processes and automated decisions requires employees to look at a process the way you would look at a production line – to think about error tolerances, measurement techniques and when to manually intervene with a case. While you get feedback from human employees about the success or failure of actions, you can't expect this kind of proactivity from a machine. Chatbots that do not have the right answers to customer questions lead to frustrating customer experiences – automatically and over and over again. Employees in process control must therefore keep an eye on all process steps, recognise blind spots and improve them where required.
Digitalization will also have an impact on the skillsets required in operations. When the bulk of the tasks are taken over by machines, the cases ending up in operations for manual review are more complex and consultation-intensive, and frequently include exceptions and conflicts; these are the cases that might have been escalated to the team leader in the past. Handling such cases requires more experience and higher qualification. We are already seeing some market participants using natural attrition to reduce headcount in operational units that are being relieved by digital processes. However, where staff are hired, they have significantly higher qualifications and earn significantly higher salaries than the average employee before the change.
Thesis 2: Digitalization Requires Agile Methods
If communication with customers takes place via digital channels, there is no immediate insight into where things are going wrong. While employees intuitively adapt their communication to make it effective, machines stubbornly follow their rulesets without providing feedback on what is not working.
Banks that are successful with digital processes monitor these processes closely and adjust them continuously. The results of the individual dialogue and process steps are systematically evaluated quantitatively, and alternative approaches are tested in a champion/challenger approach.
To facilitate this continuous learning loop, banks implement a cross-functional strategy team that reviews the results of the individual process steps jointly with the respective business owners, develop ideas for improvements and test them. The prerequisite for this agile and quantitative approach is the ability to implement adjustments quickly and largely without the involvement of IT resources. Therefore, the decisioning technology used must enable employees without programming skills to configure rules and communication content independently. IT resources are mainly involved in version management, if at all; the actual process and rule configuration is the responsibility of the respective business unit.
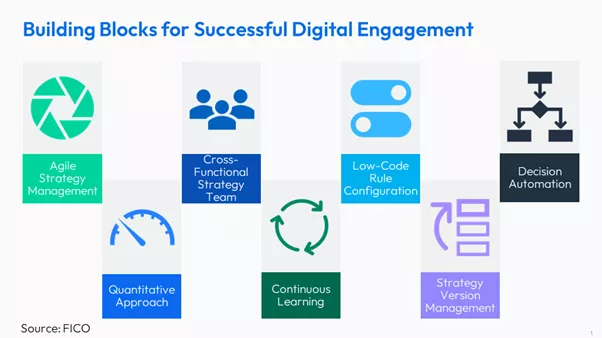
Successful organisations constantly refine digital processes with agile methods
Thesis 3: AI and Operations Research Unleash Additional Effectiveness
Which credit offers or limits a customer receives, which marketing initiatives are promising for a target group or how intensively receivables management approaches customers – the decision strategies that guide these actions are generally developed based on business experience. Analytics are frequently used to segment the portfolio — but analytical methods are often underleveraged when assigning decisions, measures or prices to these segments. This leads to considerable opportunity costs.
I expect that methods from operations research will be increasingly used in the development of price strategies, but also when developing targeted operational processes – which in some industries, such as manufacturing, has been common practice for decades. With mathematical decision optimization, the dependencies between turnover, profitability and risk goals, for example, can be understood quantitatively, so that decision strategies can strike the optimal balance between competing goals. Not using these methods is expensive: I estimate that insufficient use of mathematical methods in the development of pricing strategies causes European banks to miss out on annual profits between 500 million and 1 billion Euro from instalment loans alone.
Thesis 4: AI Requires Effort
Machine learning and artificial intelligence are surrounded by an aura of effortlessness: Problems solve themselves. This assessment is inaccurate.
Many underestimate that the introduction of AI requires good preparation and regular monitoring and readjustment. This starts with the selection of the appropriate method: not every algorithm is suitable for every problem. And a model is only as good as the underlying data. Accordingly, careful data preparation and cleaning is essential.
In order to achieve real added value, it is also imperative to have a solid understanding of dependencies between business goals, methods and decision space. Where is the value in a business process, and which decision has the greatest impact? What knowledge and predictions can help improve that decision? These questions will continue to require answers from expert staff.
Thesis 5: AI Must Be Explainable
Automated decisions using AI are highly scalable. This carries the risk that errors and undesirable bias replicate in an automated fashion. Decision logic that represents a black box therefore harbors incalculable risks. It is essential to understand how models work, and you must be able to see and explain which data characteristics dominate a decision — both on a global level and for an individual decision.
According to a recent study "State of Responsible AI" by market research firm Corinium and commissioned by FICO, 65% of companies surveyed cannot explain how AI decisions or predictions are made. Only a fifth actively monitor models for fairness and ethics. These are worrying numbers.
However, the need for explainable AI does not just result from principles of good corporate governance. In various discussion papers issued by the European Banking Association and national regulatory bodies, regulations are emerging that demand explainability at least for risk-related decisions. This makes explainable analytics an imperative for reasons of investment security alone.
Conclusion
Artificial intelligence and digitalization promise to significantly improve the cost structure in retail banking. As with all automation projects, however, it is important to use these tools carefully. But even intelligent technologies cannot magically fix mediocre processes. Therefore, it is worth focusing on the decisions and processes that deliver the greatest value to your organisation. When you do this, AI moves beyond being just another buzzword, and opens up new potential in retail banking.
How FICO Can Help You Advance Your Use of AI
- Discover our AI and machine learning solutions
- Read posts by our chief analytics officer, Dr. Scott Zoldi
- Download our paper on The State of Responsible AI
- Download our AI Playbook: A Step-by-Step Guide for Achieving Responsible AI
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.