Disruption and Transformation: Opposite Sides of the Same Coin
One company’s digital transformation is everyone else’s digital disruption

Digital disruption, customer centricity, and decisioning technologies have combined to create a dilemma for companies seeking to improve client satisfaction and retention: should they do nothing, and take a wait-and-see approach? Or should they take the initiative and go through the pain of reinventing themselves?
Just as Pablo Picasso once observed that "Every act of creation is first an act of destruction,” people have been drawn to the notion of symmetry and balance in our surrounding world throughout human history: the Roman god Janus; Yin and Yang; even The Force in Star Wars. We accept that all things exist as inseparable and contradictory opposites, and that these contradictions are inexorably intertwined: day and night, light and dark, peace and war, and life and death, in a never-ending dance. One remains until the other consumes it, ad infinitum.
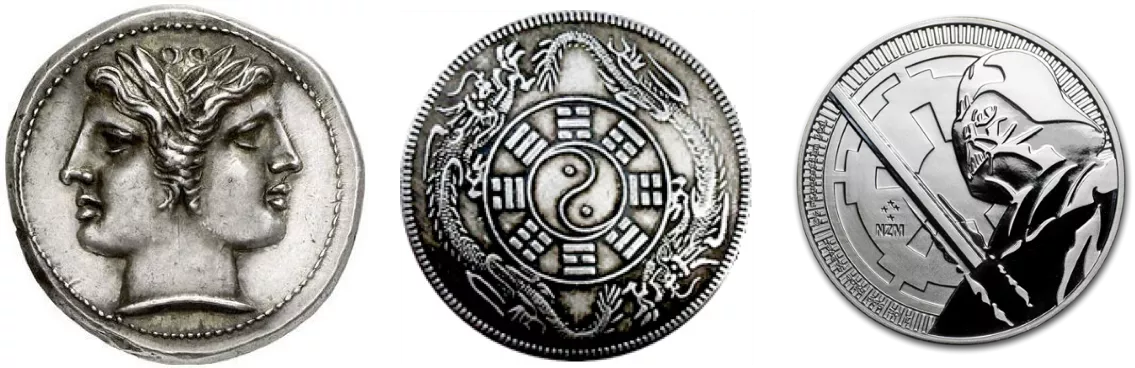
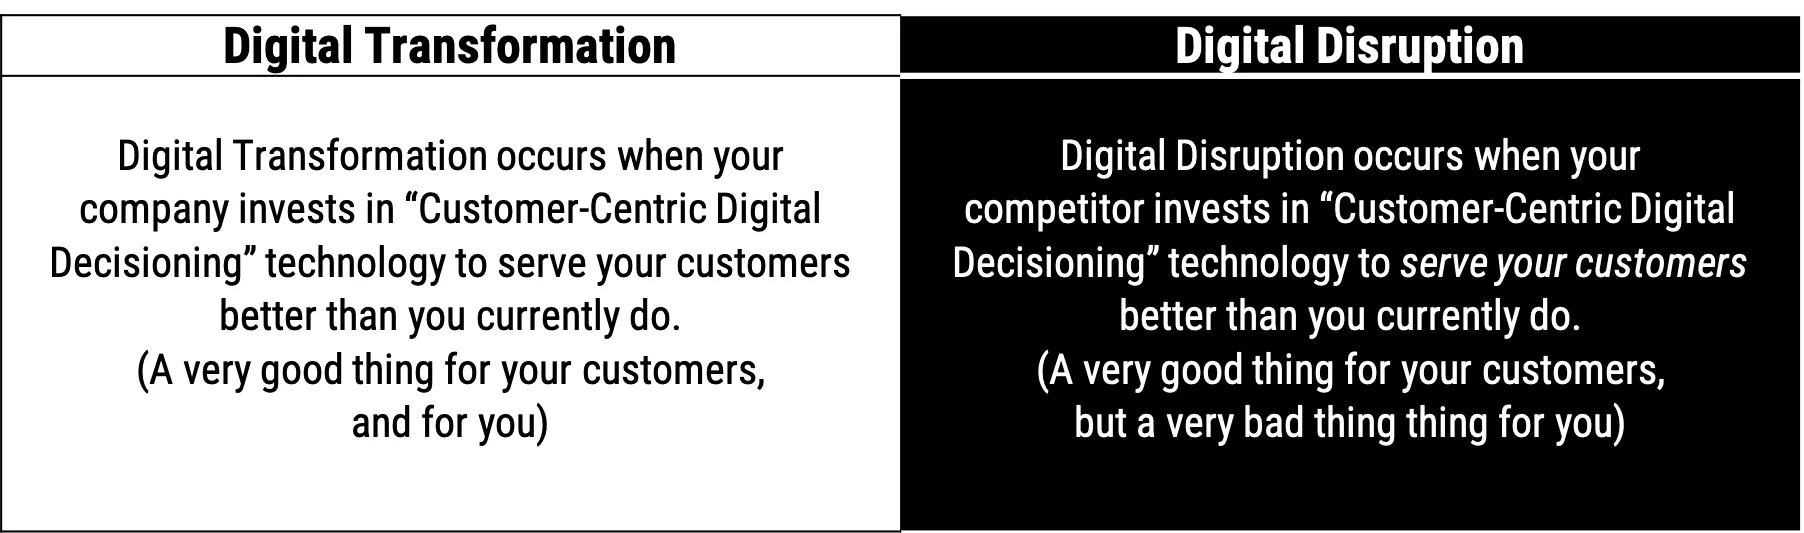
Many business people naively talk about digital transformation and digital disruption as if they were two unrelated things; they aren’t. They are opposite sides of the same coin. Technology and market forces have tossed that coin into the air; and before it lands, you have to choose heads or tails, or a competitor will choose for you.
Here’s why: one company’s digital transformation is everyone else’s digital disruption. You can be the disruptor or the disruptee. It’s your call. Either way, change is coming, and your customers will soon be getting options on the solution of his or her choosing. The only question is, will they stay your customer, or will they be lured away by a competitor?
Your options look something like this:
Disruption Isn’t Just Taxicabs and Retailers Anymore
Today, in hypercompetitive, disrupted industries, every customer touch becomes a zero-sum faceoff of its own: each win comes at a competitor’s expense, and their wins come at yours. Every Uber trip means a taxicab didn’t get a fare; every Kindle download costs bookstores a sale; every purchase on Amazon was one that didn’t happen at a retailer; and every booking at an AirBnB is one that didn’t occur in a hotel. But the results of each satisfactory experience are cumulative; people who try Uber, Kindle, Amazon, and AirBnB are very likely never turning back.
Could this level of disruption happen in banking and financial services? The experts believe that it’s already here: top analysts like Forrester, Gartner, and IDC – as well as top consulting firms like Accenture, Deloitte, E&Y, and McKinsey – are advising their banking clients to rebuild their businessesinto full, customer-centric operations as a way to stave off disruptors.
Venture capitalists are betting big on the disruptors: they plowed almost $12 billion in fintech and financial services investment last year, up 120% from the year before. Even the executive director of the Bank of England is telling bankers, “We can’t afford to be Uber’d; banks have to ensure we adapt, just like everyone else.”
Taking Control of Your Destiny
Probably the worst thing financial services companies can do right now is take a wait-and-see attitude. The reality is the longer you wait, the further behind you will be when disruption hits. And make no mistake: it will hit, if it hasn’t already.
Smart companies are already bracing for disruption by self-disrupting. They aren’t waiting around for change to hit them: they are seizing control of their futures, knowing that fortune favors the bold. Their strategy is to preempt digital disruption and customer defections by transforming themselves, their information assets, and their internal processes to achieve a 360-degree view of their customers called “customer centricity.” This means that every single customer touch – across your entire product and services portfolio – is optimized to create a customer experience that exceeds expectations for the duration of the customer lifecycle.
The road to customer centricity begins with digital decisioning – or in FICO’s case “Centralized Decisioning” – consisting of six essential steps:
- Adopting a unified, scalable decision platform across the enterprise
- Committing to creating personalized customer treatments at every touch
- Empowering business users to create and manage the strategies, rules and analytics
- Re-use connected decision assets across the customer lifecycle to improve decisions, while making them transparent and explainable
- Validate and simulate decisions before they are put into production, with dashboards displaying predicted and compared-to results
- Stop producing costly one-off “shelfware”: bring technologists and business SMEs together, to operationalize analytics and solve vexing enterprise challenges
By embracing these measures, companies can maximize the return-on-decisions across the enterprise and throughout the entire customer lifecycle. They can access more, and more types, of the freshest data available, in order to glean the types of valuable, actionable insights that drive winning customer strategies. Armed with those insights, they can take carefully-designed actions at the most opportune moment across all channels, as well as continually improve ROI by maintaining a deep, analytical understanding of the effectiveness of decisions and actions.
FICO Centralized Decisioning is recognized as a leading platform for enabling customer centricity. It is already helping companies worldwide to make faster, smarter, and more profitable decisions over the lifespan of every customer relationship. “Centralized” doesn’t mean decisions are made by a central committee; it means all customer-facing decisions and strategies across the enterprise are made with a 360-degree, connected focus with the customer at the center, using all knowable information, updated in real-time. This means that over time, customer insights incrementally grow deeper and more accurate with each iteration, resulting in increasingly higher return-on-decisions.
It also means that you are taking the offensive, not just acquiring and serving customers better than ever before… but being the disruptive force in your industry who sets everyone else into reactive mode. And when they are busy reacting to you, they are taking their eye off their customers.
The future of your company is too important to trust to a coin toss. Commit yourself to learning more about disruptive threats facing your industry, and the strategies that will separate the winners from the losers in the year ahead.
To read more about Centralized Decisioning, including case studies and whitepapers (registration may be required) please visit https://www.fico.com/CentralizedDecisioning
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.