Diversity and Governance: AI Breaks into the Boardroom
Dr. Scott Zoldi in conversation with Vanessa Colella, Chief Innovation Officer, Citi, Head of Citi Ventures & Citi Productivity

Artificial intelligence is today’s hottest technology—and how companies create and use unbiased AI should be a topic near the top of Boards of Directors’ agendas. AI is a Board-level issue because this technology makes decisions that profoundly affect all customers, in ways that can be positive or negative. This blog captures the extended conversation around “Diversity and Governance: AI Breaks into the Boardroom,” FICO’s recent LinkedIn Live broadcast featuring Dr. Scott Zoldi, Chief Analytics Officer at FICO and Vanessa Colella, Chief Innovation Officer of Citi, Head of Citi Ventures and Head of Citi Productivity.
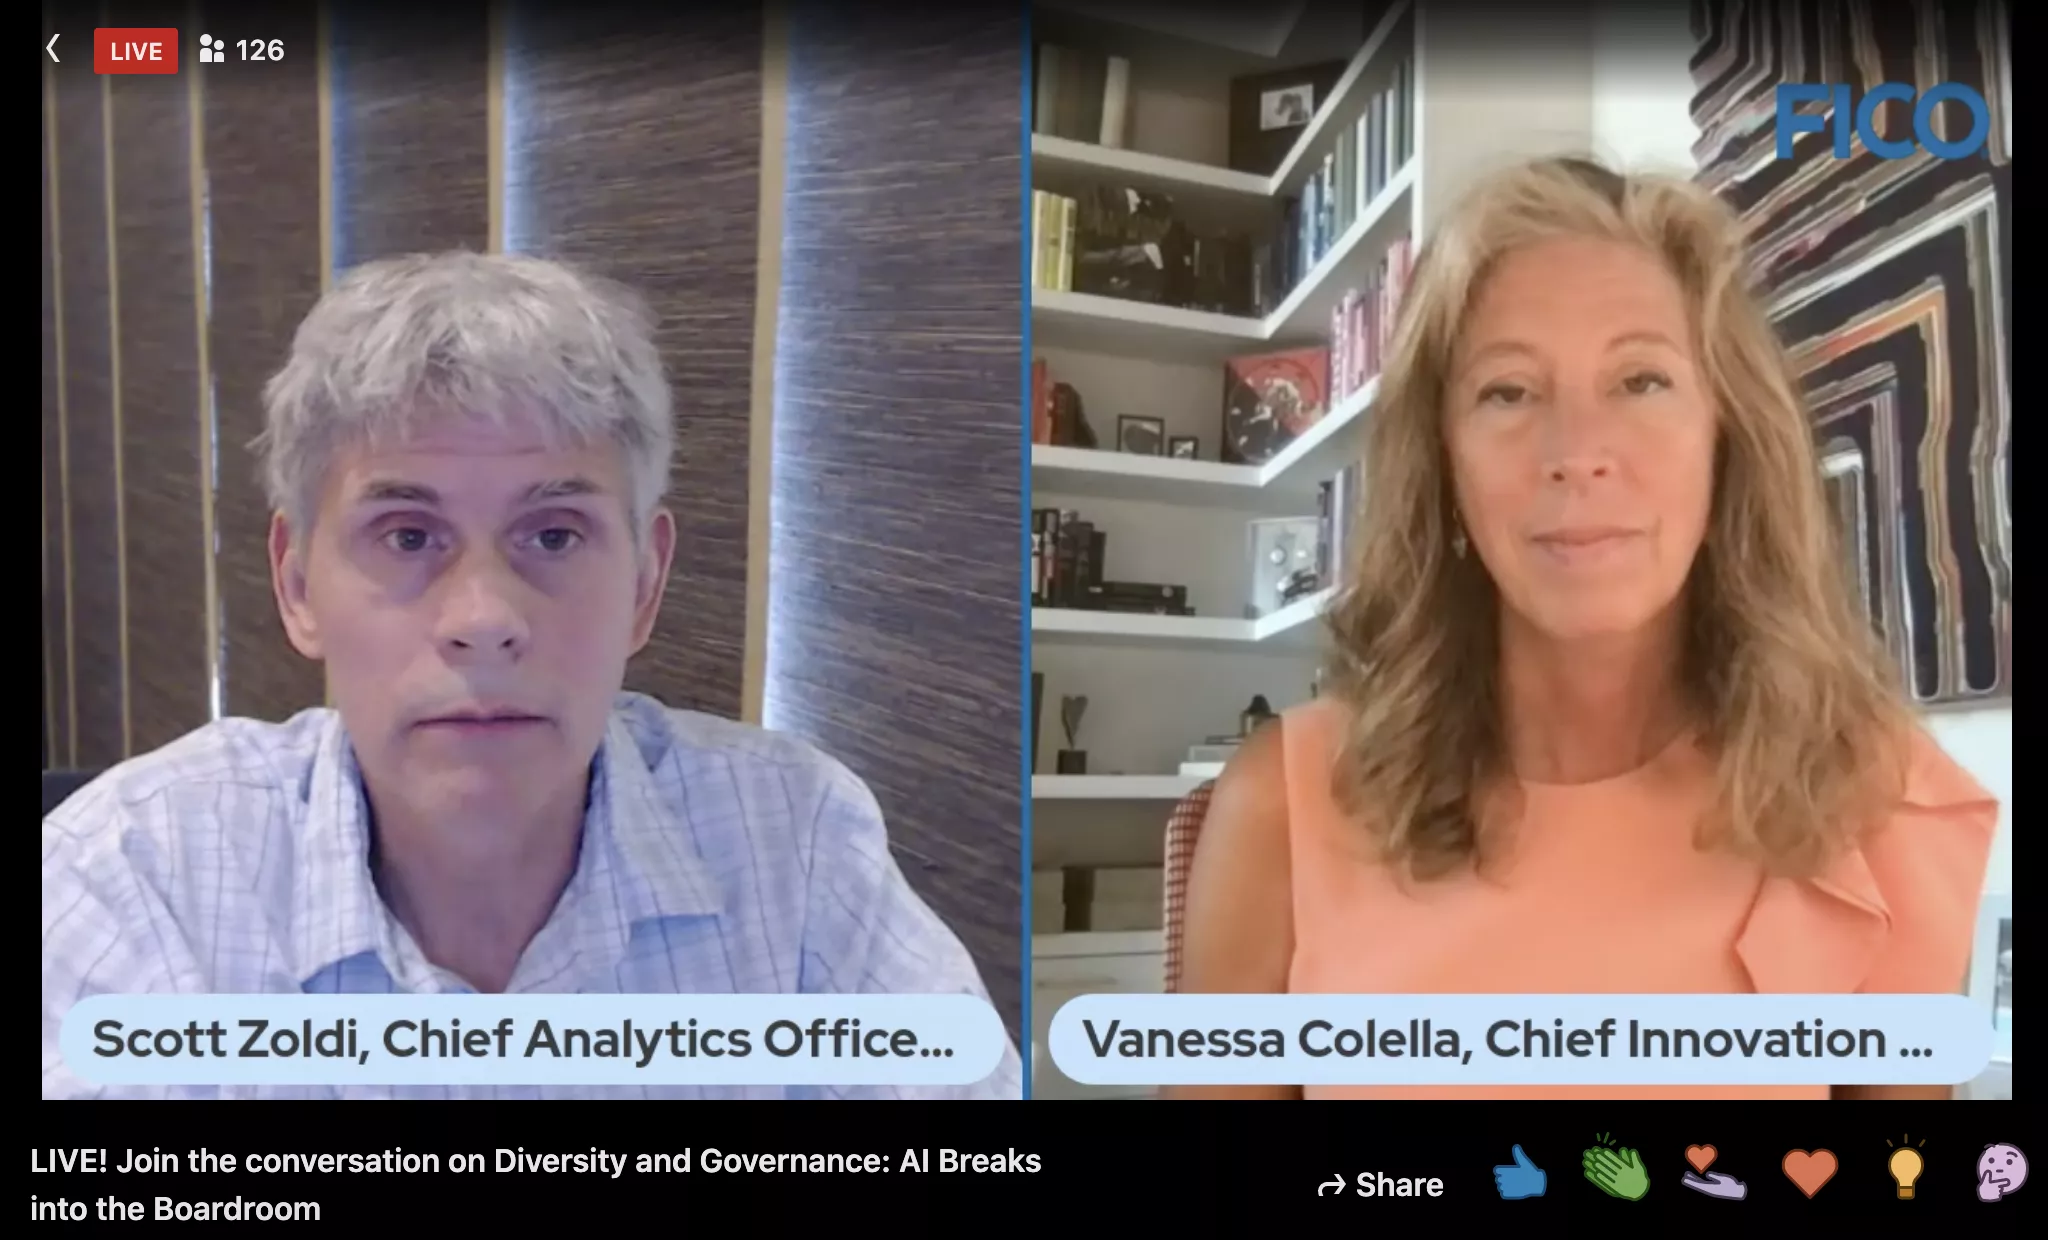
Scott: Vanessa, thank you for joining me to talk about diversity and governance in AI, and how artificial intelligence is breaking onto Boardroom agendas. One of the reasons, a widely reported statistic from FICO’s recent survey with Corinium Global on the State of Responsible AI, indicates that 65% of the analytics executives we surveyed can’t explain how their AI models make decisions. In your role, how do you see a greater understanding of how AI works at the executive and Board level as spurring innovation? What’s the connection?
Vanessa: AI has been around for a long time and just now are we at the precipice of seeing its true promise. We are now seeing a push for explanatory AI across the industry. This integration not only helps with making AI fairer and more unbiased, but can help improve AI models as well, making it smarter.
By gaining a greater understanding of which factors are the most important predictors, people can understand how to improve and develop new products for marginalized communities. For example, if we know that an AI for credit approval is biased and we understand it is because of homeownership, of which we know that marginalized groups have a lower rate, we can not only tune the model to be fairer, but can offer new products to help first-time home buyers.
Scott: Let’s talk about the role of diversity in AI innovation. How do you think about diversity in AI at a macro level, at an organization with 210,000 employees?
Vanessa: Large organizations should be representative of the demographics of the customers they serve. Diversity and the right culture will drive innovation and as we develop new AI solutions, that diversity will help to push boundaries, creating new sources of value and driving new outcomes for smarter AI usage and deployment.
Diverse teams are needed to develop any unbiased products, not just AI. As teams need voices of marginalized communities to be represented, they can more easily recognize when things are not right and how we can better serve all our customer segments.
Scott: How do diverse teams make a difference in building AI that is unbiased? How do you see this being realized at Citi?
Vanessa: One example is as part of Citi’s $1 billion Action for Racial Equity commitment announced in April, the Citi Ventures Studio team is working on REDDI, the short name for Racial Equity in Data and Design Initiative. The goal of REDDI is to develop standards for inclusive software design that eliminate bias, including within AI models, and help deliver equitable outcomes to the communities Citi serves.
Scott: I understand you have been working on a theory called Artificial Enlightenment, the idea that we should be evolving AI models and leveraging data to perform in situ analyses. Can you tell us more about this theory and how it could help incorporate more unbiased, diverse results?
Vanessa: AI is good at carrying out narrow tasks when there is an enormous amount of relevant data available, and the situation is fairly predictable. It falls short, however, when conditions are changing rapidly and randomly. These cases require a deep, contextual understanding of the situation and all its variables─the type of analysis the human brain was built for. That is why you can teach a seven-year-old child to safely cross the street in a few minutes, but it might take seven years to teach an autonomous car to do it.
As AI continues to develop, other applications of the tools are emerging. The same technological advances that enable AI—including vastly improved compute speeds, parallel processing, the ability to handle massive heterogeneous data sets, and cloud computing—can now be used to deliver the data people need to make better decisions in situ, that is, locally and in the moment.
Used in this fashion, these capabilities are beginning to give us actionable insights into global challenges such as climate change, public health, food production, supply chain management, and finance. This has the potential to create new opportunities for collaborative innovation to improve our interconnected society and open the door to an era of Artificial Enlightenment, or AE.
Scott: Companies are well-versed in the tenets of corporate governance: operating with accountability, fairness, transparency, and responsibility. In your view, how can Boards improve their ability to understand and trust AI by adopting a model governance framework based on this approach?
Vanessa: I believe the most important things a Board can do when adopting a governance model are establishing a one enterprise view and guidance for the understanding, use and deployment of AI. Second, making the necessary investment in training across the organization for all employees who will use the tool. One vision and education should be the core tenants.
Scott's next LinkedIn Live will be broadcast on August 3, in conversation with Ganna Pogrebna, Lead for Behavioral Data Science at The Alan Turing Institute. They’ll dive into the topic of AI and regulation in “Is Your AI Ethical? The Answer May Surprise You.” Sign up for the session here, and follow Scott on Twitter @ScottZoldi.

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.