How the Focus on NPL Is Changing Europe’s Debt Market
Are we making the progress we want to see — and regulators demand — on non-performing loans (NPL)?

Are we making the progress we want to see — and regulators demand — on non-performing loans (NPL)?
That’s the topic I explored with banking leaders from across the Europe, Middle East and Africa at our EMEA Risk Leadership Summit in May. Taking a step back from all the activity going on in this space, it’s clear that major shifts are occurring, but there are some surprising gaps.
Why Focus on NPL?
High volumes of NPL can cause a significant drag on a bank’s performance in the form of- Reduction in net interest income
- Increase in impairments costs
- Additional capital requirement for high-risk-weighted assets
- Lower ratings and increased cost of funding, adversely affecting equity valuations
- Reduced appetite for new lending
- Additional management time and servicing costs to resolve the problem
European banks have set NPL target rates and plans to achieve these. The biggest tool these banks will have to reduce their exposure to NPL will be to parcel them together and sell the portfolios, removing the loans from their balance sheets. Some of the banks with larger exposure are targeting a 60% reduction in their NPL stock in the coming years. Many banks in countries that have already under gone heavy restructuring are still in need of further reduction and have also set targets.
These efforts are having an effect, and the total NPL volume fell from its €1 trillion high in 2016, but still exceeds € 840 billion. The majority of these NPLs are corporate, but a significant proportion are consumer debt. Banks’ asset quality remains a major concern for the European banking system.
NPL Divides Europe
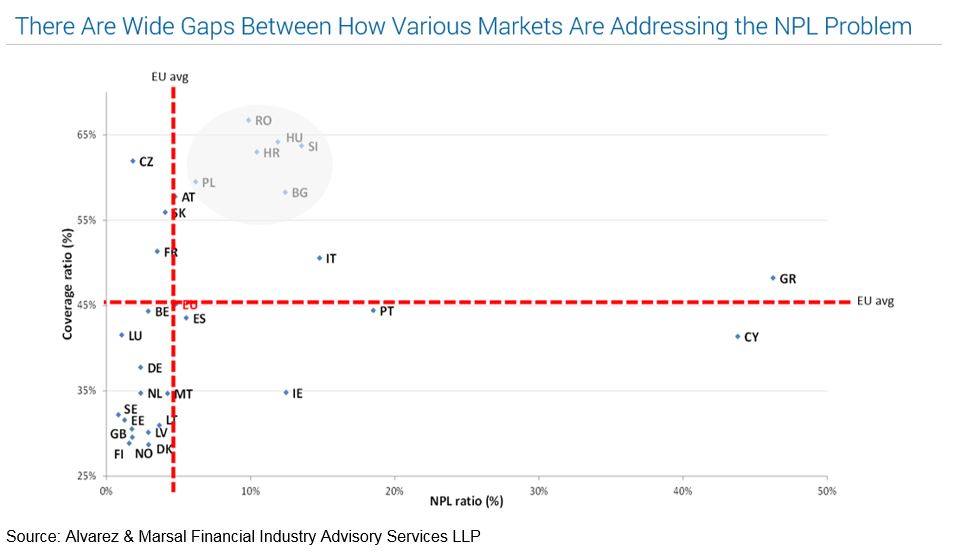
You can analyse the European landscape by dividing the countries into 3 blocks.Block 1 — Countries with NPL ratios > 20%
This block, which includes Greece and Cyprus, has seen little movement in the past three years in average NPL ratios and coverage percentages. Systematic barriers are in place restricting progress, such as restrictions in Greece on loan book sales. The vast majority of future loan book sales is likely to come from this block. The Loan Servicing Platform, a framework in Greece comprising investors and 3rd party servicers overseeing the effective restructuring and management of NPLs for a large number of banks in Greece, is expected to have an impact.Block 2 — Countries above the EU average NPL rate (5%) but below 20%
This block, which includes Ireland and Spain, is seeing the most improvement over the past three years, with falling NPL rates and increasing coverage ratios. These countries are actively addressing their issues through state Asset Management Companies, bad bank units and loan book sales. A large percentage of debt sale transactions originated from this block during last few years.Italy is the stand-out country in this group. Although its NPL rate is 14.8%, due to its size, the actual stock number is extremely large at over €300 billion.
Block 3 — Countries at or below the EU average
This block, which includes the UK, Germany, the Netherlands and France, has a similar trend to Block 2 but a much lower NPL rate. These countries have decreased their rates in past 3 years while increasing coverage to over 45%.This block includes large, systematically important countries to the EU. They were largely protected from massive NPL rates due to tighter lending laws before the crash.
Note: The NPL data in this article are from a presentation by Alvarez & Marsal Financial Industry Advisory Services LLP at our EMEA Risk Leadership Summit in May.
Changing the Debt Purchasers Market
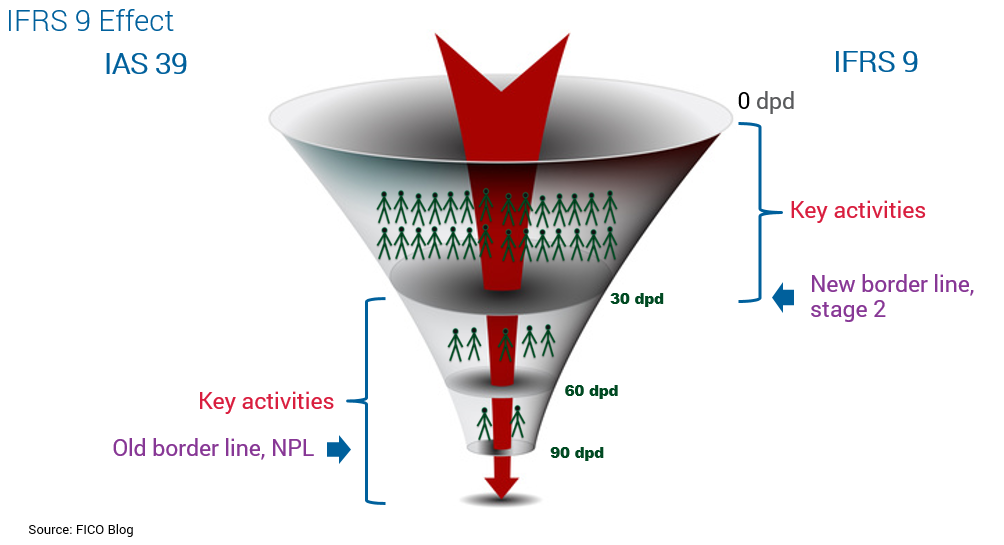
One of the big changes we see as a result of the NPL activity is in the debt purchaser market, where some of the larger firms — such as B2 Holdings and Hoist — have grown rapidly, as banks look to shed unprofitable portfolios. Debt purchasers and debt collection agencies are consolidating, innovating and in some places become the preferred location for financially vulnerable customers. This is driven to a large degree by regulatory pressures on banks to reduce their NPL, and also by a new force: IFRS 9.IFRS 9 accounting rules have effectively drawn a new border line for concern. Under previous regulation IAS 39, this border was at 90 days past due, when loans are classed as NPL. Under IFRS 9, this border has moved way up in the funnel, to 31 dpd, when customers (and all their accounts with the bank) move from Stage 1 to Stage 2 in terms of risk. At this point, the bank must increase impairment for the customer’s accounts from 12-month expected credit losses to lifetime expected credit losses. That’s a cliff-edge banks are naturally keen to avoid.
From NPL to NPE
Whilst focus may be on IFRS 9 and NPL, the reporting of NPE (non-performing exposures) will also cause changes in the creditor customer treatment strategies and that will impact the 3rd party sector. We are likely to see NPE as a primary group for debt sales, because creditors can’t afford to hold the capital coverage NPE will necessitate but do want to prove that there is performance value in these NPL that warrants stronger purchase pricing.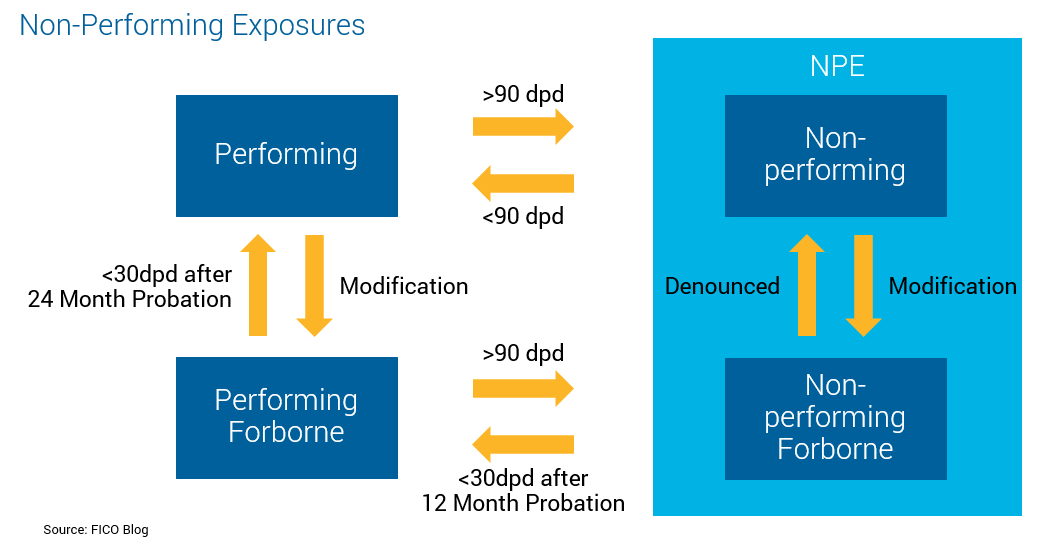
In my next post, I’ll discuss six steps banks should consider to focus on NPL and NPE.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.