Hyper-Personalization Survey Highlights Boardrooms' Blind Spots
New study from Forrester shows the value of hyper-personalization and the gaps businesses face today


Hyper-personalization is now front-of-mind among banking’s boardrooms. It’s also a minimum mandatory expectation among bank customers. Everyone is talking about it, and everyone is doing it — at some level.
The way we all bank has undergone a huge transformation — driven in part through technological innovation and in part through a post-pandemic cultural shift. Customers expect personalized engagement from all businesses they transact with, including financial services.
There's little patience for a one-size-fits-all approach. At the same time consumers are getting far more data-savvy. They know their personal information is valuable and many are reluctant to share it without getting something back in return, be it personalized offers, competitively priced deals, or tailored service.
But are hyper-personalization efforts effective? And more importantly, are customers convinced? Boardrooms know that an inability to deliver is costing in lost businesses — and it has emerged very few are satisfied with their institutions’ performance.
The findings are revealed in Unlocking Hyper-Personalization at Hyper-Scale. It’s a commissioned study conducted by Forrester Consulting on behalf of FICO. Feedback was analyzed from more than 300 senior decision-makers responsible for personalization of customer experience at banks across North America, Brazil, South Africa, UK and Thailand. The results yielded a mass of interesting findings and highlight where critical investments look set to be made within the next 12 months.
More than half of all decision-makers readily admit that hyper-personalization is the critical route to driving improved customer engagement, loyalty and reputation. A significant number also see it as a key building block to culture change, breaking down internal siloes and ensuring informed real-time insights from their deep investments in data.
But gaining a comprehensive 360-degree customer view continues to pose a challenge for many.
Acknowledging Poor Performance and Legacy Systems’ Impact on Personalization
More than one in three (+33%) respondents are dissatisfied with their firms’ abilities to successfully attract, engage, originate, on-board, nurture, or manage new and existing customers.
In fact, accurately understanding or anticipating customers’ needs, managing risk and detecting fraud, are all proving to be critical challenges for more than half (~55%) of all decision-makers polled.
The impact of legacy systems, the continued inability to hire or retain skilled talent, wrestling with compliance and regulatory demands — these are also hampering the ability to meet customer expectations for nearly half of respondents (~45%).
All of these are directly hitting banks' financial performance, competitive edge and their ability to deliver good customer experiences.
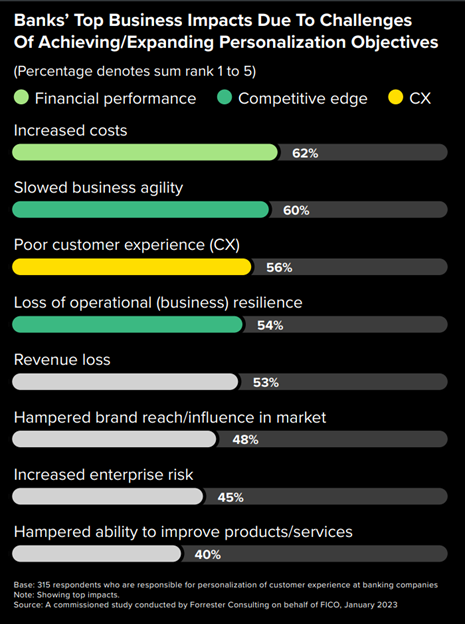
The impacts of failing to meet personalization challenges resonate right across the business, reflected by a mix of direct financial consequences, blunted competitive edge, and poor customer experience. Respondents who failed to fully meet their personalization demands reported seeing increased costs for nearly two-thirds (62%), poor agility (60%), inadequate customer experience (56%), loss of operational resilience (54%) and declining revenue (53%).
Many also admit to being hamstrung by a combination of legacy systems, lack of agility, talent retention and the day-to-day demands of regulatory compliance. As a result, firms are seeing rising operating costs, loss of market share and continued poor customer experience.
Key Impacts Driving Critical Investments
Analysis showed the top priorities for the year ahead among more than a third of the banks polled include ongoing simulation and testing of hyper-personalization strategies on customer data (42%). A similar number (40%), are set to enhance customer engagement through real-time decisioning, while 38% also plan to incorporate more third-party data and services.
Around a third of all banks are also keen to fill existing gaps in their toolkits. This includes investment in observability tools, execution and asset repository tools, while event management tools to support real-time data streaming and persistence tools, are all key areas of investment. Most notably, these are in simulation, visualization, optimization, contextual processing, composition and orchestration.
Step-Changes in Personalization Programs
Within the next 12 months, the vast majority of banks polled are set to significantly step-up their hyper-personalization programs. Research reveals nearly all (88%) plan to support personalization priorities through the deployment of analytics / machine learning to gather insights.
More than four out of five (82%) will be also supporting personalization programs through achievement of a single view of the customer through accurate and accessible data. At the same time, more than three-quarters (78%) plan to support personalization priorities through enhancement of customer engagement through real-time decisioning. A similar number (70%) plan to support personalization priorities through simulation and testing of personalization strategies on customer data.
Delivering Great Expectations
The impact of better data, insights, action, and outcomes capabilities is expected to make a significant improvement to KPIs. For instance, nearly three-quarters (71%) predict reduced costs, a similar number (69%) expect to see a spike in customer satisfaction, while more than half (+58%) anticipate improved loyalty and retention.
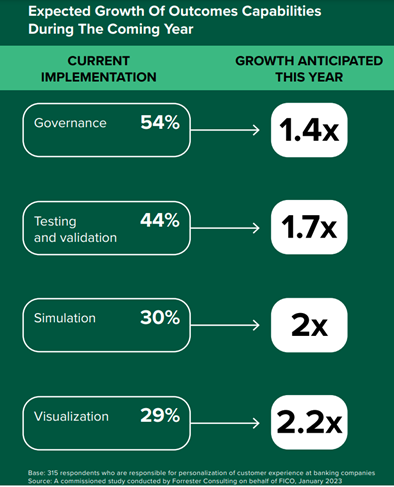
But it’s worth noting that more than half (+50%) of all business leaders surveyed also admit they continue to be hampered by siloed processes and siloed thinking. It’s a trend most prevalent in feature management, external data access and dataflow, contextual processing, decisions, plus the more critical predictive disciplines of governance, testing, visualization and simulation. It’s a near-uniform viewpoint. Significantly, around three-quarters (~76%) of all firms say they plan to invest in and implement all of these areas within the next 12 months.
Read the New Study
This is simply a brief glimpse of what your peers and fellow professionals are telling us. There is a mass of insights readily available in Unlocking Hyper-Personalization at Hyper-Scale.
How FICO Can Help You Unlock the Value of Hyper-Personalization
Contact us today to discuss how FICO can help you assign hyper-personalized offers to each client or consumer in real-time to maximize your sales and improve your customer loyalty and experience. Cloud-based or on-premises FICO AI-powered analytics solutions enable you to fully automate your marketing campaign, quickly respond to business requests, continuously improve marketing processes and develop hyper-personalized marketing strategies.
- Read Unlocking Hyper-Personalization at Hyper-Scale.
- Find out more about How to Unlock the Power of Hyper-Personalization.
- Read Hyper-Personalization and Prescriptive Analytics for Customer Offers.
- Read more on hyper-personalization in the Top 5 2023 Trends Redefining Banking Today.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.