FICO World 23: Unleashing the Power of FICO Platform
Creating next-generation customer experiences

An Engine for Next-generation Customer Experiences
FICO World 2023, is an embodiment of the collective vision and dedication of leaders, change agents, and revolutionaries like our clients, who are shaping the future of customer experiences. We have a once in a generation opportunity to create the next generation financial services ecosystem.
FICO is on a mission to unlock the potential of Applied Intelligence and create a connected end-to-end customer experience. As a company we have spent a tremendous amount of capital and resources, in building and developing what is going to be a platform that will power this vision.
In fact, we are so committed to this and believe in it so deeply that we have changed our mission Here it is: Applied Intelligence – powering your customer connections.
Innovation is incredibly important. There is no growth without innovation. Not anymore. And here’s proof.
Before the pandemic, Accenture surveyed over 8,000 companies across 20 industries and countries. They wanted to know how investing in technology innovation was affecting growth. Here’s what they found. The top 25 percent of companies that were investing the most in technology innovation were growing at twice the pace of the 10 percent that invested the least.
That was before the pandemic. You might think that the pandemic affected everyone equally. But of course, it didn’t. When Accenture ran the same survey after the pandemic, they found that the top 25 percent of companies investing in innovation --grew at 5 times the pace of the 10 percent who invested the least. It's clear that the leaders took a different approach to innovation than the laggards.
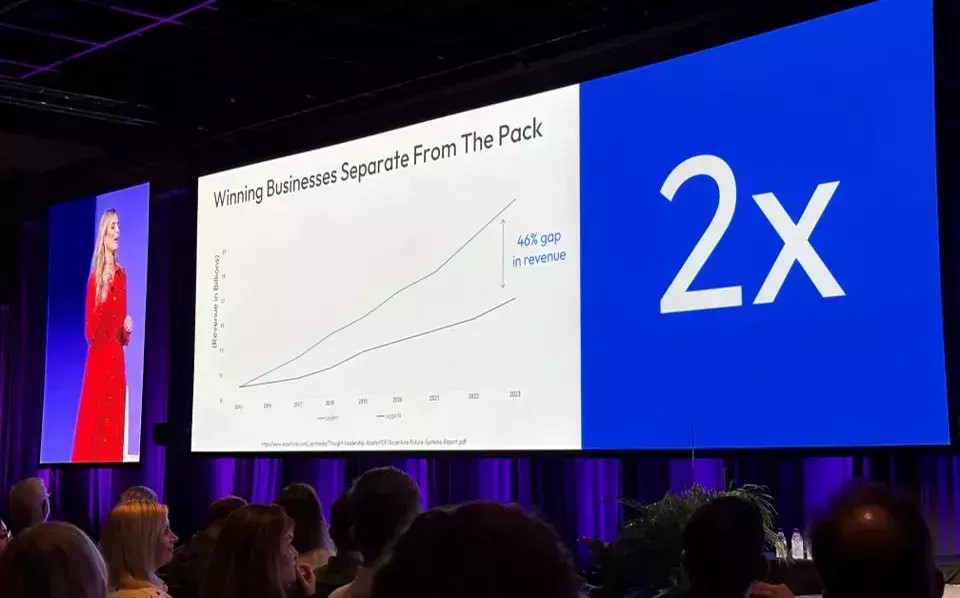
Leaders claimed they were getting value from AI by orienting around “Decision Outcomes” as opposed to less than half of the laggards. The delivery of outcomes is truly is about the operationalization of AI. Innovation is the key to growth. FICO is laser focused on innovation. But which innovation? Which direction? Where do you focus? Which market trends matter – both in business and technology? Let’s take a look at some of the market trends that may resonate and be top of mind or perhaps a challenge.
Market Insights Shaping the Strategy to Success
Innovation is the driving force behind growth, and FICO remains at the forefront, committed to pushing boundaries. It is crucial to identify the market trends and insights that truly matter to your business strategy, enabling you to stay ahead.
-
Digital Transformation: Across industries, optimizing customer experiences through digital transformation is a common challenge. Surprisingly, research reveals that only a fraction of the massive $1.3 trillion invested in digital transformation has effectively enhanced customer satisfaction and retention. We need to unravel the reasons behind this disparity and find solutions.
-
Business Composability: Breaking down monolithic applications into discrete components empowers organizations to swiftly create new solutions that align with evolving customer needs and market demands. According to Gartner, embracing composability enables organizations to outpace their competition by 80% in implementing new products and features—an undeniable advantage.
-
The Promise of the Cloud: The cloud offers a plethora of benefits, including accelerated time-to-market, cost optimization, and enhanced business innovation. One of our customers, Blu Nova, experienced firsthand the transformative power of migrating to the FICO Platform on the cloud. This transition liberated their CIO to focus on adding value to the business while leveraging the cloud's potential instead of managing an on-premise solution to remain operational in a complex environment.
-
Enterprise Artificial Intelligence & Machine Learning: Numerous analytics projects fail to deliver intended value due to challenges like data availability, misalignment between data science and business teams, and delayed model deployment. Operationalizing analytics and leveraging the power of AI can revolutionize decision-making and drive superior outcomes.
-
Hyper-Personalization: In an era defined by customer obsession, achieving hyper-personalization at scale becomes paramount. Real-time decisions should transcend speed and consider the context and knowledge gained from each customer interaction. Through hyper-personalization, you can ensure that your decisions and offers align with customer preferences while navigating the increasingly stringent regulatory landscape.
-
Open Ecosystem: Open ecosystems, as exemplified by Open Banking, foster marketplace approaches driven by the power of APIs. At FICO, we envision a platform that empowers you to build upon our foundation, unlocking limitless possibilities to create your own tailored solutions.
Each of these market trends plays a pivotal role in shaping the future of your business and the experiences you deliver to your customers. By understanding and embracing these trends, you can unlock new possibilities and drive strategic outcomes.
We have been listening very carefully to your ideas and your feedback. In many cases we have partnered with you to deliver the value propositions and design principles that are core to FICO Platform to ensure it delivers on the outcomes you need.
With FICO Platform we are giving you an engine for your own intelligence revolution.
To bring this to life, we are again brining back our fictional character 'Jane' whose journey embodies the impact of FICO Platform in the real world. Jane's stories, at the YouTube link below, help to illustrate the transformative potential of our platform.
Let us embark on this journey together, as we explore the boundless potential of the FICO Platform and witness the transformative power of intelligent customer experiences.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.