Persistent Debt Regulation and Advanced Analytics
Here's how decision optimisation can improve cardholders' strategies to comply with persistent debt regulation and help consumers meet their credit burdens.

The Financial Conduct Authority of the United Kingdom (FCA) has recently introduced new rules to avoid long-term indebtedness of credit card holders. As per this regulation, a cardholder is in persistent debt if payments against interest, fees and charges exceed amortisation payments over an 18-month period. The 18-month period is reset if the card balance falls below £200.
Persistent debt is a situation that tends to occur with customers who choose to make minimum payments only. With typical monthly interest rates between 1.5% and 2.5% (18% to 30% p.a.), a monthly minimum payment of 2.5% will systematically lead to a persistent debt situation. Some high-interest products even lead to persistent debt situations when more than the minimum payment is made.
While it seems to be the aim of the FCA to ensure that amortisation exceeds interest and fees, the persistent debt regulation surprisingly does not regulate minimum payments to exceed the interest rate by a factor of two. Instead, the policy requires card issuers to take a number of escalating steps, informing the customer after 18 and 27 months of persistent debt, and eventually going through a forbearance process before month 36, which might include actions like card closure and interest waivers.
My colleague Stacey West has recently blogged about some of the operational implications of the persistent debt regulation. Today, we will look at this topic from a decision analytics perspective.
Decision Options
For new accounts, card issuers can avoid the challenges arising from persistent debt entirely by setting the contractual minimum payment rate at least to double the value of the monthly interest rate. For products which accrue substantial fees, these might need to be considered for the minimum payment as well. In general, affordability checks will need to assess if customers can make sufficient payments avoid a persistent debt situation.
For existing customers, increasing the minimum payment can prevent persistent debt situations, but requires additional considerations. Customers making average payments in excess of the minimum payment and customers at low to medium utilisation levels might easily be able to meet higher minimum payment requirements. However, customers at high utilisation levels with low to minimal payment to balance ratios might not be able to make larger payments – whether or not an issuer increases the minimum payment terms, or the customer is implicitly required to increase payment levels to get out of the persistent debt situation. This also suggests that, for customers who do not have the financial capacity to stay out of a persistent debt situation, the credit limit provided might be too high considering the new regulation.
Persistent Debt Decision Tree Example
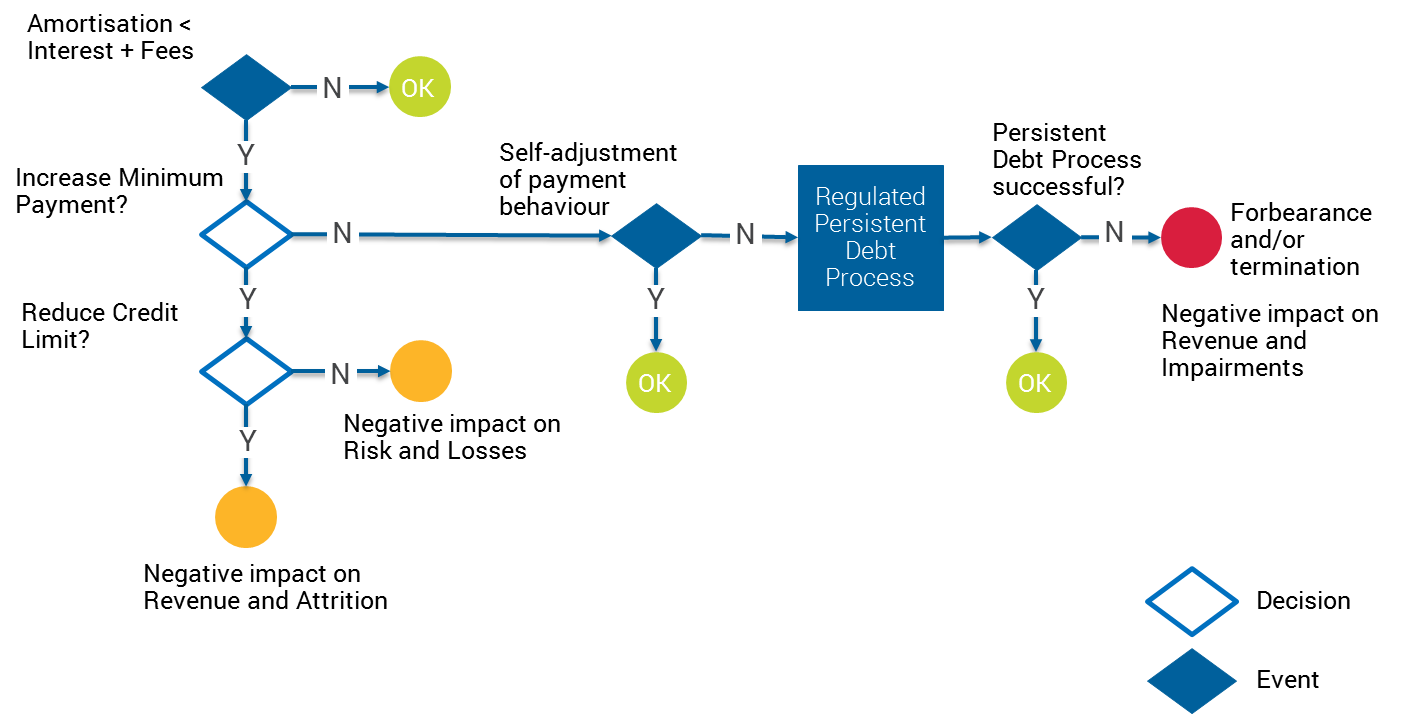
For customers who typically make minimum payments only, this gets us to the following decision options:
- Leave the minimum payment as it is and hope that the customer’s payment behaviour changes later or can be influenced by the mandatory persistent debt process. If unsuccessful, this might lead to forbearance measures, card closure or write-offs.
- Increase the minimum payment to a level that prevents persistent debt situations. However, this might drive customers with insufficient financial capacity into arrears, eventually leading to account termination and write-off.
- Decrease credit limit to a level where an increased minimum payment remains affordable for the customer even at high utilisation. However, this might negatively impact interest revenue and could trigger attrition if the customer wants to maintain the credit line or feels inappropriately treated.
When deciding whether to modify minimum payment and credit limit, the financial impact of the respective outcomes should be considered. If this decision is made at account level rather than at portfolio level, more appropriate decisions can be made, and unnecessary financial impact can be avoided.
How Analytics Can Help
Analytics can help to predict the probabilities of the respective alternative outcomes. For example, analytic models can predict the probability of a customer moving into the regulatory milestones at 18, 27 and 36 months, and hence can help to identify customers who should be contacted ahead of reaching these trigger points.
Analytics can also help to predict how customers are going to react to modified minimum payments and modified credit limits, and how such changes are going to impact revenue, attrition and delinquency levels. In that context, FICO’s Risk and Affordability Decision Suite can help issuers understand the financial capacity of customers, and hence their ability to make payments that get them out of the persistent debt situation.
Decision optimisation can help to balance the draw backs of the alternative outcomes, including revenue impact, losses and attrition. Combining multiple action-effect models into a decision framework, optimisation can simulate portfolio performance in alternative scenarios, and prescribe a treatment strategy that maximises or minimizes a given objective (such as profitability) under chosen constraints (such as attrition goals, revenue targets and operational capacity).
For example, decision optimisation can identify which customers should be subject to modified minimum payment and credit limits. Optimisation can also help to identify which customers in persistent debt should be contacted ahead of the regulatory milestones. In both cases, optimisation would help to understand the financial dynamics and trade-offs between revenue, losses and attrition.
When addressing persistent debt, don’t just look at it as an operational challenge. Treat it as a decision problem and gear up your analytic tools to address it.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.