FICO Safe Driving Score Predicts Likelihood of Future Collisions
The FICO Safe Driving Score provides a consistent and objective measure of driver risk and safety based on driving behaviors.

Despite advancements in safety technology, road fatalities are on the rise. Per the National Highway Traffic Safety Administration, human error accounts for 94% of crashes. FICO, along with global risk management leader, eDriving, firmly believes that proper education and reinforcement of safe driving behaviors can help make roads safer and potentially save lives, including for fleet drivers of all types of vehicles, driving for varied work purposes in all types of conditions, and others.
Pertinent data and prudent application of predictive analytics can provide insights into helping identify and reinforce safe driving behaviors.
FICO launched the FICO® Safe Driving Score in partnership with eDriving’s smartphone application, MentorSM in October 2016. Since then, the underlying model and application have both been fine tuned to the specific needs and requirements of Fleet Safety Management programs and adopted by global industry leaders with fleets of tens of thousands of drivers in service, delivery, and sales sectors.
The FICO® Safe Driving Score leverages telematics-based driving data provided by Mentor to predict the likelihood of future driving incidents by evaluating driving behaviors, such as acceleration, braking, cornering, speeding and cellphone distraction. Designed to be at the heart of the Mentor smartphone application, the FICO® Safe Driving Score provides a driver’s risk score after each valid trip and over time. The higher the score, the more likely a driver is to display safe driving behaviors and to avoid collisions in the future.
Providing a consistent and objective measure of driver risk and safety based on driving behaviors, the FICO® Safe Driving Score is poised to become the industry standard for predicting driver risk.The FICO® Safe Driving Score offers a significant level of transparency and insight which is shared with drivers who use Mentor on an opt-in basis, wherein location data is shared only with the driver. This provides drivers with actionable insights into what specific driving behaviors they need to demonstrate to improve their scores or to maintain current high-level scores.
Our most recent analytic effort validated the ability of the FICO® Safe Driving Score to predict drivers’ propensity to be in a collision using data from an independent sample of drivers. In this effort, we leveraged naturalistic driving data from a third-party research study, the 2ndStrategic Highway Research Program (SHRP2), spanning three years, 3,000 drivers and over 30 million miles driven (Dataset 10.15787/VTT1/IEKRD3).*
We designed the FICO® Safe Driving Score to zoom in on these key dynamics between various driving behaviors and their relation to subsequent collisions. Most importantly, in the preponderance of cases we examined, we have been able to demonstrate that drivers identified by the FICO® Safe Driving Score as being higher risk for having future collisions are, indeed, more likely to incur a collision in the future than those identified as lower risk.
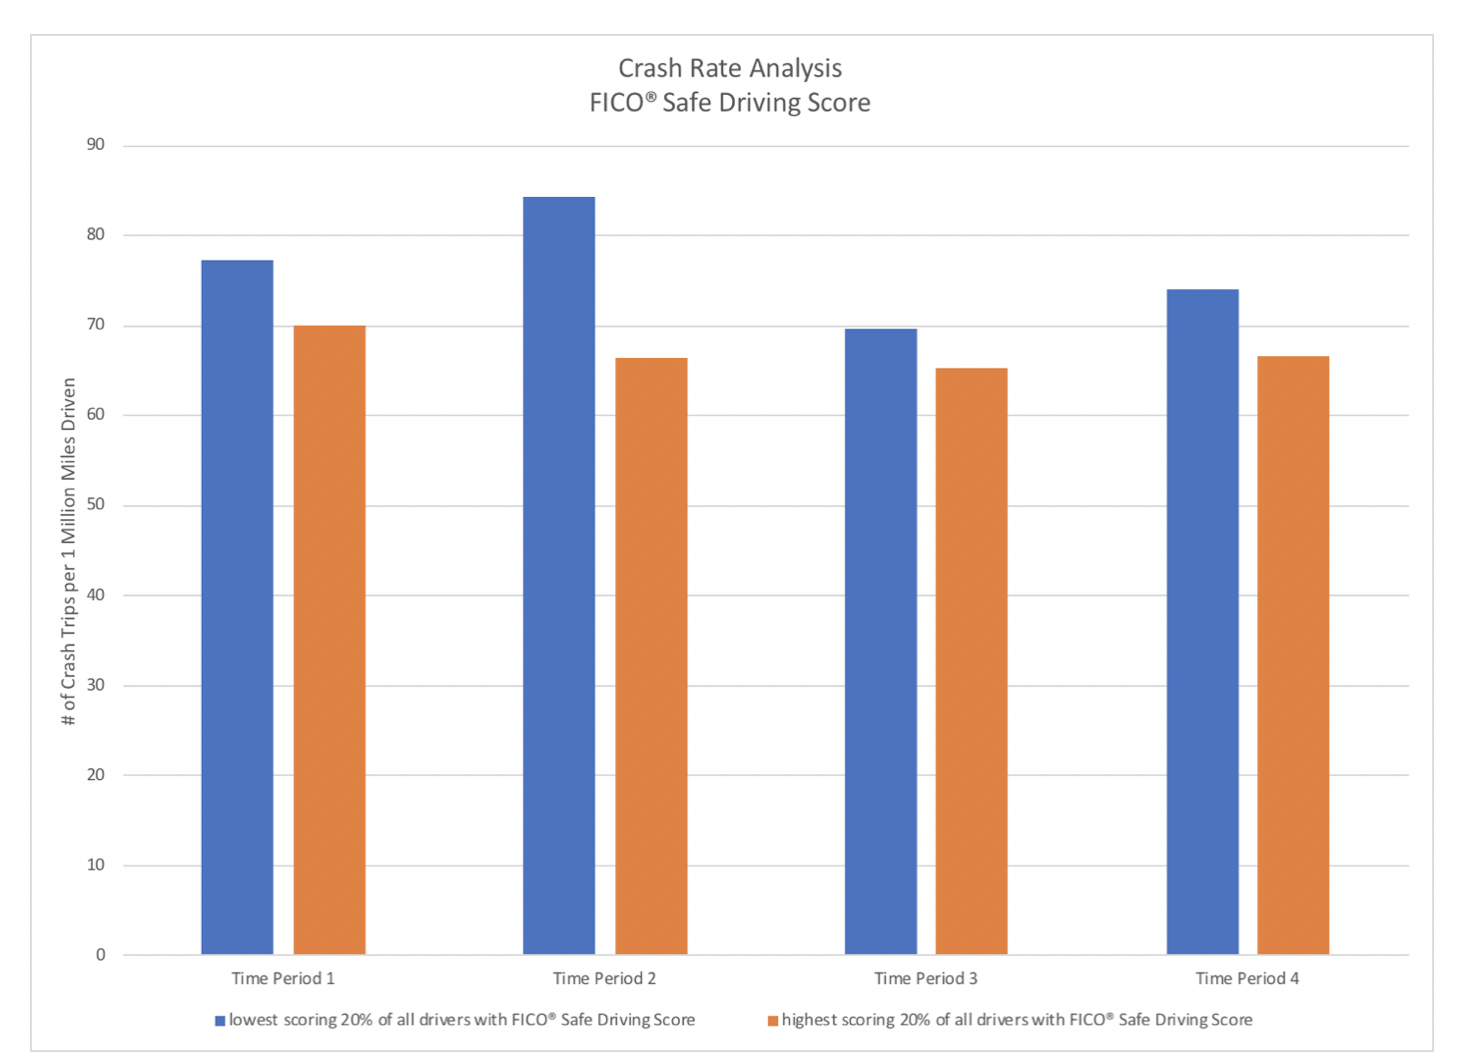
As this chart illustrates, the lowest scoring 20% of drivers are up to 30% more likely to have a collision in the future than the highest scoring 20% of drivers.
Furthermore, our analysis has concretely verified the assumption that unsafe driving behaviors, such as hard braking events, are correlated with higher risk of future collisions.
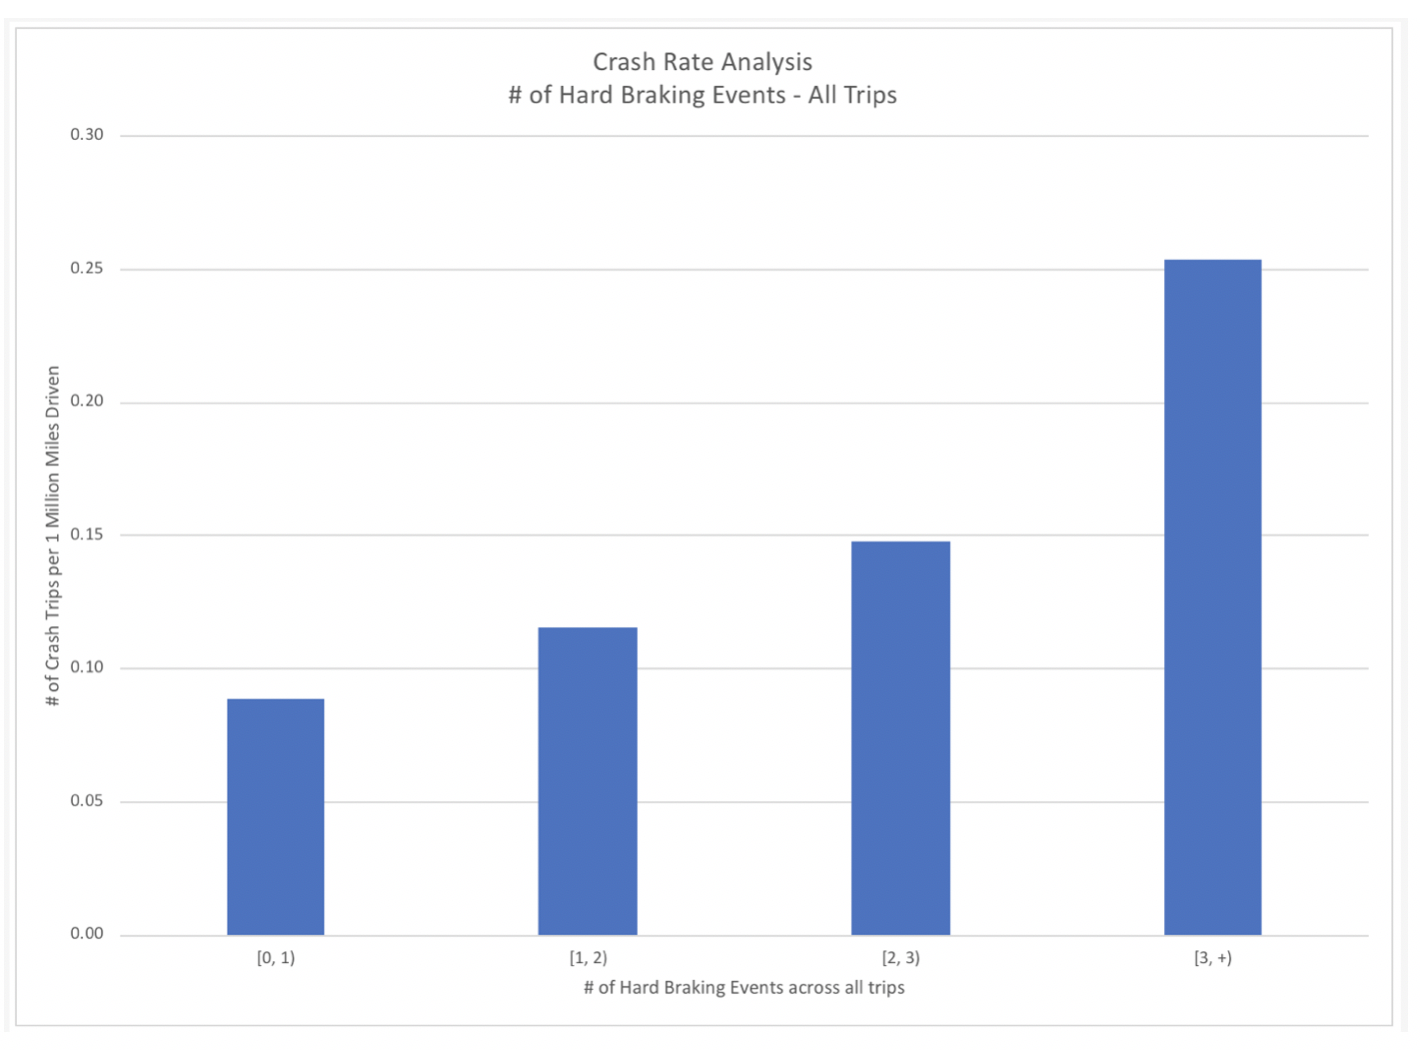 As the above chart demonstrates, trips with three or more hard braking events are more than 2.5 times more likely to result in a collision than those with no such events.
Our analysis to date has offered very solid evidence of the efficacy of the FICO® Safe Driving Score in predicting future collisions. And, yet, there is an opportunity to continue to build on this strong foundation. Predicting future collisions based on telematics-based driving data alone is challenging – the data can be noisy even within a somewhat “controlled” environment; the behaviors can vary based on extraneous events such as weather, traffic flow, or even mood of the driver; and connecting the telematics-based driving data to the outcome (collisions, losses, etc.) can be expensive and takes time. In spite of these challenges, the analysis of the SHRP2 data has provided significant insights that we will leverage to continue to improve the FICO® Safe Driving Score modeling, giving Fleet Safety Managers even more powerful tools to help their employees return home safe to their families every night.
*The findings and conclusions of this paper are those of the author(s) and do not necessarily represent the views of VTTI, the Transportation Research Board, or the National Academies.”
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.