US Bankcards Industry Benchmarking Trends: 2022 Q4 Update
Bankcard delinquencies continue to rise, higher losses are coming in 2023

FICO releases quarterly US Bankcard Industry Benchmarking trends, to catch up on the last quarter click here.
Another full year is in the books
As 2022 came to a close, the economic environment in the United States is teetering on the edge of a recession. Inflation is easing as funding rates have risen to 15-year highs, but the technology sector is beginning to lay off employees in masses – through 2022 low levels of unemployment kept the U.S. out of recession even when growth was negative. Despite lower energy prices, the cost of housing, food and services continues to increase to all-time highs causing consumers to tighten their belts even more than before.
The numbers: Annual GDP for 2022 released by the U.S. Bureau of Economic Analysis showed the economy grew at a pace of 2.1%. The first two quarters of 2022 were slightly negative (Q1: -1.6%; Q2: -0.6%) but then the economy returned to growth in Q3 and Q4. Expectations from Visa are that the GDP will turn negative once again in Q1 and Q2 of 2023 leading The National Bureau of Economic Research to declare a recession. The two main differences this year vs. 2022 are that the housing market has slowed down dramatically (sales are down 35.4% from November 2021 to November 2022) and the unemployment rate is expected to rise to 4.6% according to the Federal Reserve forecasts. The year-over-year calculation for the Consumer Price Index, also known as inflation, slowed to 6.5% in December; however, prices remain at all-time highs with the Consumer Price Index flattening between October to December.
What does a recession mean for consumers trying to keep up with their payments?
Although the overall macro economy may not directly impact individuals, the environment that develops into a recession affects households in various ways.
Increasing of the fed funding rates leads to higher interest rates when seeking new credit or carrying balances on credit cards. For example, the average interest rate on credit cards accruing interest in Q4 2022 was 20.40% compared to 16.44% in Q4 2021 (Source: Federal Reserve G.19 report on Consumer Credit). The difference in interest rate amounts to ~$30 more in interest paid each month per $10,000 of revolving debt – making or breaking some budgets, especially with elevated prices of goods.
An increase in the unemployment rate from 3.5% to 4.6% also means that ~1.8 million more people will be out of work over the next 12 months. With savings rates down and limited government assistance available, more consumers depend on their income to pay for daily expenses and pay down debts.
The following card performance metrics help us understand the impact of the macro environment on the credit card industry at an aggregate level. These figures represent a national sample of approximately 130 million accounts that comprise FICO® Advisors’ Risk Benchmarking solution. The data sample comes from FICO client reports generated by FICO® TRIAD® Customer Manager and Adaptive Control System solutions.
Usage & Payments
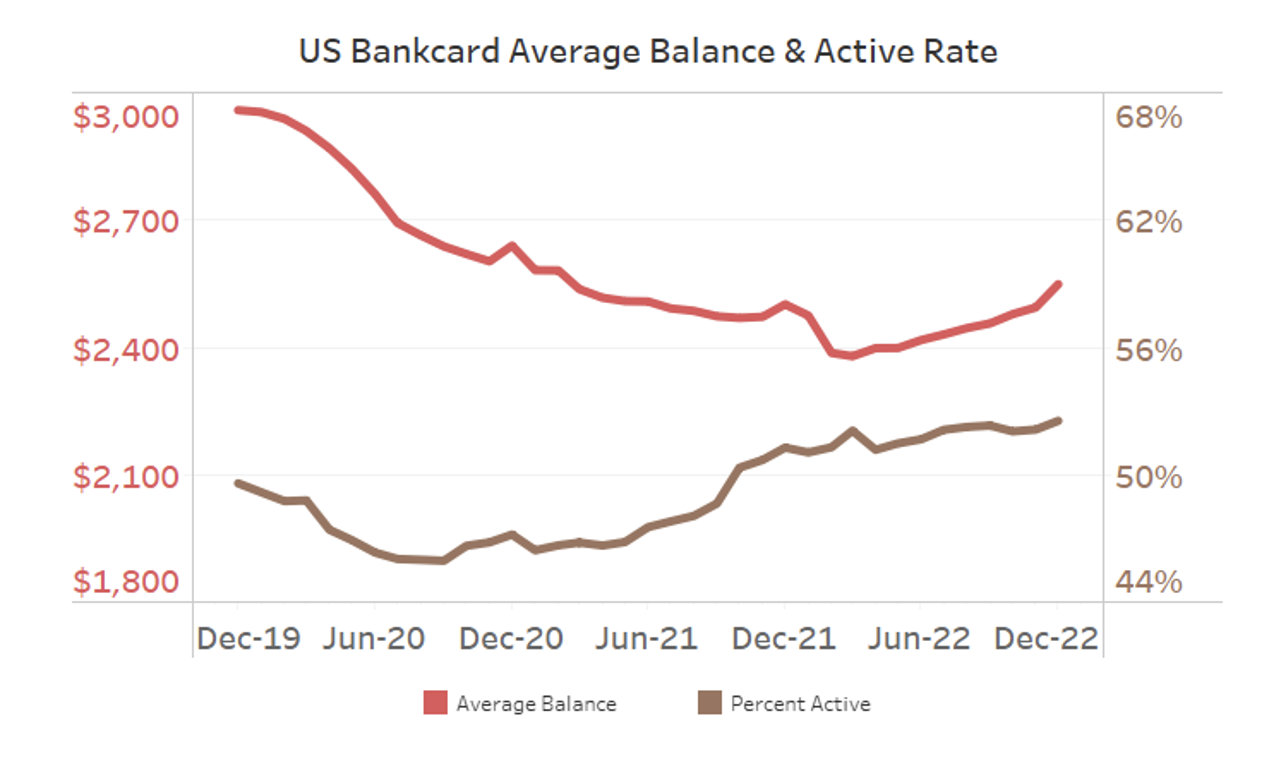
More consumers turned to credit in 2022 to help cover their everyday purchases and are revolving a higher percentage of that spend. The average balance of $2,549 has increased 7.1% since March 2022 and is up 1.9% compared to December 2021 with average monthly spend staying flat. Not only are balances increasing, the percentage of credit cards that are being used each month is substantially higher than prior to COVID when the active rate was very stable around 49% (December 2022: 52.5% vs. December 2019: 49.6%).
Throughout 2022 we have been discussing how average balances trending towards pre-COVID levels is positive news. This, combined with higher active rates, is exactly what Marketing departments strive for. However, now more than ever, Risk departments and Collections Operations are feeling the pressure that the balances being added may eventually turn into higher losses for the issuer.
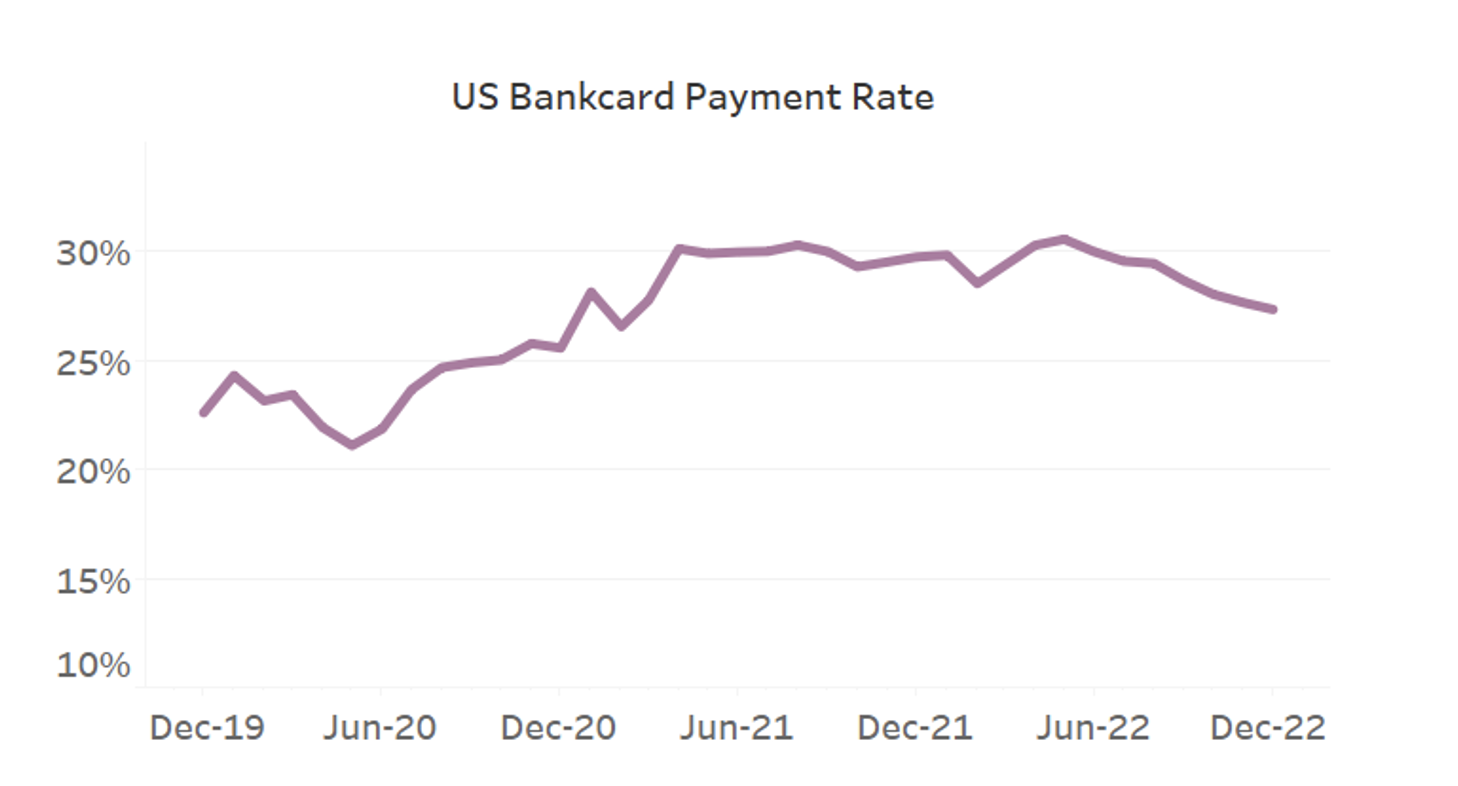
Showing more signs of consumer stress is the payment rate. This metric is calculated as the percentage of overall balance that is paid back each month. Consumers remained confident through the end of 2021 and into 2022 leading to record high payment rates. Unfortunately, the past seven months have returned decreasing rates landing at 27.3% in December, an 8.1% drop year-over-year.
Delinquency
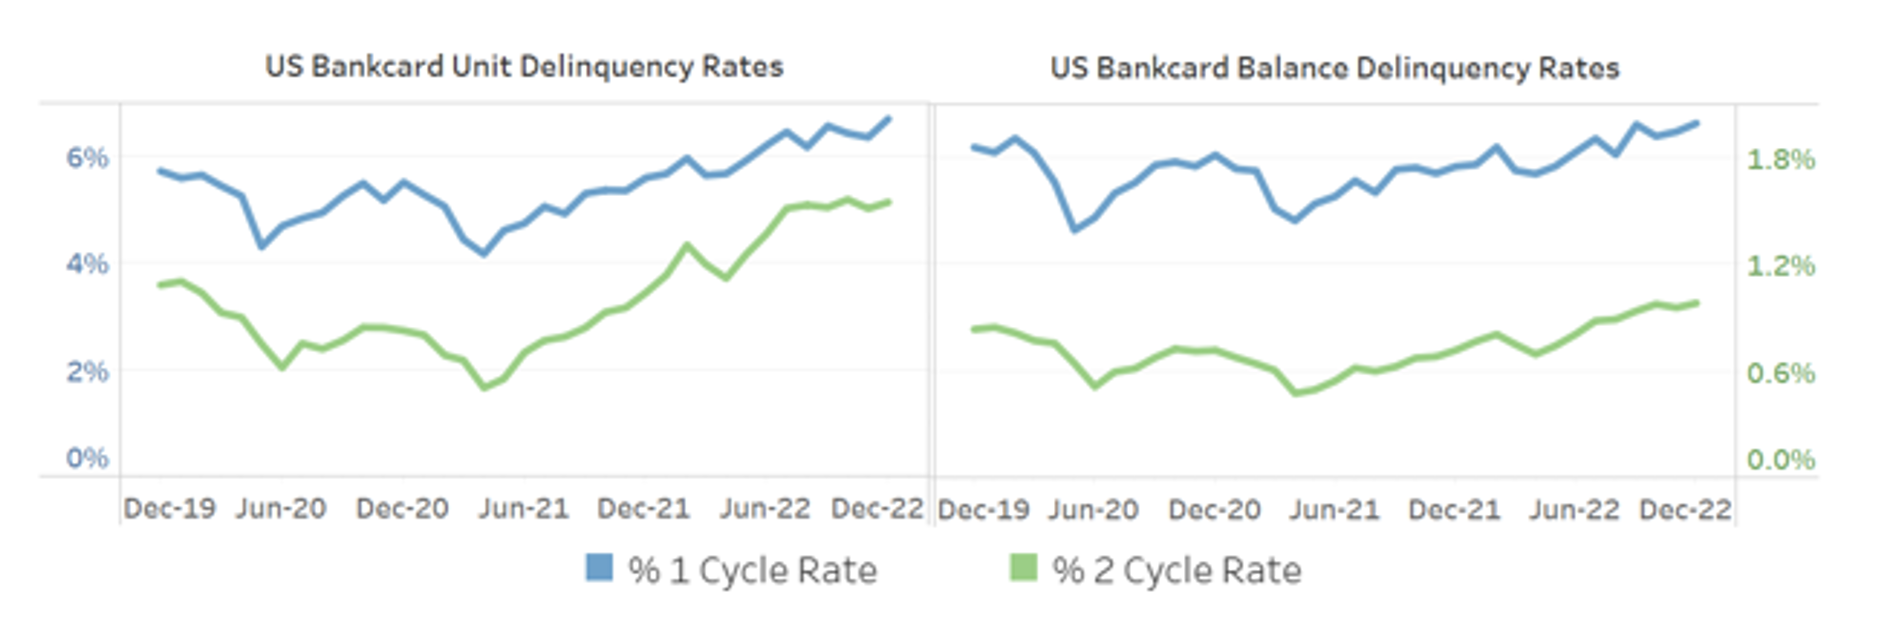
Higher balances and lower payment rates lead to turmoil in trying to keep customers on track. The percentage of accounts missing one or two payments have been trending upward for the past 20 months with no signs of slowing down (up 19.7% and 49.3% year-over-year, respectively). The percentage of balances that are past due have exceeded pre-COVID levels as well, which means that issuers will be taking on higher losses in 2023 than over the past three years.
If consumers are having trouble making their payments, the best course of action is to call the credit card companies and explain the situation as soon as possible. Most companies offer short-term or long-term payment plans depending on the expected length of the hardship. Tools at myFICO.com are also available to help consumers track their credit usage and FICO Score. There is a myriad of articles and community posts to help consumers understand the impact of taking on new debt, increasing revolving debt load or missing payments.
Based on the trends we have reviewed and predictions for 2023, it may be a difficult year for many consumers and institutions. Risk Managers should be reviewing lending strategies to ensure customers are receiving the right treatments across the lifecycle and getting the help that is needed if debts cannot be fulfilled. Reach out to your Solution Success Manager or Client Partner for a discussion and currect state assessment if you need any help completing this evaluation.
If you have questions or are interested in discussing these insights in more detail please contact me, Leanne Marshall, through comments on this blog or at leannemarshall@fico.com.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.