Composable Architectures: Why Now and What’s Next
Composable architectures are driving IT’s evolution by enabling greater flexibility, scalability and resilience

Composable architectures have emerged as the cornerstone of modern enterprise innovation. As organizations contend with market disruptions, legacy integration challenges, and relentless demands for agility, composable architectures provide both a philosophy and a technical foundation for building resilient, scalable, and adaptable platforms. This post explores what is driving the need for composable architectures, defines the concept and its core principles, examines where the industry stands today, and considers future trends, culminating with how FICO is harnessing composable architecture to power FICO Platform.
What Is Driving the Need for Composable Architectures?
IT departments across industries are in the midst of a profound transformation, fueled by several converging factors:
- Market Disruption: The pace and magnitude of market disruptions have accelerated dramatically. Technologies such as artificial intelligence and machine learning are reshaping industries overnight. The COVID-19 pandemic forced organizations to rethink their operations and accelerate digital transformation. Enterprises are now expected to respond to change at lightning speed, with little tolerance for slow adaptation.
- Hyper-Personalization: Customer expectations have shifted from generic offerings to highly personalized experiences. Whether in financial services, retail or healthcare, businesses must now tailor products, recommendations, and interactions to the unique needs of individuals. This demand pushes IT teams to build flexible, granular systems capable of rapid configuration and deployment.
- Legacy and Modern System Integration: The average enterprise is a patchwork of legacy systems, modern cloud platforms and cutting-edge microservices. Integrating these disparate technologies remains a thorny challenge. Organizations want the innovation and scalability of cloud-native services while preserving the value and reliability of legacy investments.
- Speed and Operational Risk: Time-to-market pressures mean organizations must deliver new capabilities quickly, often with minimal disruption. Business leaders expect IT departments to support faster launches, continuous improvement, and rapid experimentation — without increasing operational risk.
These interconnected drivers create an environment where traditional, monolithic approaches to application development and IT infrastructure simply cannot keep pace. The answer, increasingly, lies in composable architectures.
Defining Composable Architecture
At its core, a composable architecture is a collection of modular, interoperable components or services. Rather than building applications as single, monolithic entities, composable architectures break them into finely grained building blocks that can be assembled, disassembled, and reassembled in countless ways—enabling composability within the business.
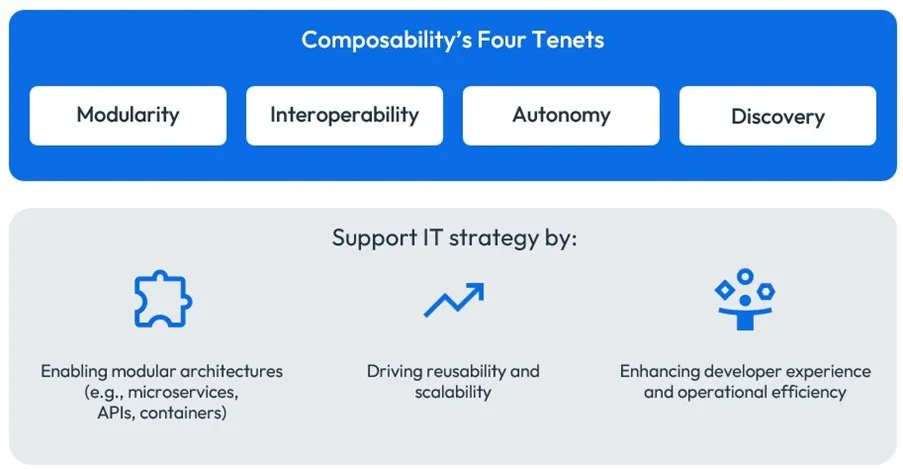
Four Pillars of Composability:
- Modularity: Every application or service is deconstructed into discrete modules, each encapsulating distinct functionality. Modularity enables abstraction, isolation and reuse, making it easier to update, replace or repurpose components as needs evolve.
- Interoperability: Components communicate effectively through well-defined interfaces, typically APIs. This ensures that modules can work together, regardless of their underlying technology or domain.
- Autonomy: Each module is designed to function independently, minimizing interdependencies. This independence is crucial for resilience — if one service fails, others remain unaffected, ensuring business continuity.
- Discovery: Modules must be discoverable so developers and systems can find, integrate and reuse them as needed. API-driven discovery frameworks facilitate this by making interfaces visible and accessible.
Composable architectures are not merely a technical strategy — they represent a paradigm shift in how organizations approach problem-solving. By decomposing business problems into refined units of work, enterprises can adapt quickly to change, reconfigure systems in response to new demands and innovate more rapidly.
Industry Status: From Mainframes to Microservices to Composability
The journey toward composable architecture mirrors the evolution of IT over the past three decades.
The era of mainframes and monoliths gave way to client-server architectures, which distributed workloads but often led to complex, tightly coupled systems.
The rise of cloud computing and microservices signaled a new wave of distributed, loosely coupled applications. These technologies enabled greater scalability and flexibility — but not without introducing new integration and observability challenges.
Today, composable architectures represent the next logical step. Modern platforms are built from modular services, exposed through APIs, and orchestrated via CI/CD pipelines and automation frameworks. Organizations strive for cloud-native solutions, yet remain wary of vendor lock-in and the need for interoperability across multiple providers (AWS, Azure, GCP, private clouds).
IT departments are at a crossroads. Many enterprises have begun the journey toward composability, but few have fully realized its potential. Most organizations operate hybrid environments, balancing legacy systems with modern cloud services. Challenges remain — especially in discovery, integration, and governance — but the momentum is unmistakable.
Building Your Future on a Composable Architecture
Several trends are set to shape the future of composable architectures:
- API-First Development: Successfully leveraging composable architecture within your business depends on clear, robust APIs that serve as contracts between modules. As organizations adopt API-first strategies, integration becomes simpler, test-driven development becomes standard, and cross-domain collaboration accelerates.
- Domain-Driven Design: Increasingly, IT teams are abstracting business knowledge into reusable assets — features, strategies, decision models — that can be shared and repurposed across the enterprise. Domain-driven abstraction allows organizations to compose solutions that directly reflect business objectives.
- Observability and Automation: As ecosystems grow in complexity, observability frameworks will need to track both system and business metrics. Automation of testing, deployment, and operations (via CI/CD) will become more sophisticated, enabling continuous integration and delivery across domains.
- Agentic Architectures: The next frontier lies in agentic systems that decompose workloads into self-contained units, capable of autonomous decision-making and problem-solving. These systems leverage business composability to orchestrate complex workflows, optimize outcomes, and respond dynamically to changing conditions.
FICO Platform: Built on a Composable Architecture
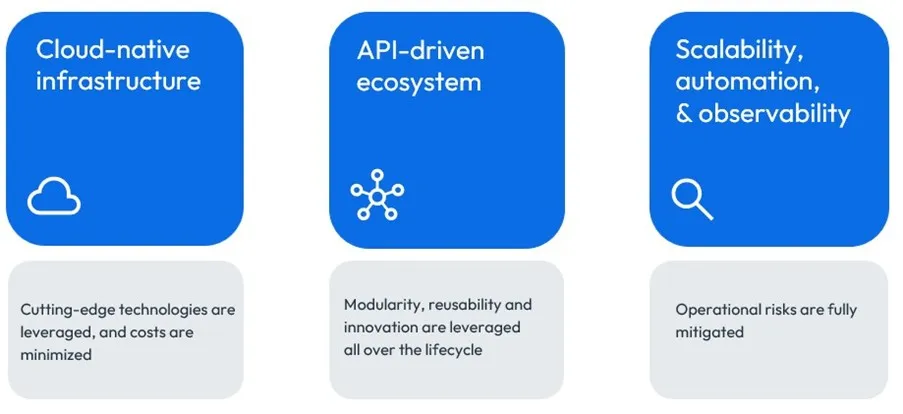
FICO, a leader in decision management and analytics, has embraced composable architecture as the foundation of our FICO Platform. Over the past three decades, FICO has refined the art of decision management by breaking processes into smaller units, abstracting business logic as reusable assets, and assembling these components to drive portfolio outcomes.
Core Principles in Practice
- Decision Management as a Composable Asset: FICO treats business logic — not just software — as an asset. By abstracting domain knowledge from runbooks and manuals into composable, reusable components, FICO empowers organizations to repurpose their knowledge across varied use cases.
- Granularity and Flexibility: FICO Platform enables users to configure composable flows, integrating services managed within FICO Platform and exposing them as modular solutions for specific business problems. These flows are domain-driven, allowing composition and communication between multiple workflows — such as retail lending sharing information with application fraud detection.
- Prepackaged Solutions and Modular Deployment: FICO’s asset-based approach allows rapid deployment of solutions, freeing users from the burden of underlying mechanisms. Existing logic and patterns can be reused, so organizations do not have to transform everything at once — they can evolve iteratively and strategically.
- CI/CD Integration: FICO Platform exposes continuous integration and deployment concepts not only to IT systems but also to business domains. Customers can continuously integrate and deploy updates in seconds, minimizing disruption and maximizing agility.
- Interoperable Ecosystems: FICO Platform supports hybrid environments, including cloud-native services, legacy systems, and customer-managed infrastructure. API-first, contract-based development ensures seamless interoperability and future-proof scalability.
Real-World Impact
Consider a major FICO customer that required seamless integration with their GitOps environment for automated deployments — a hybrid model where authoring occurred in the cloud but execution was local. FICO’s composable architecture enabled integration using Jenkins or Argo workflows, supporting both cloud and on-premise operations.
Another example is a leading video game company handling billions of daily events. By leveraging FICO Platform services authored in the cloud and integrating them with other cloud-hosted and local services within its composable business flow, the company optimized domain content reuse and operational flexibility at scale.
Key Takeaways: The Path Forward
Composable architecture is not a destination but a journey. It enables organizations to:
- Break business problems into manageable, reusable components
- Adapt quickly to disruption and changing market needs
- Integrate legacy and modern systems for maximum value
- Accelerate innovation, reduce operational risk, and ensure resilience
- Align IT strategies with business objectives through domain-driven design
By adopting approach based on a composable architecture, organizations will find themselves better equipped to navigate uncertainty, experiment boldly, and deliver personalized, impactful experiences at scale. FICO’s commitment to enabling business composability ensures its customers remain at the forefront of this evolution, leveraging the power of modularity, interoperability, autonomy, and discovery to drive lasting business value.
In the words of modern IT architects, “Design for modularity, validate through testing, and let domain-driven thinking guide every decision.” The future belongs to those who can compose, recompose, and adapt — one building block at a time.
How FICO Platform Gives You the Advantage of Composable Architecture
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.