How to Get Better Results from Your ‘Lift and Shift’ Project
Moving to a ‘Lift, Shift and Enhance’ strategy can deliver substantial growth and future-proof your operation

The typical notion of ‘Lift and Shift’ is often simply a catch-all route applied to any cloud migration. It broadly refers to moving an application and its associated data from an on-prem center to a cloud platform, while retaining the same architecture, sizing and configuration.
But the term is regularly used in a far broader way. It also often refers to moving an entire software application as it is to an upgraded or superior version - even if the move is on-prem to on-prem, or cloud to cloud. But the term gets so frequently overused it creates the perception of low-level complexity or minimal effort during implementation.
As a result, the overuse creates low expectations around business outcomes – modest enhancements to decisioning and processes, which take advantage of incremental capabilities delivered by the new system. In other words, lower levels of implementation effort justify expectations of reduced ROI – if there’s even any at all.
Why ‘Lift and Shift’ Projects Take Longer, Cost More and Deliver Less
Expectations for a ‘Lift and Shift’ software implementation project typically include:
- Design, configuration, and testing will be fast and painless - pretty much just copy and paste.
- Interfaces with both downstream and upstream systems will remain almost unaltered.
- Given the input data is exactly the same, calculations and decisions delivered by the new software will be identical to the old system.
- There will be little or no enhancement to decisioning and processes that take advantage of incremental capabilities brought in by the new system.
- Provided the above, business users - Credit Risk, Operations, Compliance - will not be materially impacted during the course of the project.
- Transition to the new system will be totally transparent for operations and customer-facing staff.
In summary, there’s a misconception that ‘Lift and Shift’ will be a picnic.
But experience tells us the preconceptions of a typical ‘Lift and Shift’ implementation are rarely met in the real world. In fact, these types of software implementation projects are far more than simply just ‘lifting and shifting’ for numerous reasons.
- Input data structure and new fields in the new system might not be exactly the same, as source systems may have been updated, revised or replaced.
- New data lakes or data warehouses already in place may be in the midst of an upgrade or replacement.
- Input and output data language might be different in the new system as the old one may be outdated.
- Internal algorithms and functions – such as scores, affordability calculations or limit allocation logic - may not return the same results as in the old system.
- Extended user skills may be required to properly run the new technologies to make the most of their capabilities.
- Further updates may be required to align the new technology with existing systems, disrupting the operating models of customer-facing and operations staff.
When this happens - and the level of implementation effort is not as low as expected - a question mark immediately hangs over the reduced expectation of ROI. Was it really worth giving up the opportunity to achieve greater enhancement in decision-making and processes at the time of system migration?
That said, there are still many organizations where a ‘Lift and Shift’ approach to software implementation makes all the sense in the world. Typically, these enterprises are already analytically and technologically advanced, with sophisticated processes and decision-making in place. It may also be there is little room for incremental automation and the potential uplift from changes in decision-making is negligible.
Moving from ‘Lift and Shift’ to ‘Lift, Shift and Enhance’
For the vast majority of organizations migrating to a new system with expanded capabilities, it is an opportunity to help kick-start the journey to greater prosperity.
At FICO, many of our clients migrating from their legacy on-prem point solutions to our cloud-based FICO Platform realize the tremendous impact the expanded capabilities can bring in significantly improving their decisioning, orchestrating, or processing outputs, and consequently their business outcomes, growth and success.
For example, 'Lift, Shift and Enhance' drove mortgage growth for one EMEA lender, thanks to 90% automation and increased approvals of US$2.8 million - all without undermining risk exposure.
In this instance, our client opted to implement FICO originations software to replace obsolete legacy technology. But during the pre-implementation assessment it quickly became clear the bank's legacy decisioning was significantly hampering mortgage approvals for good quality credit applicants.
As a result, originations strategies were adjusted following analysis from a combination of expert know-how and data-driven insights, which helped inform the most appropriate 'Lift & Shift and Enhance' route to software implementation.
The bank's results spoke for themselves. It quickly emerged mortgage decision automation rates had soared from 65% to 90% - without detriment to risk quality. Annual yields from increased approvals were estimated to be around US$2.8 million.
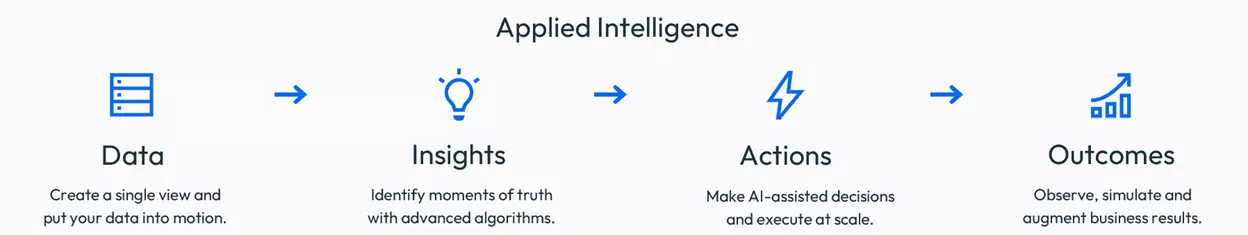
The Four Pillars of ‘Lift, Shift and Enhance’

Data
- Break down data silos and create a rich, contextualized view of your customers and organization.
- Access more data, and more data types, from both internal and external sources to produce more accurate decisions.
- Ingest alternative data from non-traditional sources to expand analytics predictive power and afford precise decisions for thin-file and no-file customers promoting financial inclusion in the process.
- Process and make the most of granular transactional data to strengthen and refine analytics capabilities to help deliver ever-more accurate affordability calculations.
- Capture data as events happen in real-time. Insights can further complement the traditional cycle-based or end-of-month batch processing models.
- Streamline and orchestrate data access to various internal and external sources, enabling stakeholders from different business areas to make appropriate and better-informed decisions where it matters.
- Future-proof the whole decisioning platform for planned expanded capabilities.

Insights
- Keep customer profiles up to date, outsmart competitors, create better customer journeys, respond faster to opportunities and build a learning culture.
- Add greater sophistication to analytics with new AI and machine learning models to draw actionable insights, strengthen customer strategies and enable smarter, faster, more profitable decisions.
- Expand analytics to more areas in the institution – be it transactional analytics, pricing elasticity, income and affordability estimation, attrition, customer lifetime value or link analysis.
- Take advantage of applied optimization models to expedite decisioning evolution and maximize return across the entire credit lifecycle.

Actions
- Combine insights from human and machine intelligence to deliver smarter decisions and hyper-personalized experiences which can maximize return-on-information.
- Make impactful actions when they matter the most, introducing real-time event-driven decisioning across all channels and throughout the entire customer lifecycle.
- Take advantage of superior technology and innovation to enhance decisions. Many bad decisions may simply be a result of poor technological capabilities.
- Rationalize logic and move from a rule-driven to an analytic-driven approach for increased decision automation and precision.
- Evaluate the full customer experience and lifecycle to provide consistent decisions and communications aligned across business areas and credit lifecycle stages.
- Create an omnichannel framework to enable every individual transaction – be it a credit application, insurance offer, customer service claim or any other across the different areas of the business - to move seamlessly across digital self-service as well as more ‘traditional channels’ to enhance customer experience and meet customer preferences.

Outcomes

- Ensure strategies consistently maximize their return by keeping a profound analytical understanding of data, decisions, actions, and their outcomes through upgraded reporting capabilities.
- Institutionalize test and learn champion-challenger methodology to drive a program of continual strategy evolution within a controlled learning environment.
- Take advantage of expanded outcome simulation capabilities to investigate the expected impact of changes within complex analytical decisioning solutions before deploying them into production. Stress-test predictive models alone or complete decision strategies against changing market conditions or changes in the models themselves.
- Create an enhanced reporting framework to provide the appropriate level of detail for all the various stakeholders within the enterprise, to clearly understand how the business is performing against the established targets so, if necessary, appropriate corrective or pre-emptive measures can be promptly adopted at any time.
- Set up a robust governance framework on your operating model around process, people, and systems.
If your organization is one of the few already enjoying these features and capabilities, congratulations! You are in a privileged position and likely to dominate your market for the next few years.
But if it’s still deemed to be far, far away from a decisioning paradise, or want to move to a new decisioning platform with augmented capabilities to be a resounding success – arguably the only option – is to embrace a ‘Lift, Shift and Enhance’ approach.
At FICO, we are here to support throughout the process, making any migration as painless as possible to supporting in making the most of the advanced capabilities to ensure better business outcomes.
How FICO Can Help Your Digital Transformation Succeed
- Explore innovation with FICO Platform
- Watch the video “FICO® Platform: Applied Intelligence, when and where it matters”
- Read the whitepaper “FICO® Enterprise Intelligence Network: Redefining the next generation of applied intelligence”
- See customers discuss their use of FICO Platform
- Read the article from The Journal of Digital Banking, “How Financial Services Leaders Are Using Enterprise Intelligence to Optimize Efficiency Ratios”
- Read the blog Three Ways to Justify Digital Transformation Investment to the C-Suite
- Making Digital Transformation Pay Off
- Watch FICO Platform in action with the story of your everyday consumer, Digital Jane

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.