360 Degrees Isn’t Enough to Chart Your Digital Transformation Journey
Having customer information from all angles is essential for digital transformation, but only if you can connect the insights coming at you from all directions

In selling situations, software vendors love to promise prospects “a full 360-degree view” of all their customer data. It’s a popular, throwaway marketing line; almost a cliché, leaving the impression that their product gives you a view of the customers from every possible vantage point: just like a compass.
What vendors often don’t tell you is that their “platform” is often a combination of products that sit beside one another – like the four 90-degree angles between north, east, south, and west that add up to 360 degrees – without ever touching one another.
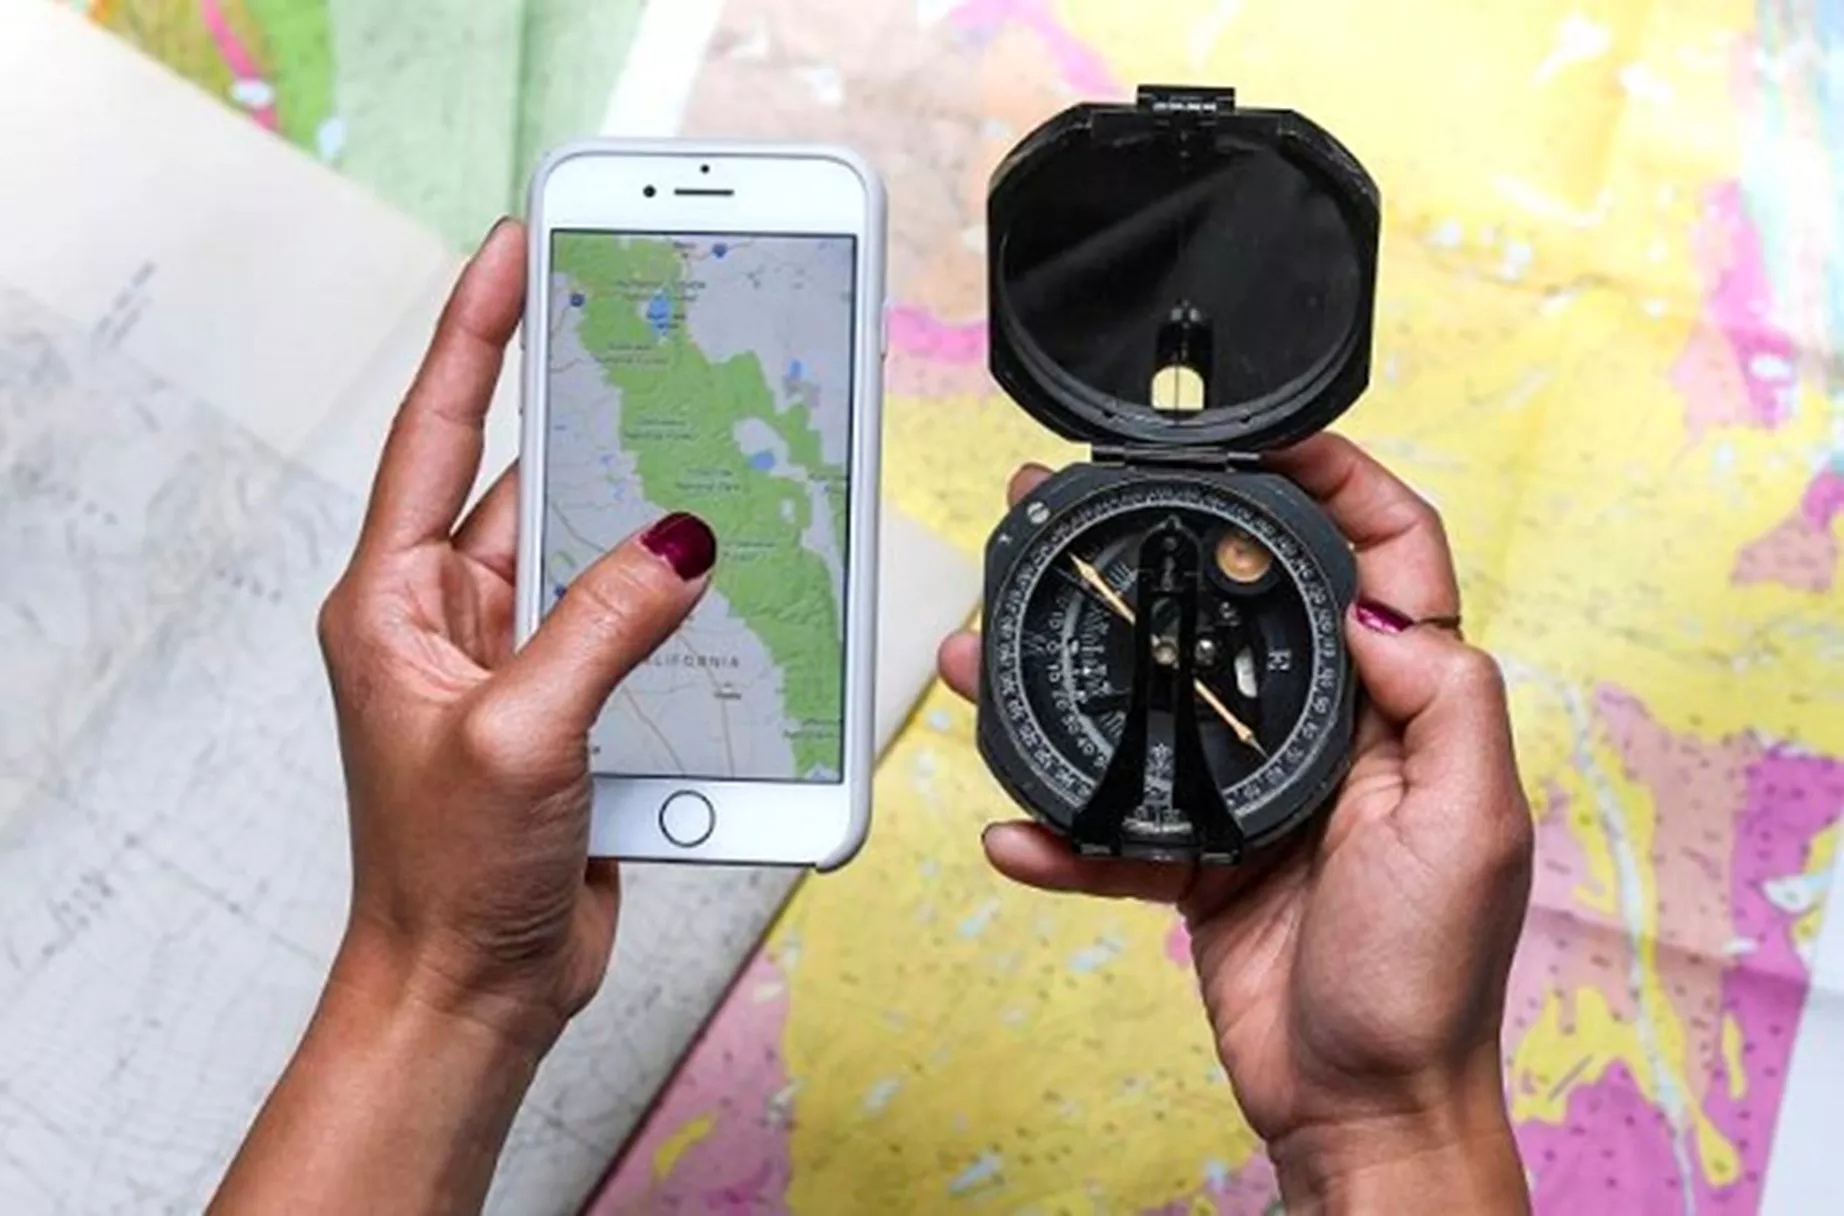
A compass can be a handy thing to have for recreational hiking. But even a 360-degree field of view has its limits: what you really need is up-down-all-around omnidirectional vision to spot changing developments from every direction. That’s why for a really long or really important journey I’d much rather have a GPS or the navigation app in my smart phone: assuming that I had an always-on mobile connection, it offers more robust information, pinpoints my exact location, tells me precisely how much progress I’ve made towards my destination, and alerts me to potential problems and opportunities around the bend.
Centralized decisioning is the digital decisioning equivalent of a GPS. It’s the new upper-right-hand-corner of competitive offerings, where the highest levels of decisioning sophistication and business value meet. Like comparing a compass to a GPS, a comparison between traditional software applications – or even previous-generation decisioning systems – to centralized decisioning isn’t a fair fight. Here’s why:
1) A compass stays fixated on just one data point
A compass tells you just one thing: direction. It cannot tell you where you are in terms of your destination, how fast you are traveling towards it, or when you will get there… only that it’s somewhere in that direction. (Of course, doesn’t even point to the same “north” as the one on your map; it points to magnetic north, which can be 400-1000km from true north.) The same holds true with software applications designed as point solutions; unless they can be made to operate synergistically as part of a larger platform, they can only provide a very limited view of the customer… certainly not enough for decisioning.
Why GPS/Centralized Decisioning is better: A GPS is an intelligent, geospatial GIS-driven digital map, that includes finely-detailed, always-updated information on your starting point, destination, route, speed, and ETA over time. It moves with you and captures changes in your surroundings in real-time. In the same vein, Centralized Decisioning delivers omnidirectional real-time insights and suggested actions in response to (or anticipation of) changes in a customer’s situation or macro-market developments. To your customer, it offers and immersive, high-personalized, and contextually responsive user experience.
2) A compass operates as though the world is flat
A compass works in 2D, so it offers virtually no useful information about topography. It is blind to natural obstructions like mountains, chasms, and other natural obstructions that could impede your journey; and it cannot alert you to more 3D threats above or below… whether something potentially annoying like birds sitting overhead, or something truly dangerous like quicksand three paces ahead. Similarly, many software standalone applications have a very limited field of view because they operate in siloed systems designed to support a single function or department; they cannot aggregate their insights to provide a broader customer view.
Why GPS/Centralized Decisioning is better: Just as GPS unifies all types of digital information – from roadmaps, GIS systems, elevation studies, real-time traffic reports, etc. – Centralized Decisioning unifies all siloed application data from across and from all levels within the enterprise… detailed information needed to provide an immersive, IMAX-like view of the customer and plan a personalized customer journey over their full lifecycle. This unlimited visibility enables a 3D view of the customer and makes hyper-personalized customer experiences possible… which, in turn, increases satisfaction and retention.
3) A compass has no concept of time
If you throw your compass in your backpack, and then your backpack in a closet, the needle will continue to point towards magnetic north. So, barring a geomagnetic reversal (there have only been 183 reversals over the last 83 million years, roughly or every ~450,000 years) it will remain pointing north until your next trip, oblivious to the time that has passed. The same is true of data in applications that aren’t continually refreshed and cross-pollinated with newer, fresher information: the data gets stale, outdated, and eventually unusable.
Why GPS/Centralized Decisioning is better: Your GPS or navigation system is continually pinging for updates, revising what it knows, filling in what it doesn’t, and refreshing what it is presenting to the user. Data remains current in real-time, allowing the user to instantaneously make smarter decisions to arrive at their destination faster and more safely. Centralized decisioning operates exactly the same way: any changes in a customer’s profile, behavior, or analytically-predicted needs automatically updates their master record, and proposes revised, personalized customer strategies. Again, this serves to boost customer satisfaction and retention.
4) A compass can lead you in the wrong direction
Navigating over long distances via compass – especially in the air or over water – can be a hit-or-miss proposition: for every degree that a plane or boat veers off its course, it misses its target destination by about one mile for every 60 miles travelled. So, if you set a compass heading from Los Angeles to Cadiz, Spain and were only off by one degree, you’d end up in Africa… in Tangier, Morocco, to be precise. Software applications, when used in decisioning, can have the same effect: one errant piece of data that goes undetected can throw off the entire customer journey off course.
Why GPS/Centralized Decisioning is better: Making decisions based on imperfect data will, over time, cause your customer strategies to veer off course just enough to cause you to miss the bullseye. Just as a GPS continually verifies its position and heading to keep you on course, Centralized Decisioning persistently updates and validates data to ensure that customer strategies are followed and course corrections are made to ensure the optimal customer journey.
5) A compass is prone to bias and external influence
Because it relies on magnetism, a compass is susceptible to magnetic interference from metal objects – wrist watches, keys, mobile telephones, etc. – as well as natural electromagnetic anomalies. So much so that the updated World Magnetic Model – produced by National Geospatial-Intelligence Agency, the National Oceanic and Atmospheric Administration and the British Geological Survey – has added “Black-Out Zones”(BoZ) where compasses aren’t at all reliable. Decisioning systems cobbled together using siloed applications can also yield unwanted influence on the direction of your customer strategies, when one data set is more complete than the others, there are inconsistencies/conflicts in the underlying information, or critical information from key applications is left out of the decision.
Why GPS/Centralized Decisioning is better: People have driven their cars into oncoming traffic, onto wrong-way highways, and even into lakes following their GPS. In the decisioning world, intentionally or not, data can be sliced, diced, skewed, mishandled, manipulated, and omitted in all sorts of ways to produce spurious results. Centralized decisioning takes a multitude of precautions to ensure that decisions are made on the best possible data available and is continually working to validate data before it can contaminate the decisioning process. This ensures that customer strategies are based in the accurate, verifiable information necessary to ensure optimal business outcomes.
Over the past few years, FICO has been helping leading corporations across the globe reach their digital transformations successfully and we have emerged has an industry-recognized leader in digital decisioning platforms. We are uniquely qualified to advise companies on how to accelerate their transformation efforts in a people/process/technology-friendly manner, with minimal disruption to their existing operations.
For more information on the FICO Centralized Decision solution, please visit www.fico.com/CentralizedDecisioning For educational material on digital transformation and digital disruption, please visit www.fico.com/DTeducation For information on digital transformation in the financial services industry, including detailed research and reports from Arizent and American Banker, please visit www.fico.com/ABresearch
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.