NFTs and Money Laundering - Are Fraudsters Becoming Artists?
As non-fungible tokens fetch millions of dollars in auctions, it raises questions about the connection between NFTs and AML

In part 1 of this blog series my colleague defined NFTs or Non-Fungible Tokens. Now, I’m going to cover what it means for the wider financial crime space.
It is well known that dealing in art can be a vehicle for money laundering and terrorist finance. We saw this in the Panama Papers as well as the FinCEN files.
I think NFTs are even better for illicit purposes than traditional art, simply because the hurdles are lower. Art presents itself in many different ways, but to overly simplify I categorize it in two ways:
- Often the art in question is historical in nature (for example, paintings or antiques). They are physical objects, even if on occasion their provenance can be shady and their authenticity difficult to prove.
- Contemporary art, presented in a traditional, physical format may appear different in its subjects, forms and interpretation. However, as with older artworks, the identities of the artists are generally established. While some artists like Banksy remain anonymous to the public, it is not proving difficult to assign an artwork to them and I would argue that certain parties such as government agencies could work out who is behind the identity if they haven’t already.
When we move to the world of digital art and NFTs, the provenance and authorship of the works of art are obscure to say the least and they don’t fit into the categories I outline above. And yet they are exchanging hands for huge sums, making them a great vehicle for money launderers. So, how do criminals go about using NFTs to launder money?
Four steps to using NFTs for money laundering:
- Create the artwork. A single grey pixel sold for ~$1.4 million. The grey box at the top of the linked article is not a picture failing to load – it’s the artwork! Meanwhile these low-pixel 24x24 images of ‘punky-looking guys and girls’ (CryptoPunks) are according to their creators the first NFTs. They are generated algorithmically and they’re selling for millions of dollars – even though there’s no human artist involved in creating them beyond programming the algorithms. At the risk of sounding disdainful about these purported works of art, fraudsters can create similar works by programming the required algorithms without too much trouble (are they even fraudsters in this scenario, or actually artists?).
- Create the artist. Identity fraud is easier than ever thanks to the digital world we are living in. Fraudsters can steal identities, or artificially create them. It takes a little work, but with more and more services being digital, it’s not that hard to fake an identity, and to give it a life on Facebook, Instagram or with a few well-placed credit applications even in ‘real life’. Fraudsters can create months and years’ worth of identities that are completely made up. By using bots to create digital art and ascribing them to a fake identity that hides behind a nickname, you can achieve nearly peak anonymity.
- Create a web presence, using servers in jurisdictions that do not cooperate with international policing efforts.
- Trade your digital artwork (aka NFTs) using crypto currencies.
These four steps may seem a hypothetical scenario, but it is relatively simple and a tempting proposition for anyone looking to launder money. With art that is purely digital and can be created anywhere, there is no need for shipping, and nobody needs to put their hands on it. We have artists that might only be active via digital channels and thus have a purely digital identity. If there is nothing to show physically, you have even less reason to be anywhere in person. Such art is primarily traded on digital platforms using crypto currency, making tracking and controlling the trade and the vast sums of money behind it even more opaque.
When you examine the payments for the art pieces, you end up looking at crypto companies. Given how fast this market moves, I would argue that a lot of these crypto-finance companies have very little focus on KYC and AML, let alone any meaningful awareness of what they need to do. Coincidentally, around the time of writing this blog post, the FATF released a review of the virtual assets market. Their assessment of common issues in AML compliance amongst virtual asset service providers (see page 19/20 of the report) is damning.
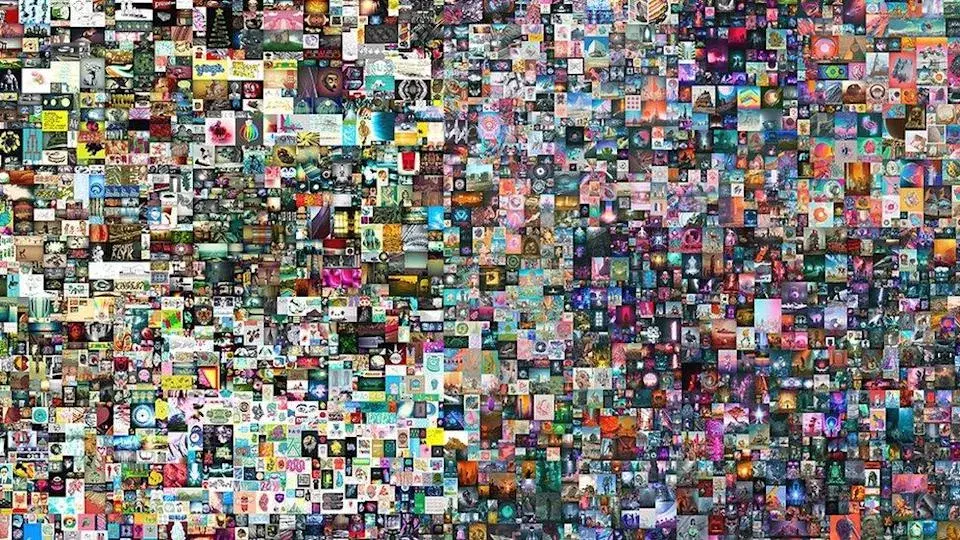
In recent times there has been a push by regulators to ensure that auction houses thoroughly vet the identity of their customers and that crypto companies are properly regulated. It remains to be seen what effect this will have, but it could be too little, too late, and in the wrong place. ‘Everydays: the first 5000 Days’ has been sold via Christie’s. That grey pixel has been sold via Sotheby’s. But the CryptoPunks I previously referred to are still for sale via various channels. In 2020, the total value of CryptoPunks sold was about ETH208k (that’s Ethereum, a crypto currency), or $414 million.
This is a fast-paced market meeting a slow-moving regulatory environment. Will it give fraudsters and money launderers a low-risk, high-profit heyday?
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.