Real-Time Payments: 4 Requirements for Scam Protection Systems
How to design a multi-CSM (clearing and settlement mechanism) RTP solution for maximum fraud and scam protection

This is a post co-authored by Alexandre Graff with Krishanu De, senior director, head of Payments, Risk & Compliance at Cognizant, and Manan Gauba, head of Strategy and Partnerships, BFS at Cognizant.
The growth in real-time payments has been well-documented globally, but rising in parallel are scams and fraud. To stop this “scamdemic”, financial institutions must evolve their systems to enable the huge growth potential of RTP while increasing consumer protection from scammers. In this post, we’ll discuss some essential considerations for designing such an RTP system, especially one that works with multiple Clearing and Settlement Mechanisms (CSMs).
First, it’s worth summarizing the huge growth in the RTP space. RTP systems are expected to grow at a CAGR of 21.3% between 2022 and 2027. More than 70 countries have already adopted RTP in some fashion. A recent FICO survey shows that consumer adoption is keeping pace:
- 90% of more than 14,000 consumers from 14 different countries polled have used RTP
- 38% use RTP more than five times per month
- 88% plan to maintain or increase use of RTP in the coming year
A global wave of scams has shadowed RTP’s rapid adoption, resulting in more consumers suffering significant losses.
- Financial crime and fraud are projected to cost banks and financial institutions $40.6B globally by 2027.
- In 2022, 20% of all consumers worldwide were victims of payment fraud, of which ~27% was Authorized Push Payment (APP) fraud, the most common form of fraud related to RTPs
- APP fraud losses are expected to climb to $6.8B by 2026 at a CAGR of 11% (2022-27) across six major RTP markets (US, UK, India, Brazil, Australia, and Saudi Arabia).
Changes in Clearing and Settlement Mechanisms
We have also seen the introduction of new RTP CSMs, such as FedNow, which the US Federal Reserve launched last year to replace The Clearing House. Indeed, some markets now have multiple CSMs.
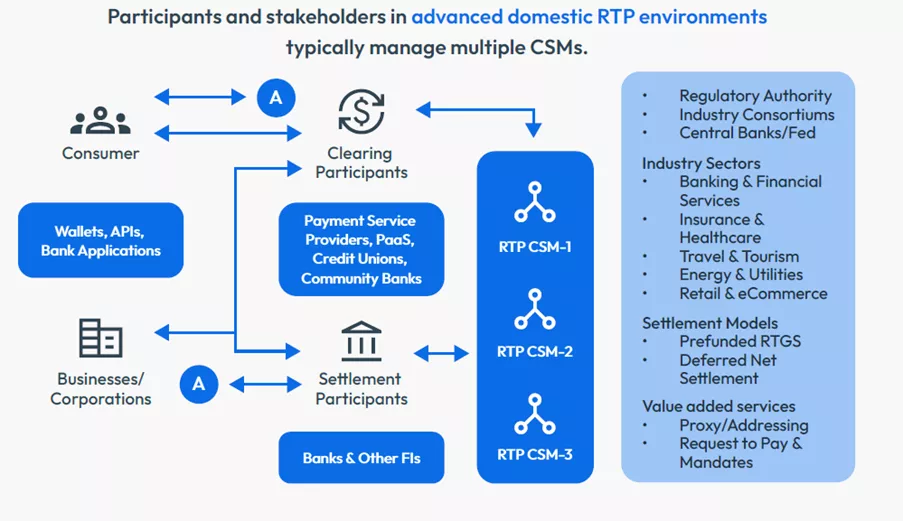
Banks operating in RTP ecosystems with multiple CSMs typically have the option to integrate with more than one. While this means additional complexity and cost it also gives banks the ability to transact with more counterparties, which invariably attracts a larger customer base.
Many financial institutions have begun enabling instant cross-border payments. For example, BIS Nexus is connecting Europe’s TIPS with ASEAN-5. Elsewhere, Singapore and Indonesia have a cross-border QR code-based payment already in place. These regional networks bring additional opportunities for banks and PSPs to capture an international client base.
Fraud Risk Grows with Multiple CSMs
A fraud-resilient integrated solution approach is required for creating instant payment hubs or enabling RTP rails that process domestic RTGS, ACH, or SWIFT transactions. The nature of real-time payments poses additional challenges for fraud systems, demanding more powerful fraud prevention safeguards that stop scams before they take place.
How can fraud be detected even before the payment hits the payment hub? Network and counter-party collaboration is the key — sharing the data characteristics of fraudulent transactions through the Payment Market Infrastructure service is essential for combating counter-party fraud and will provide better protection for consumers. Additional AI/ML-based suppression layers of protection against sophisticated threats would help detect and block RTP fraud with granular precision, reducing losses and improving approval rates. Detection of network decoding traffic and deploying firewalls to block suspicious transactions are some techniques for managing fraud early in the lifecycle.
How to Design a Multi-CSM RTP Solution for Maximum Fraud and Scam Protection
1. Build in advanced scam detection techniques
Standard fraud prevention models and techniques are failing to detect RTP scams, for multiple reasons. The small size of most RTP transactions means its easier for fraudulent transactions to slip under the radar. Criminals often launder the stolen money through multiple account “hops,” making tracking and recovery harder. There are also fewer “red flags” with RTP fraud, as it’s generally the legitimate customer making the transaction.
This is why customized machine learning models are needed, which can identify multiple features required to confirm the identity and intentions of the sender. These models use new techniques, such as specialized behavior sorted lists (B-lists), which can determine the probability that the debit party is the authentic originator of the payment. B-lists also monitor key attributes of the originator’s payment history and learn what constitutes normal behavior for an originator, which means these models can detect anomalies that may be signs of a scam.
2. Create Payment Command Centers guided by customized rule sets
The major challenge for banks and PSPs is to act instantly after detecting a scam, given that intervention must take place in real time. First, the right interdiction support must be baked into the payment flow for all RTP CSMs. Classifying detected fraudulent transactions against a predefined and agreed upon taxonomy for each participating RTP network is difficult for any risk scoring engine. Thus, it’s crucial for PMIs to separate authorized transactions from push-payments in order to apply the appropriate rule set. In fact, not only does the entire process of interdiction and regulatory reporting and compliance depend upon the classification rules defined by the PMIs for the CSMs and participating banks and PSPs, but those rules usually evolve over time. Therefore, any fraud detection and command action software needs to be easily customizable in order to support rule updates.
Setting up a separate RTP command center that can employ automated responses based on the appropriate (and easily updatable) scenario-driven rule sets should be a critical consideration for banks and PSPs that process a large volume of RTP transactions.
3. Stakeholder collaboration strengthens data modeling
Stakeholders should share their enhanced data and intelligence, as well as collaborate in order to reduce fraud more effectively. Solution design can also foster collaboration by allowing easy API access to third-party providers, making data source modification easier. Integration with credit bureaus is crucial for sourcing individual and corporate credit history, eligibility scores, credit types, interest rates, and more. Access to PMI data—including fraudulent transaction history, watch lists, compliance metadata, and settlement reports for both domestic and cross-border transactions—is also of utmost importance. Finally, several third-party firms and organizations can source know-your-customer (KYC) information, aggregated transaction data, channel data, financial information data, and ratings. Banks and PSPs should always seek out ways to make their intelligence more comprehensive, and they should be supported by a solution that facilitates connectivity to these data sources.
4. Leverage both internal and RTP network data and controls
Instant PMIs such as FedNow provide certain capabilities for preventing fraud through various transaction limits (network- and participant-level) and through participant-defined negative lists. Typically, network-level limits are defined by the PMI, whereas participant-level limits are set by banks and PSPs. Participating banks and PSPs need to fully leverage these capabilities to fight RTP fraud. In terms of internal tooling, transactional fraud models have been very effective in fighting account takeovers, CNP fraud, etc.
However, RTP transaction fraud requires more sophisticated tools to detect scams that fall in a more ambiguous area that will often look like authentic transactions. The best approach to tackling this problem is a consortium-based model that detects anomalies in the consumer’s behavior and fed by the data sources we’ve discussed.
Additional Design Considerations
- Manage all RTP transactions through an RTP hub.
- Adopt ISO 20022 as the internal message formatting of the RTP hub — this will be the most common format.
- Ensure you have configurable and scalable translation and orchestration. This allows legacy systems to coexist with the new messaging standard and aids in gradual transition from a fragmented ecosystem to a standardized target architecture.
- Employ a sound framework for selecting your solution. Prioritize considerations such as the supporting RTP CSMs, geographical coverage and NFR requirements.
- Develop a detailed data transition plan and prepare for contingencies. The process of data mapping from existing channels to a new RTP CSM transaction processing hub can lead to data truncation and other snags. Test rigorously during the transition and be ready to troubleshoot.
- Take an iterative approach to your RTP transformation. You will want to roll out your RTP hub in phases, especially if you’re participating in multiple CSMs. This is primarily to ensure you maintain interoperability with your back-end systems and third-party services.
Learn More About RTP and Fraud Prevention
- Read the white paper from FICO and Cognizant, “A Perspective on Fraud: Resilient Real-Time Payment Hubs with Multiple Clearings.”
- Explore the findings of FICO’s recent global scams survey
- Explore the partnership between FICO and Cognizant
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.