FICO Platform Drives R$1B Digital Rural Credit in Brazil
Bradesco delivers agriculture finance solutions to 500,000+ farmers via E-agro, Brazil’s first fully digital rural credit platform, powered by FICO® Platform

Creating New Agriculture Finance Solutions
Bradesco, one of Latin America’s largest banks, is using FICO® Platform to revolutionize how rural credit is delivered in Brazil. Through the E-agro digital platform, built and run on FICO’s advanced decisioning capabilities, the bank has automated complex processes, improved credit access for over 500,000 farmers, and delivered over R$1 billion in funding within the first year.
Brazilian agribusiness plays a key role in the global food supply, with some estimates suggesting it helps feed around 10% of the world’s population. Bradesco’s investment in E-agro is not only a leap forward in financial technology but also a catalyst for economic and environmental resilience across rural Brazil.
“Farmers play a very important role in Brazil’s economy, and technology is key to supporting their growth,” said Nadege Saad head of agribusiness at E-agro. “With FICO, we’ve built a digital offering that makes credit more accessible, approvals faster, and sustainable practices more viable. This is more than a financial innovation, it’s also a social and environmental one. By linking better credit access to sustainable practices, we’re not only protecting natural resources — we’re improving livelihoods and strengthening rural communities.”
Digitizing Credit. Empowering Farmers. Enabling Sustainability.
Bradesco launched the E-agro marketplace in 2023 to simplify access to rural credit, products, and services. Built on FICO Platform, the solution automates credit evaluation, document verification, and disbursement — removing friction from the lending process and eliminating the need for in-person visits. Small and medium-sized farmers can now apply, qualify, and receive credit entirely online, at the exact moment they need it.
Since launch, the platform has:
Granted over R$1B (USD$197M) in credit with over R$500M in marketplace transactions
Reduced contract lead times by 70%
Completed 2,000+ complex credit transactions using FICO-powered decisioning
Delivered Brazil’s first fully digital, government-subsidized rural credit solution
A Digital Platform Built for the Field
Traditionally, rural producers needed to visit branches, notaries, and multiple institutions to access credit, a time-consuming process incompatible with modern farming. With E-agro and FICO Platform, Bradesco has digitized the entire journey. Farmers can now check credit eligibility in real-time, receive tailored offers based on behavioral and agronomic data, submit socio-environmental documentation online, and digitally sign contracts, all from their mobile device or desktop. Once approved, funds are disbursed immediately into the client’s account, eliminating the need for any physical visits.
By integrating FICO Platform into the credit lifecycle, Bradesco reduced steps from dozens to just eight, making the process not only faster but fairer and more inclusive.
Driving ESG Impact Across Brazil
Beyond the E-agro offering, Bradesco’s ESG commitment extends to playing a supporting role in the ILPF (Integrated Crop-Livestock-Forestry) Network, a regenerative agriculture model that enhances biodiversity, improves soil quality, and reduces greenhouse gas emissions. Through partnerships like the Sustainable Agriculture Finance Facility (SAFF), Bradesco provides lower-cost credit for farmers adopting ILPF practices.
Bradesco is bringing new thinking and technology to banking in agribusiness. By using advanced decisioning to empower farmers and protect the environment, they’re creating lasting economic and ecological value.
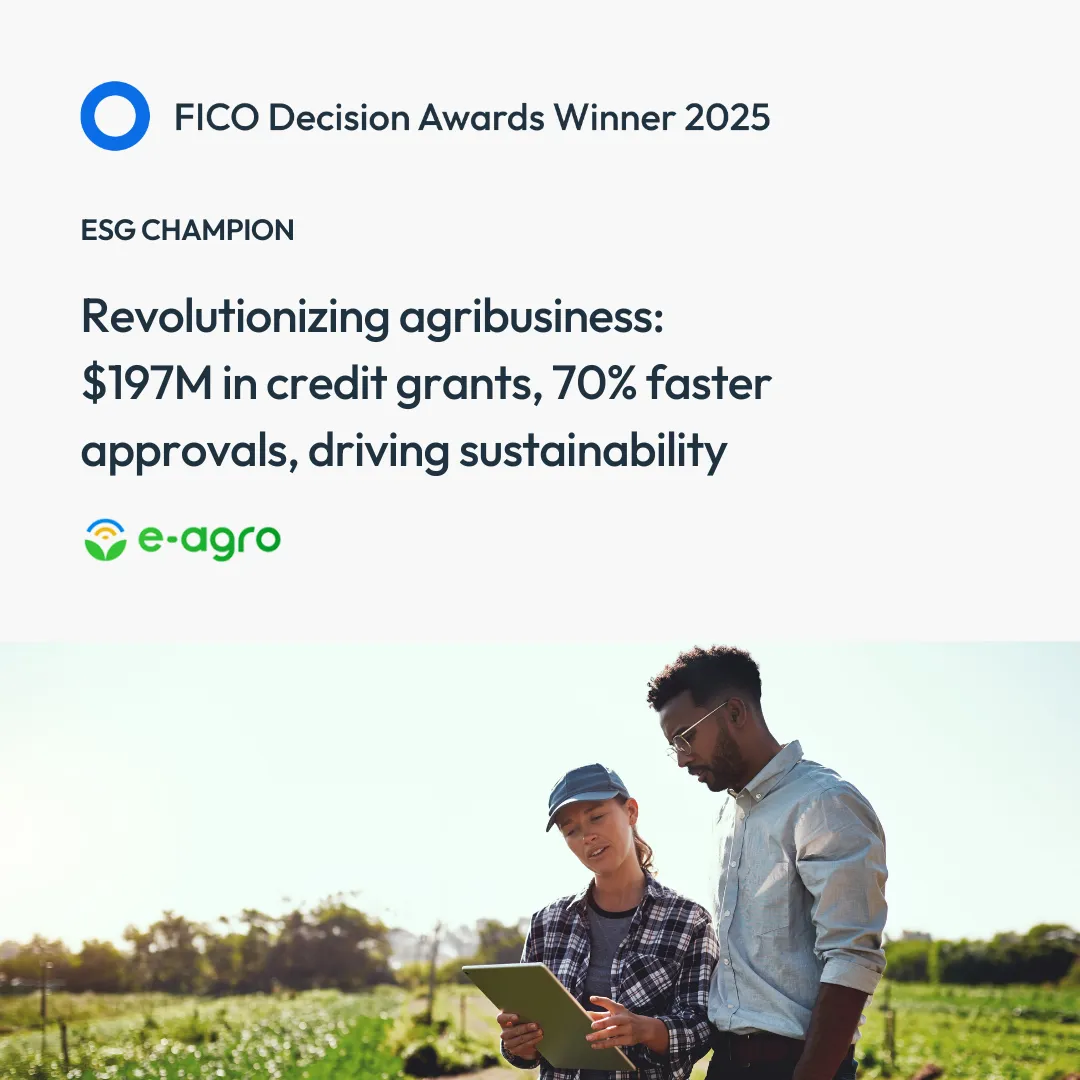
For its achievements, Bradesco’s E-agro has won the ESG Champion category in the 2025 FICO® Decision Awards.
“Bradesco’s E-agro platform stood out to the judging panel as a powerful example of how digital innovation and environmental responsibility can go hand in hand,” said Allan Tan, group editor-in-chief at Cxociety and FICO Decision Awards judge. “It’s rare to see such a clear fusion of ESG commitment with operational transformation.”
To see the full list of 2025 FICO Decision Awards winners, check out: https://www.fico.com/en/fico-decisions-awards-2025
How FICO Support Ag Finance With Smarter Loan Decisions
Discover how FICO helps banks design tailored lending solutions that meet the unique needs of farmers, ranchers, and agricultural cooperatives—improving access to both short- and long-term farm loans, even in the face of challenges like climate change and natural disasters.
Learn more about Digital Onboarding and Loan Originations. Explore how lenders can digitally onboard agricultural borrowers with speed and precision using automated decisioning, reducing friction while improving risk assessment and regulatory compliance.
- Explore how FICO Platform powers smarter lending. With FICO Platform, institutions can build scalable Agricultural Financing solutions that adapt to changing conditions, support inclusive growth, and deliver sustainable credit access to rural communities.
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.