The Impact of Regulation on Collections and Customer Care
This FICO World presentation highlights the vital importance of balancing customer care with collections success in a highly regulated environment

At FICO World, Tathiana Paredes and I underscored the critical importance of balancing customer care with collections success in an increasingly regulated environment. Our session explored how, in today’s uncertain economic climate, collections departments face mounting challenges — from rising customer arrears to the increasing struggle individuals face in managing the cost of living.
The Regulatory Challenge Collections Operations Face
To remain effective, collections operations must adapt to growing volumes while ensuring fair and ethical treatment of customers. This balance is often shaped by regulatory pressures, which increasingly influence collections practices worldwide.
Our presentation highlighted the importance of understanding the regulatory landscape and its implications for collections teams. It emphasized the need for preparedness — not only to manage higher workloads, but also to support customers with compassion and flexibility. Regulatory frameworks frequently mandate such treatment, requiring that customers be viewed as individuals with unique financial circumstances.
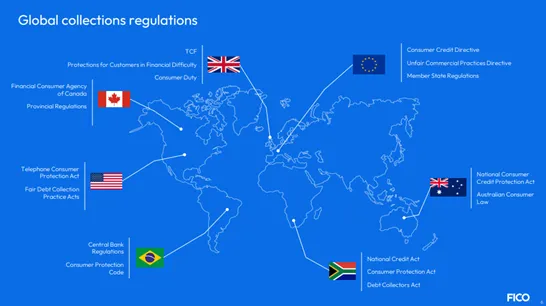
A key regulatory focus is the protection of vulnerable customers. Laws like the Fair Debt Collection Practices Act (FDCPA) in the U.S. the Debt Collectors Act in South Africa and the Protection for Customers in Financial Difficultly Consumer Duty in the UK, establish standards that limit excessive contact, prohibit harassment, and emphasize respectful communication. These requirements compel collectors to take a more supportive and ethical approach, transforming collections into financial assistance for those in hardship.
I illustrated this with a case study from a debt charity. Alan, a fictional example, experienced financial strain after losing work and relying on credit cards to cover basic needs. His situation improved when his mortgage provider took time to understand his challenges and referred him to a debt counsellor. This holistic, compliant approach—motivated by regulation—enabled Alan to keep up with priority debts and repay other creditors sustainably.
Global regulations share common themes: Avoidance of unfair treatment, flexibility in approach, and support to help customers return to financial stability. Whenever possible, the goal should be to help customers move out of arrears and onto manageable, long-term repayment paths.
Poor collections practices carry a risk of material regulatory fines and customer redress, which are on a different scale to the cost of implementing the necessary changes. However, the benefits extend beyond regulatory compliance, as more supportive, personalised collections approaches are also proven to provide transformative collections performance impacts.
How FICO Platform Powers Effective and Compliant Collections
FICO Platform is a powerful enabler of effective, customer-centric collections strategies that meet both performance goals and regulatory requirements. It enhances communication, supports compliance, and drives improved outcomes through a combination of advanced analytics, omni-channel engagement, and AI-driven automation.
Omni-Channel Engagement for Customer-Centric Outreach
FICO Platform’s Omni-Channel Engagement capability, allows collections teams to connect with customers across their preferred communication channels—whether via email, SMS, phone calls, or digital apps. This flexibility fosters more meaningful interactions, builds trust, and increases the likelihood of positive repayment outcomes by reaching customers in the ways they’re most comfortable with.
Data-Driven Communications for Better Timing and Tone
FICO Platform uses advanced analytics to inform the timing, frequency, and content of customer communications. By delivering the right message at the right time, collections teams can improve engagement and response rates. The platform also supports compliance by ensuring that outreach remains within regulatory limits and aligns with individual customer preferences—helping organizations avoid over-contact and maintain a respectful tone.
Conversational AI for Scalable, Personalized Service
FICO Platform’s conversational AI capabilities enable dynamic, interactive self-service experiences. This is particularly valuable for digital-native consumers who prefer to manage financial matters through automated, on-demand solutions. Conversational AI improves customer satisfaction while also increasing operational efficiency—boosting self-service adoption and lowering the cost of collections.
Tathiana provided a real-world example from a financial institution in Latin America that emphasized the importance of modernizing collections systems, without jeopardizing customer trust. This compassionate approach increased amounts collected by 37% while reducing cost per promise by up to 75%. Adaptation to modern tools and data-driven strategies also led to 80% of the delinquent portfolio being served in digital channels. In turn, this increase in self-service adoption, delivered faster account collection with a 50% decrease in days to collect and halved the cost to collect.
Conclusion
The regulatory environment surrounding collections is increasingly complex, requiring organizations to strike a careful balance between performance and customer care. FICO Platform plays a critical role in achieving this balance by equipping collections teams with the tools they need to stay compliant, engage customers effectively, and improve outcomes. As regulations evolve, leveraging technology like FICO Platform will be essential for adapting quickly and maintaining ethical, compliant collections practices.
Learn How FICO Can Help You Improve Collections and Meet Regulatory Requirements

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.