India's Digital Scam Epidemic: A Threat to its Financial Resilience
As digital transactions soar, Indian banks face a rising tide of scams. Learn how to stay ahead with smarter fraud prevention strategies.

The Dark Side of Digital India: How Scammers Are Exploiting Online Payments
Online payments are becoming the backbone of India's financial system as the country transitions to a digital-first economy. From villages to Delhi - 'Digital India' has reshaped how citizens interact with money. However, this transformation has also brought to light a growing vulnerability: a surge in digital scams that threaten to undermine the very progress it has fostered.
Scams, particularly an Authorized Push Payment (APP) scam, occur when victims are tricked into willingly transferring rupees – with tactics that range from fake investments and legal notices to emotional manipulation. Scams are very different from traditional fraud that involves unauthorized access to bank accounts or identity theft. With the explosion in transactions via Unified Payments Interface (UPI), Real-Time Gross Settlement (RTGS), and Immediate Payment Service (IMPS), there is a staggering increase in these scams.
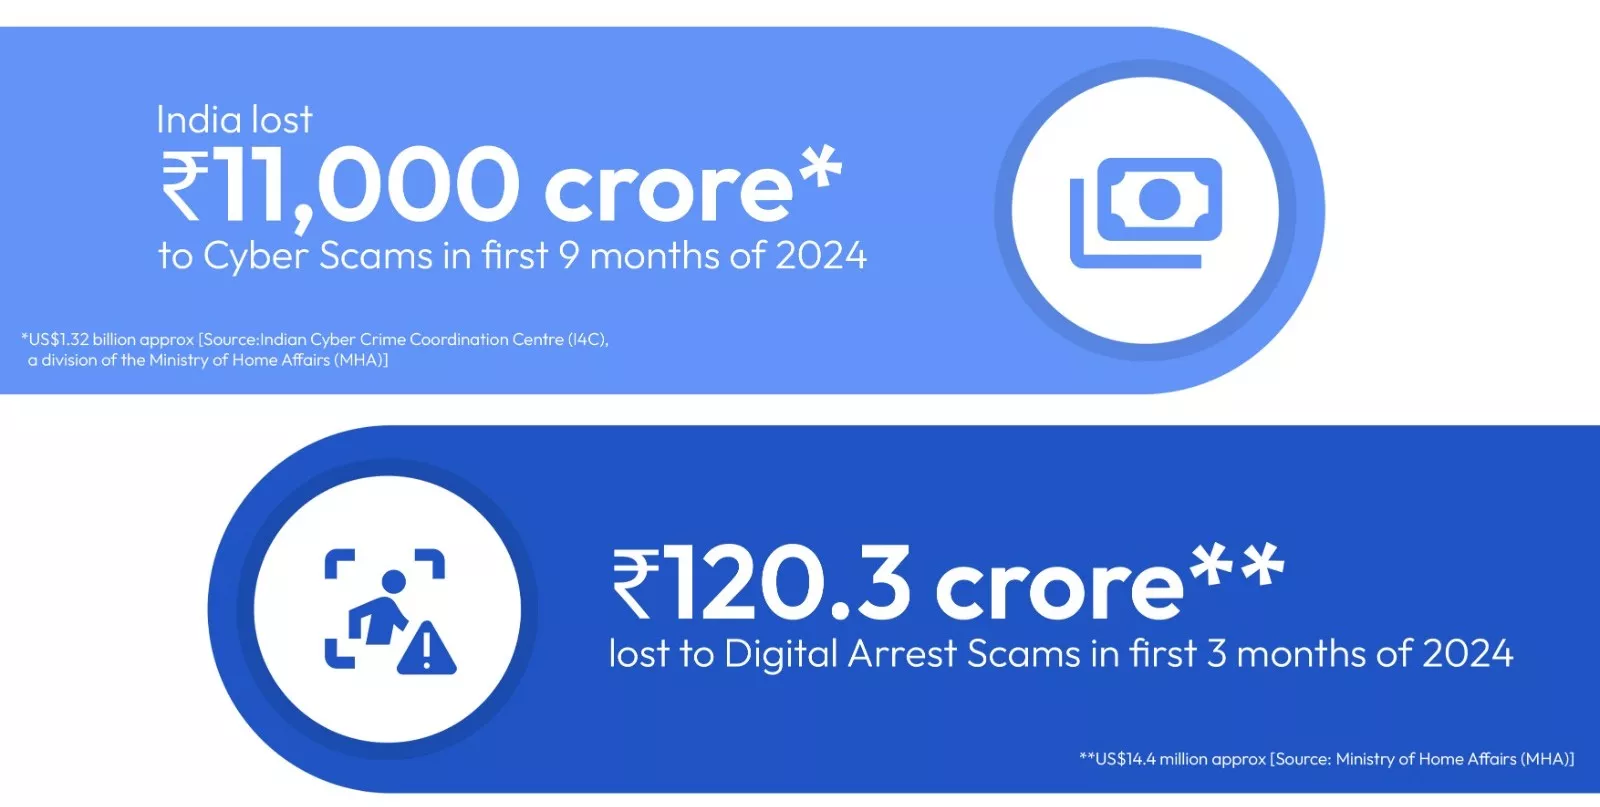
Reports indicate that, in the first nine months of 2024, India lost around ₹11,000 crore (US$1.32 billion approx) to cyber scams, but a more surprising number is that ₹120.3 crore (US$14.4 million approx) was lost to ‘digital arrest’ scams within the first three months of the same year. Digital arrest scams, which are relatively new and may be unfamiliar to many people, happen when scammers impersonate law enforcement officers and intimidate victims to transfer money to avoid legal trouble. In one instance which isn’t an isolated incident, a woman from Bengaluru was tricked into transferring ₹30 lakh (US$36,000) to scammers posing as government officials. Beyond this, romance scams, fake investment schemes, and parcel scams are also becoming common, each taking a toll on unsuspecting victims.
The Escalating Threat of Scams in India Fueled by Real Time Payments (RTP)
UPI transactions alone jumped by 52% last year, showing just how much people are reliant on real-time payments (RTP). Scammers target the growing volume and speed of RTP transactions while also adapting their approach to carry out their schemes. The impact of these scams is concerning, not only from a financial standpoint, but also from a social perspective – left unchecked, this could hurt consumer trust, as observed in other countries where digital payments are rapidly evolving.
This threat extends far beyond individuals - impacting banks and financial institutions that are at the heart of this digital economy. Globally, banks and regulators are tightening security and operations; but as the honeypot of opportunities moves to scams, the traditional, reactive approach is no longer enough. We need a proactive strategy that anticipates threats and actively prevents them.
Legal and Financial Burden on Consumers and Banks Responsibility
Digital scams are also creating a growing legal and financial strain for both consumers and banks. While victims suffer financial losses, banks face the dual risks of financial impact and reputational damage, with recovery rates often remaining shockingly low.
In India, the compensation for scam victims, especially in cases involving APP scams, is determined based on specific circumstances, and banks are not legally required to make restitution as would be the case in other countries. Take the UK, for instance, where the Payment Systems Regulator mandated both the sending and receiving banks to compensate customers who fall prey to scams, up to £85,000.
Governments and regulators are also stepping up – In India, the Reserve Bank of India (RBI) has recently introduced AI-powered initiatives designed to protect the banking system from scams, alongside strengthened cybercrime cells and public awareness campaigns for customers. Its 14C guidelines also mandates banks and financial institutions to develop and deploy better detection algorithms and provide proactive education to their customers through alerts, app notifications, and warning messages, as an added measure.
As FICO’s 2024 Scams Impact Report highlights, 45% of Indian consumers believe that better detection systems would be the most effective way to combat scams. And it doesn't stop there; they can also play a role in educating customers on emerging threats – which is where FICO comes in.
FICO: Role of Intelligent Detection Systems
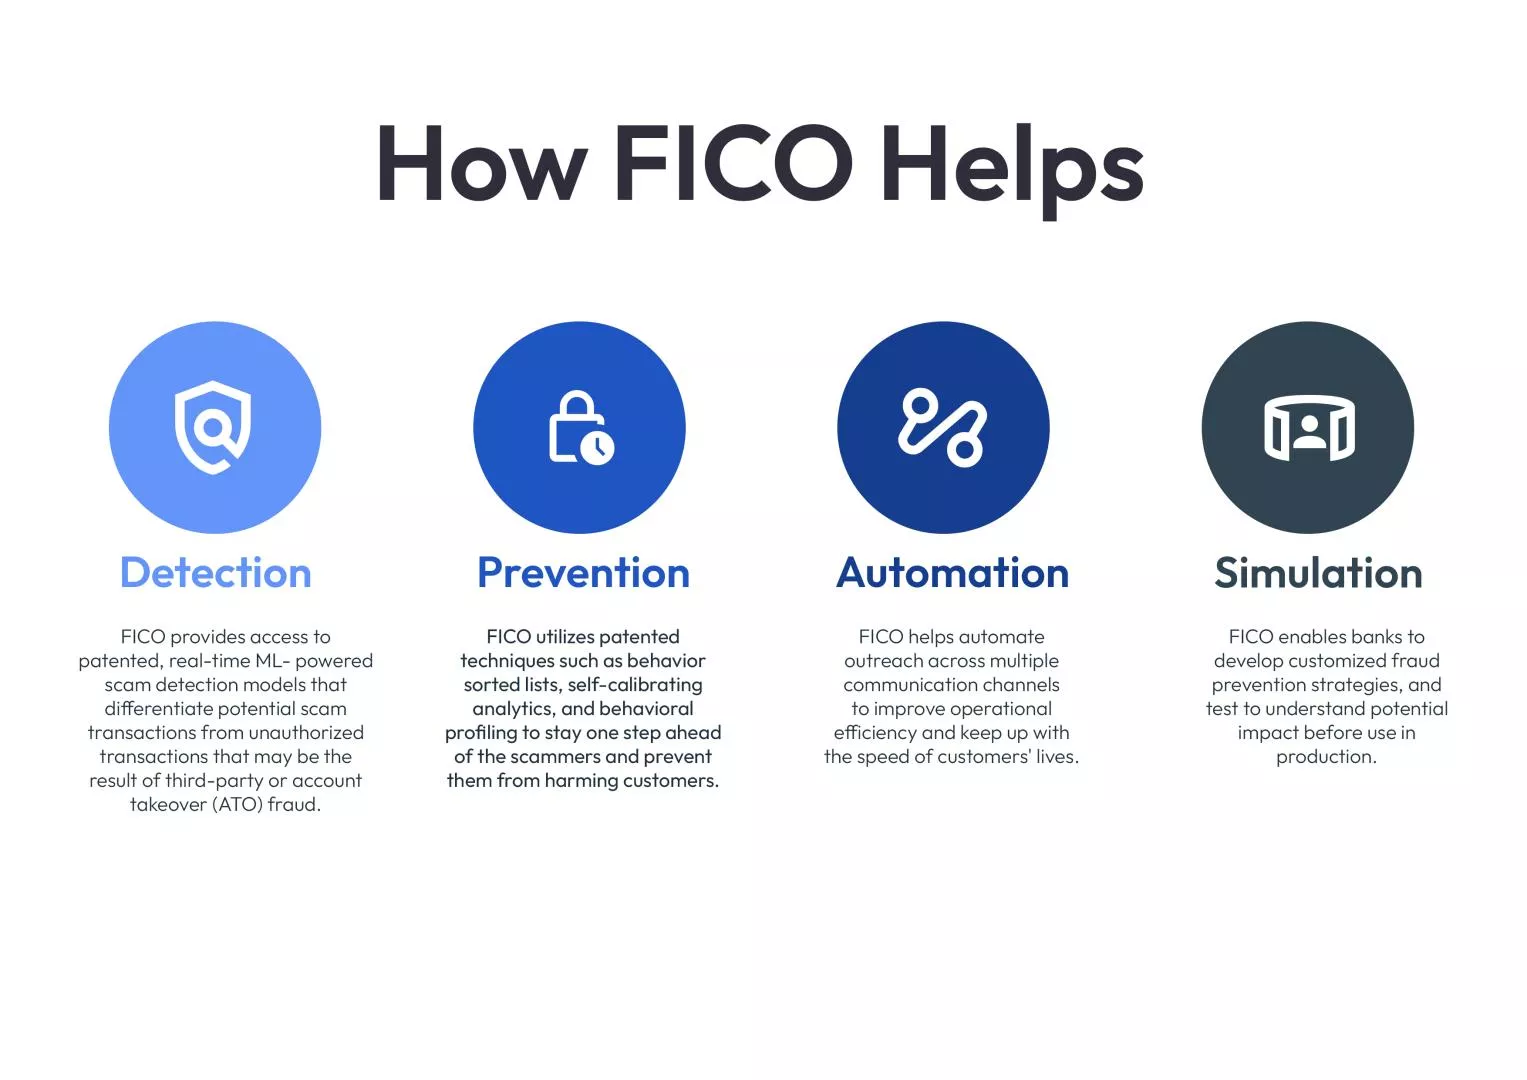
For more than 30 years, FICO has delivered fraud solutions that detect and prevent fraud and financial crime across the customer's life cycle. By leveraging AI-driven insights and real-time monitoring, FICO’s technology can deliver insights in milliseconds—faster than the blink of an eye—while processing thousands of fraud detection calculations per transaction.
The company’s advanced scam detection technology can help banks differentiate between unauthorized transactions, authorized transactions and authorized push payments that may be associated with fraud, distinguishing between genuine transactions and those made under likely duress or deception. FICO’s machine learning-powered fraud detection model has been shown to detect up to 50% more scam transactions over a traditional third-party fraud score, with a low review rate of just 0.5%.
The speed and precision significantly enhance banks’ ability to prevent scams before they can impact customers. This has earned FICO multiple accolades, including the 2022 Machine Learning in Credit and Collections Award and the 2024 Silver Medal for best scam and APP fraud innovation from the analyst firm Datos Insights for its Scam Signal, developed in conjunction with Jersey Telecom, reaffirming the impact and reliability of its fraud prevention capabilities.
FICO’s fraud technology protects more than 4 Billion payment cards globally and in Asia Pacific while working with many of the most significant banks across the region. The company’s partnership with Bank Mandiri in Indonesia helped safeguard over 1.64 billion transactions valued at US$156 billion and reduce fraud losses by 85% in eight months. Indian banks including Axis Bank and ICICI Bank, have also long relied on FICO’s fraud prevention technology to protect customers. Axis Bank, for instance, has been using FICO’s Falcon fraud detection system since 2013, enabling it to identify potential fraud in real-time and take appropriate action. ICICI Bank, another early adopter, has seen similar success using the same AI-powered solutions.
No Silver Bullet for APP fraud and Scams
Authorized push payment fraud is complex and multifaceted, affecting individuals, businesses, and banks alike. While no solution is flawless, a multi-layered and collective approach - where every stakeholder plays their part, will be key to reducing losses. Education, the right tools, and effective policy enforcement will be essential.
Consumers and businesses must be educated and aware, banks must use the tools available to them and the industry and regulators must continue to drive effective policy and where necessary regulation.
As scams become more sophisticated, the urgency for this collective effort has never been greater. The road ahead is challenging, but with a concerted effort, the tide of scams can be turned.
Take Action Against Scams
- Learn how FICO’s solutions can help you stay ahead of scams.
Get in touch for actionable strategies – email dattukompella@fico.com.
Find Out How FICO Can Help You Better Manage Scams
1. Discover Key Insights – Read the FICO 2024 Scams Impact Survey: India
2. Stay Ahead of Global Trends – Explore the FICO 2024 Global Scams Impact Survey
3. Read our blog on stopping scams in real time, Survey: Real-time Intervention Is Key to Scam Protection
4. Explore insights on Real-Time Payments: 4 Requirements for Scam Protection Systems
5. Read our post on, From Detection to Prevention – Tackling Scams from Every Angle

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.