Survey: What Makes a Great Customer Experience?
A new FICO survey on customer experience found that 9 in 10 people globally believe that customer experience is as important as a bank’s products

Today’s customers expect exceptional experiences no matter the industry. They aren’t just comparing one bank to another or one channel to the next – they are measuring you against the best experience they’ve had anywhere.
Customer experience (CX) impacts how customers feel during every interaction with your bank throughout their entire journey. From calling the contact center or transferring money via mobile app to routine bill paying, each touchpoint shapes their perception of you and influences their decision to remain loyal.
A recent FICO survey found that 91% of people globally believe that customer experience is as important as a bank’s products and services. Furthermore, nearly a third of those people (28% of respondents) say that customer experience is actually more important.
Why Customer Experience Is So Important in Retail Banking
Great customer experience is critical for success in the increasingly competitive and commoditized financial services industry. CX is your biggest differentiator because it drives acquisition and retention, builds loyalty, boosts revenue and lifetime value, and sets your brand apart.
There are many reasons why banks’ customer experience is important, including:
- Retention and Loyalty: Happy customers stay longer
- Acquisition and Referrals: Great CX turns customers into advocates
- Revenue Growth: Satisfied clients buy more products and services
- Competitive Edge: Customer experience sets banks apart in a crowded market
- Trust and Reputation: Positive experiences build confidence in the brand
- Lower Churn: Good CX prevents costly customer loss
- Deeper Engagement: Strong CX drives use of high-value services
FICO’s survey also revealed that bad customer experience is the #1 reason people will leave their bank. 47% of customers globally say they would leave their bank provider because of bad CX. In fact, bad customer experience ranks higher than data security concerns (43%), a fraud event (40%), and poor value for money (39%).
Bad customer experience will make people leave, but good CX is only part of what attracts new customers. 34% of customers globally say they would switch to a different bank if the new provider has better customer experience. Leading factors that would make customers switch their bank provider include better value for money (47%) and incentives (35%).
How Do Consumers Rate Their Bank’s Customer Experience?
Bank customers expect a variety of services and features to enhance their experiences, including easy-to-use apps, personalized offers, and tailored interactions that seamlessly cross all channels. Many banks have evolved their CX quickly in recent years in response to competition and rising consumer demands.
Our survey found that 87% of consumers worldwide rate their main banking provider’s customer experience as either ‘Generally good’ (61%) or ‘Excellent’ (26%). Conversely, 13% consider their bank’s customer experience to be mediocre or worse. This is somewhat positive news for banks, but it is not the end of the road.
Customer experience is a moving target that requires continuous improvement to stay ahead of the competition. With over 90% of consumers weighing customer experience so heavily, we will see CX play an increasingly decisive role in winning new customers and retaining existing ones.
What Makes a Great Bank Customer Experience?
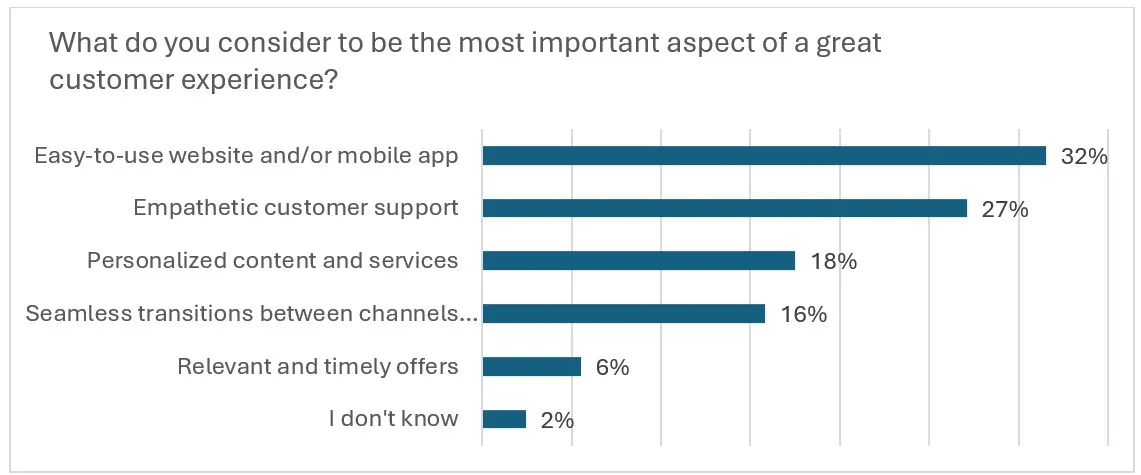
According to FICO’s global bank customer survey, the most important aspects of great CX are an easy-to-use website and/or mobile app (32%), empathetic customer support (27%), and personalized services (18%).
Here are 5 factors that matter most to customers and can help banks improve their CX:
Ease of use
Nearly one-third of consumers (32%) worldwide say that easy-to-use websites and mobile apps matter most in delivering a great customer experience. As banks layer on new technology and services, “ease of use” now goes far beyond clean layouts and well-placed buttons.
Customers expect seamless, integrated communication (e.g., private chat, text, email, secure voice) plus intelligent tools that help them quickly find what they need and continue where they left off. Automated notifications, natural language assistants, and guided or automated navigation are no longer extras, they’re becoming the baseline for a modern banking experience.
Empathy
More than a quarter of customers (27%) say empathy is the most important aspect of a great customer experience. Customers want to be cared about. They expect their bank to approach and respond with informed, personalized interactions based on intelligent insights. For example, a customer struggling with a payment should be guided to resolution, not pushed an upsell. Meanwhile, a customer victimized by fraud deserves swift support and assurance in resolving the problem. Remember that technology can deliver efficiency, but the human touch remains vital.
Personalization
According to FICO’s survey, 18% of consumers think that personalized content and services are crucial for great customer experience. Additionally, 73% of people say that personalization makes them more likely to do business with a financial institution. A personalized customer experience involves tailored interactions – delivering the right message to the right customer at the right time and through their preferred channel. In order to achieve personalization, banks must have a deep understanding of their customers’ behaviors and preferences.
Seamlessness
A seamless, positive customer experience fosters trust, reduces churn, inspires referrals, and strengthens both brand reputation and profitability. Customers are frustrated by repetitive processes that keep asking for the same information or being unable to easily transition from one channel to the another (e.g., from a bank’s mobile app to its website). Omni-channel engagement, transactional monitoring, and intelligent fraud resolution are examples of capabilities that contribute to a seamless customer experience.
Relevant and timely offers
It’s important for financial institutions to understand their customers’ behaviors, cater to their preferences, and anticipate their needs. That means banks must harness real-time data, advanced analytics, and intelligent decisioning at scale so they can determine the next best action or experience for each customer.
How FICO Can Help You Improve the Customer Experience and Loyalty
- Explore FICO solutions for customer management
- Read How to Unlock the Power of Hyper-Personalization in Banking
- Review the e-books on our customer survey:

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.