A Guide to Customer Intelligence and Why It's Critical for Revenue Growth
Customer intelligence transforms raw, disconnected customer data into structured, actionable insights that inform smarter business strategies

The ability to truly understand customers and adapt to their needs is an essential component of sustained revenue growth. That's where customer intelligence comes in. It plays a foundational role by transforming raw, disconnected customer data into structured, actionable insights that inform smarter business strategies so companies can deliver better customer experiences that foster loyalty and lifetime value.
What Is Customer Intelligence?
Customer intelligence is the process of collecting and analyzing data about customer behaviors, interactions and preferences across various channels to inform strategic business decisions. This involves the integration of diverse data sources, such as transaction histories, website interactions, social media activity, and customer feedback, to build a comprehensive view of each customer.
Most importantly, customer intelligence is not limited to surface-level data aggregation, it incorporates advanced analytics, artificial intelligence, and machine learning to uncover patterns and predict future customer behavior.
The Different Types of Customer Intelligence Analytics
Actionable customer intelligence leads to a comprehensive understanding of customers, built from data collected through core enterprise systems, CRM platforms, surveys, digital engagement analytics, and complementary third-party data sources. Each type of customer data point offers unique insights that drive business value.
- Behavioral Analytics: Behavioral intelligence focuses on tracking and analyzing how customers interact with a company’s products, services, and communication channels by tracking website clicks, app usage, social media engagement, and customer support interactions. These signals can not only be used for detecting revenue generation opportunities, but can also be used for fraud mitigation.
- Demographic Analytics: Demographic intelligence centers on collecting data such as age, gender, location, company size, and industry, to define who the customer is and support personalized customer engagement strategies.
- Psychographic Analytics: Psychographic intelligence is a broader analytics category that includes attitudinal analytics, but covers deeper psychological traits like values, interests, lifestyle, personality, and motivations (often summarized as AIOs: Activities, Interests, Opinions) to provide context for why customers make a particular purchasing decision.
- Transactional Analytics: Transactional intelligence tracks information such as purchase history data, including products purchased, purchase frequency, average transaction value, and payment methods used to predict future buying patterns. It can also play a critical role in identifying potential fraud: for example, if a purchase deviates too much for the usual buying pattern it can signal a potential fraudulent transaction.
Collecting and analyzing those distinct types of customer intelligence is necessary to create a holistic understanding of the customer journey and a strategy that will lead to improved customer experience and increased revenue. These same sources of data are critical for functions such as risk management and fraud prevention. FICO Platform combines every type of customer intelligence analytics to deliver always-on customer intelligence that evolves with every interaction.
Best Practices to Get the Most Value Out of Customer Intelligence Analytics
To extract the maximum value from customer intelligence, there are some best practices companies should follow:
- Break data silos and integrate data from multiple sources to provide a unified and comprehensive view of each customer. This is the goal of FICO® Platform, which provides customer intelligence across silos and equips organizations with a shared, single customer profile. The customer profiles in our platform update continuously with data from across every part of the business, combining historical context with real-time signals to expose behavior patterns, preferences, intent, and emerging needs.
- Maintain rigorous data hygiene by regularly auditing, cleaning, and enriching records to eliminate inaccuracies, reduce duplication, and fill informational gaps.
- Leverage advanced AI, analytics, and end-to-end decisioning capabilities to surface hidden customer patterns and proactively predict future behaviors.
- Deploy robust privacy and consent management protocols to ensure regulatory compliance and build customer trust in how their information is handled.
- Break down silos between marketing, customer experience, product, risk, fraud and analytics teams to ensure that the insights gained from the customer data analysis are actionable and aligned with broader business objectives.
- Institutionalize an active feedback loop, monitoring the performance of customer intelligence initiatives and iterating based on results, industry trends, and evolving technologies to drive ongoing revenue growth and profitability.
The Benefits of Customer Intelligence
Customer intelligence delivers numerous benefits that are crucial for companies looking to drive measurable ROI and achieve competitive differentiation.
- Identifying at-risk accounts: Customer profiling analytics can help you identify customers who have been inactive for some time, have reported issues with your product, or have a high frequency of emails to customer service, so you can flag potential at-risk accounts and proactively reach out to them.
- Providing a hyper-personalized customer experience: Customer intelligence can help businesses tailor their communication preferences, such as emails or check-ins, to individual preferences. They can also use that data to understand which product will resonate best with which customers, and adjust their marketing outreach accordingly.
- Improving customer experience and retention: Customer intelligence allows companies to identify their customer pain points. Behavioral analytics will give valuable insights on the customer journey on the website and attitudinal analytics will provide more information about how valuable the product is to the customer. Put together, this data will help improve customer experience and customer retention.
- Increasing sales: Putting effort into understanding customers leads to better conversion rates, increased sales, and a higher return on investment (ROI) on marketing and customer insights investments.
Thanks to customer intelligence and analytics tools like FICO Platform, businesses can gain a comprehensive, data-driven understanding of their customers’ behaviors, preferences and needs. Armed with these new insights, they can deliver better customer experiences through personalization, increased automation, and improved agility. They can also improve their speed to market through faster strategy deployment and autonomous feedback loops, and cut costs thanks to reduced operational strain. As a result, companies can tailor marketing strategies and optimize customer journeys for higher conversion rates and stronger customer loyalty, and sustainable growth.
Using Customer Intelligence for Revenue Growth
Customer Analytics for Revenue Growth
To maximize revenue growth with customer intelligence, it's important to identify and monitor key analytics metrics that provide actionable insights into customer behavior, engagement, and profitability such as:
- Customer lifetime value (CLV): quantifies the total revenue a business can expect from a single customer account throughout their relationship
- Cohort analysis: allows businesses to segment customers based on shared characteristics or timeframes to analyze behavioral trends and create personalized retention strategies
- Credit risk: identifies the likelihood that a borrower will make their payments on time as agreed
- Net Promoter Score (NPS) and Customer Satisfaction Score (CSAT): provide direct feedback on customer sentiment, offering early signals for at-risk accounts and areas needing improvement
- Engagement data: including website visit frequency, product usage patterns, and response to targeted campaigns to enable the continuous refinement of marketing strategies and customer experiences
Applying Customer Intelligence Data to Revenue Growth
Applying customer analytic data to revenue growth requires organizations to move beyond data collection and focus on finding actionable insights to directly influence strategic priorities.
To drive revenue growth, companies need to analyze customer data to understand the drivers behind purchasing decisions and identify high-value customer segments. Once they have a better understanding of the "why" and "who", companies can create targeted, personalized campaigns that resonate with those high-value audiences to improve engagement and conversion rates.
Another important part of revenue growth is adjusting offers based on evolving customer needs. This can be done by analyzing past behavioral and purchasing data and incorporating predictive analytics.
When organizations connect customer intelligence to their marketing and operations, they can quickly spot market changes, adjust their approach fast, strengthen their customer relationships, and drive steady revenue growth.
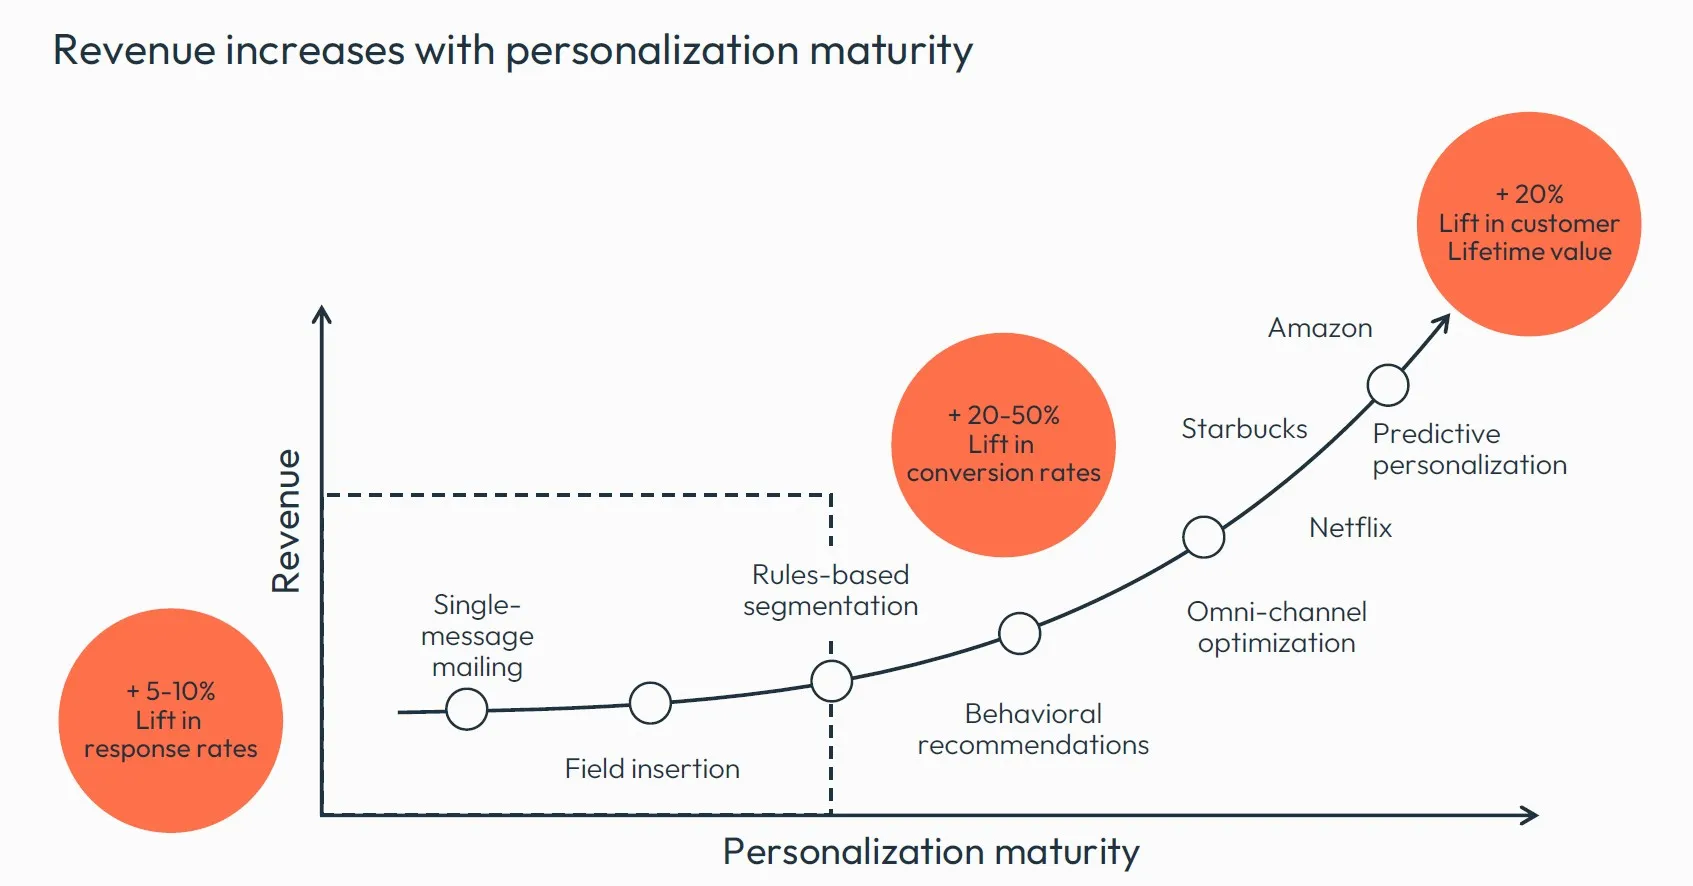
How FICO Platform Uses Customer Intelligence to Enable Customer Insights and Revenue Growth
Powered by 70 years’ innovation and pioneering work in predictive analytics, machine learning, and artificial intelligence, FICO® Platform provides a complete, end-to-end set of composable capabilities that empower you to uniquely address a vast spectrum of use cases across the customer lifecycle.
FICO Platform provides customer intelligence across silos and equips organizations with a shared, single customer profile that updates continuously with data from across every part of the business, combining historical context with real-time signals to expose behavior patterns, preferences, intent, and emerging needs.
FICO's customer intelligence capabilities enables you to analyze your data with confidence and achieve a competitive advantage, while speeding up the time to market.
To learn more about FICO's customer intelligence capabilities:
- Download the FICO world presentation to understand FICO Platform’s rich capabilities across the Applied Intelligence value chain
- Download the 2026 Gartner report to see why FICO was named a leader in the decision intelligence category
- Learn more about the FICO® Platform solution
- Get the free FICO world presentation and learn how to turn customer data into a major competitive advantage
Frequently Asked Questions
Transactional intelligence plays a key role here. By tracking patterns like purchase history, frequency, and average transaction value, businesses can establish a baseline for normal customer behavior. When a transaction deviates significantly from that pattern, it can serve as an early signal of potential fraud — making customer intelligence a valuable tool not just for revenue growth, but for risk management as well.
Disconnected systems and data silos are more difficult to analyze and prevent a single, holistic view of customer behavior. They hinder organizations’ ability to deliver consistent, relevant customer experiences across touchpoints and channels and can cause misalignment between teams.
No, customer intelligence can benefit the entire organization. While marketing teams benefit greatly from the personalization and targeting capabilities customer intelligence enables, the insights are equally valuable across product, customer experience, risk, fraud, and analytics teams. The most effective implementations are those where customer intelligence is treated as a shared organizational asset rather than a function owned by any single department.

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.