How FICO Optimization Could Help Keep Hospitals Running During Blackouts
Award-winning paper demonstrates the power of mathematical optimization and FICO Xpress to deliver sustainable, resilient energy solutions, solving an urgent need in South Africa

Since its launch in 2022, the FICO Xpress Best Paper Award has celebrated outstanding contributions to mathematical optimization, operations research (OR), and related disciplines. The 2025 competition again featured many excellent submissions, making the task of the award committee anything but easy.
This year’s award goes to:
Jusse Hirwa, Alexander Zolan, William Becker, Tülay Flamand, and Alexandra Newman for their paper "Optimizing design and dispatch of a resilient renewable energy microgrid for a South African hospital". Applied Energy 348 (2023).
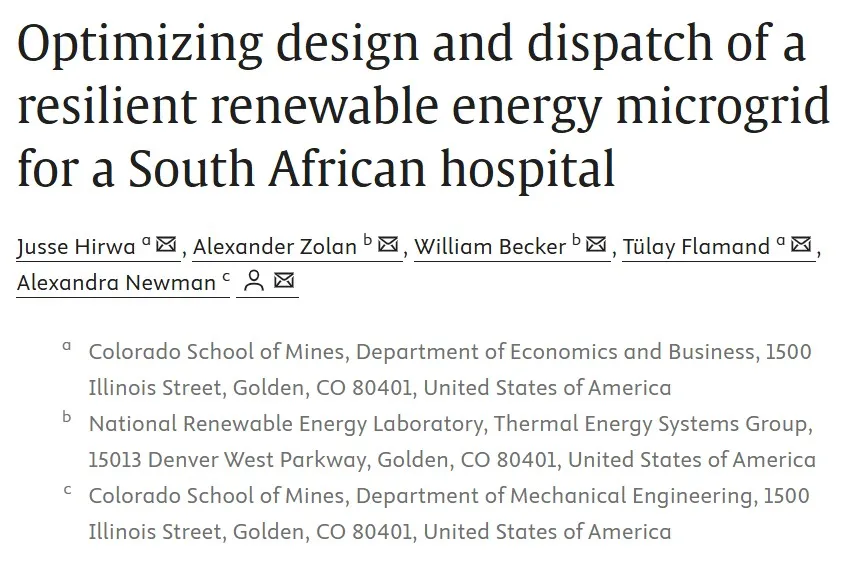
The committee highlighted the paper’s originality and its inspiring example of “using OR for social good.” The authors show remarkable dedication in addressing a highly complex, real-world challenge — guiding the reader step by step through system design, optimization modeling, and dispatch strategies.
In this blog post, we dive deeper into their work and show how their approach demonstrates the power of mathematical optimization to deliver sustainable, resilient energy solutions, using FICO Xpress.
What Optimization Problem Was the Team Trying to Solve?
Access to reliable electricity remains a major challenge across sub-Saharan Africa. A significant portion of the population either lacks access altogether or receives electricity, but while experiencing frequent outages. Many households without electricity still rely on hazardous fuels for lighting and cooking, which poses serious health and safety risks and reduces productivity, particularly among children and women, who are often responsible for household routines.
Even among communities connected to the national grid, power supply remains inconsistent. Frequent, sudden outages disrupt daily life and economic activity. Industrial and commercial sectors suffer significant losses. As the paper notes, "In 2018, 78% of firms in sub-Saharan Africa experienced power outages, compared to 46% of those in East Asia and the Pacific, 32% of those in Europe and Central Asia, and 59% of those in Latin America and the Caribbean. Additionally, manufacturing firms in sub-Saharan Africa experienced outages averaging 50 h per month, the highest of any region in the world."
Improving the reliability of electricity in sub-Saharan Africa is essential, as businesses play a central role in job creation and are critical to the region’s economic stability. In addition, hospitals require continuous power to maintain medical equipment, conduct surgeries, and store temperature-sensitive medications.
In response to unreliable grids, backup systems, typically diesel generators, designed using a rule-of-thumb, are widely used. While these generators serve as a short-term fix, they are often oversized, inefficient, costly to operate, and do not represent a long-term power solution.
How Was Optimization Used to Address the Problem of Unreliable Electric Grids?
The winning optimization paper focuses on reliability, more precisely on ensuring consistent performance during routine, short-term disruptions. Specifically, alongside existing infrastructure, the authors consider additional technologies, including photovoltaics (PV), battery storage, combined heat and power (CHP), and thermal systems. Particularly, CHP systems offer an integrated solution by producing both electricity and thermal energy from a single fuel source. When coupled with a chiller, they can also support cooling needs, making them remarkably versatile. Moreover, incorporating renewable energy sources alongside efficient CHP systems leads to substantial emissions reductions compared to traditional power plants and standalone heating systems such as boilers or heat pumps.
Which Optimization Problem Solver Method Was Used?
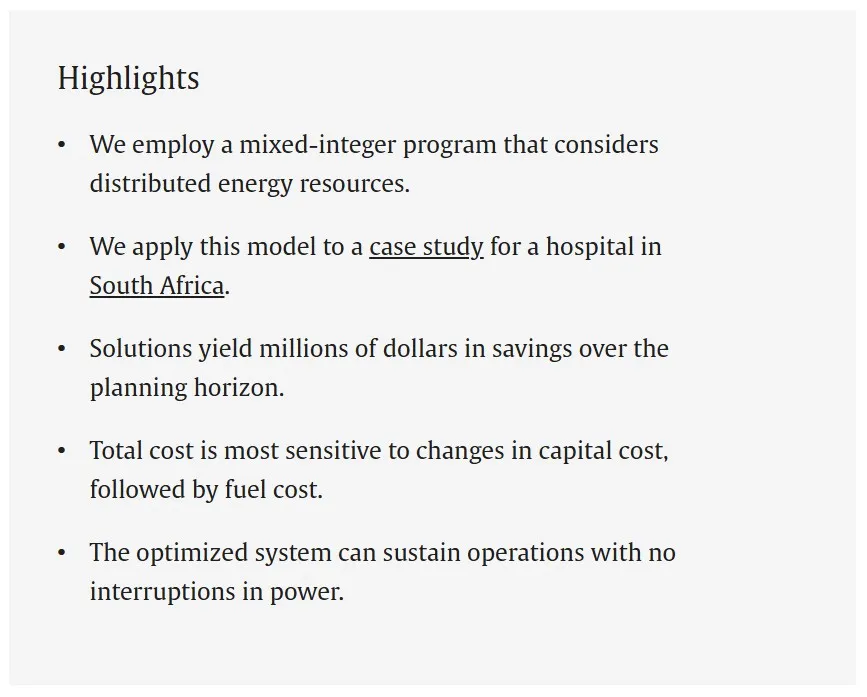
Considering the wide set of technologies, the authors propose a mixed-integer linear programming (MILP) model that provides the best (i.e., optimal) design (size and mix) and dispatch strategies for distributed generation systems that minimize lifecycle costs (capital costs, operational costs, and utility charges) while meeting heating, cooling, and electricity demands, even during frequent outages.
The authors applied this model to optimize the design and dispatch of a hospital microgrid in Johannesburg, South Africa, where energy outages pose direct threats to patient care and operational continuity.
Key Features of the Xpress Optimization SolverFICO Xpress Optimization Solver distinguishes itself by delivering advanced mathematical optimization capabilities through a suite of high-performance algorithms, including state-of-the-art linear, mixed-integer, and nonlinear solvers. The optimization platform supports a broad range of modeling environments, enabling users to construct sophisticated decision models in Python, Mosel, Java, and other widely adopted languages to facilitate seamless integration into existing decision workflows. Robust prescriptive analytics features allow organizations to address large-scale, industry-specific optimization problems (such as supply chain network design, resource allocation, and transportation planning) with speed and scalability.
Xpress Optimization incorporates intuitive modeling tools within a comprehensive API, and is engineered for enterprise-grade reliability, offering parallel processing, cloud deployment options, and support for massive datasets. |
The Process: How Xpress Optimization Could Help Keep Hospitals Running During Blackouts
The authors first generated load profiles tailored to the South African healthcare sector using climate and hospital configuration data, adapted from U.S. Department of Energy prototypes and adjusted to reflect the specific conditions in South Africa. They implemented the large-scale model in AMPL and solved it using FICO Xpress to near optimality within an hour. The model simultaneously determines:
- Design decisions (capacity and technology mix for PV, CHP, batteries, chillers, boilers)
- Hourly dispatch decisions across a whole year, accounting for variability in demand, resource availability, and outages
The optimal solution recommended by the optimization model includes a combination of PV, CHP, battery storage, and an absorption chiller. The integration of these technologies creates a well-balanced microgrid capable of handling both routine operations and disruptions. Compared to typical rule-of-thumb designs, the optimized solution achieves over $2 million in cost savings across the system’s lifetime. Results suggest that technologies such as absorption chillers, typically excluded, are shown to reduce electricity demand charges effectively, even without CHP.
The authors evaluated the system’s robustness using an outage simulator, which demonstrates that the optimized decisions improve resilience significantly, enabling the hospital to sustain five-hour outages with 100% reliability and ten-hour outages with 65% reliability. They also conducted sensitivity analyses which reveal that PV sizing is most affected by capital cost, fuel prices, and electrical demand variability, while CHP and absorption chiller sizing are highly sensitive to fuel costs. This approach is applicable not only to hospitals, but also to other high-impact facilities in emerging economies.
We at FICO warmly congratulate Jusse, Alexander, William, Tülay, and Alexandra on winning the 2025 FICO Xpress Best Paper Award. Among a field of many excellent submissions, their innovative and impactful research truly stood out.
Like many other research teams worldwide, the authors are members of our Academic Partner Program. Join our FICO Xpress Optimization Community and learn about our free community licenses for everyone and our fully-fledged free licenses for all academics. The call for the 2026 edition of the FICO Xpress Best Paper Award is out now: Consider submitting your Xpress-related research paper!
How FICO Can Help Solve Optimization Problems in Other Industries
FICO® Xpress Optimization offers a wide range of innovative optimization algorithms that are fast, scalable, and robust to solve complex problems across all industries. We leverage decades of FICO innovation in optimization combined with real-word expertise to deliver business value to hundreds of customers worldwide.
For every application, from logistics to credit risk to supply chain resilience, FICO Xpress Optimization supports a wide range of advanced analytics use cases. Users can build models using intuitive coding interfaces (Python, Mosel, Java, R, .NET, C++, and more) and adapt them to different industries to execute high-performance optimization routines that are purpose-built to improve accuracy, scalability, and decision quality. This makes it ideal not only for data scientists and operations researchers, but also for business users working in increasingly AI-driven environments.
- Explore FICO® Platform’s combined AI, machine learning, and optimization stack, from model design to deployment and its enterprise optimization capability
- See FICO Xpress Optimization in action and request a 60-day free trial license
- Join our FICO Xpress Optimization Community
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.