How Octane Achieved a 99% Digital Auto-Resolution Rate in Early-Stage Collections with FICO
Learn how Octane used FICO's collections solution to achieve a 99% digital auto-resolution rate and automate 2.4M+ interactions without adding headcount

Octane partnered with FICO to transform its early-stage collections strategy from a manual, agent-led model to an intelligent, digital-first approach. The new intelligent and scalable collections strategy led to a 99% resolution rate, automated 2.4+ million interactions per month, and scaled effortlessly without adding headcount.
Key Takeaways
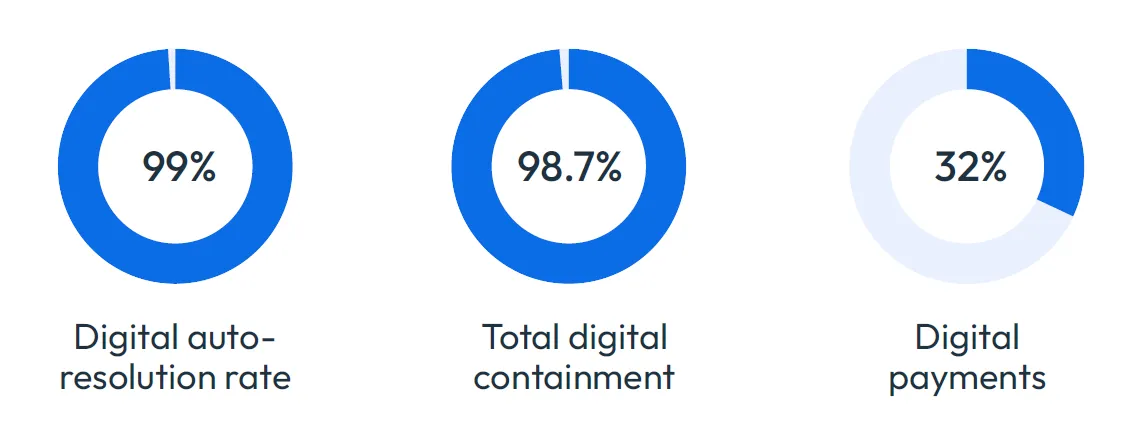
- Digital-first collections dramatically outperforms manual, agent-led approaches. Octane's shift from a dialer-based model to FICO's intelligent omni-channel communications resulted in a 99% digital auto-resolution rate and 98.7% total digital containment, proving that meeting customers on their preferred channels drives faster, higher-quality resolutions with less friction.
- Intelligent automation enables scale without adding headcount. By automating 2.4+ million interactions per month, Octane was able to absorb significant portfolio growth and manage increased delinquent volume while maintaining a stable collections team. Agents were freed up to focus exclusively on the highest-risk cases where human intervention matters most.
- A no-code, test-and-learn environment keeps strategy sharp and responsive. Using FICO® Platform, Octane can implement major strategy adjustments every 4–6 weeks without developer support, running champion/challenger tests to continuously refine messaging, timing, and channel mix in response to shifting customer behavior and market conditions.
- 4. Better collections and better customer experience are not mutually exclusive.
By delivering timely, risk-aligned communications through preferred channels with embedded payment links, Octane achieved 32% of digital payments submitted within 24 hours of communication, all while giving customers a smoother, lower-friction experience that reflects the same digital-first ethos they expect from the rest of the Octane journey.
Who Is Octane?
Octane is a leading U.S. point-of-sale lender specializing in powersports, outdoor power equipment, RV, auto, and other vehicle purchases. Through its in-house lender, Octane provides a seamless, end-to-end technology and financing experience for consumers across the credit spectrum, serving credit-worthy customers from super-prime buyers to first-time credit applicants who may be underserved by traditional lenders.
With more than 4,000 dealership partners and over $8 billion in originations, Octane has rapidly become one of the most influential players in the recreation finance industry and is expanding into new industries. Customers and dealerships choose Octane for its fast, transparent, digital-first financing experience that empowers borrowers and removes friction during the buying process.
Octane’s Challenge: Rapid Portfolio Growth and Rising Delinquencies Exposed the Limits of Manual Collections Outreach
Octane's rise coincided with one of the most difficult environments U.S. vehicle lenders had faced in decades. Delinquencies climbed across the industry, with subprime 60+ days past-due rates reaching their highest levels since the mid-1990s. Sports and performance vehicles, a core segment for Octane, carried elevated risk due to high payments, costly insurance, and greater sensitivity to economic shifts. Repossessions increased significantly, lenders tightened credit standards, and used-vehicle interest rates rose into double digits, particularly for subprime borrowers.
At the same time, Octane was entering a period of significant expansion. Beginning in 2019, the company broadened its focus beyond subprime lending, expanding into prime segments and new markets such as auto, recreational vehicles, tractors, and outdoor power equipment. Leadership anticipated rapid growth and the portfolio nearly doubled annually.
As volume increased, so did the number of accounts requiring payment reminders or early-stage collections outreach. The company's servicing team relied primarily on an agent-led, dialer-based strategy, partially through third-party service providers. As account volumes accelerated, it became clear that this approach could not scale and limited Octane's ability to directly control how and when customers were engaged.
The onset of COVID and broader market volatility introduced additional delinquency risk, making it even more important to manage early-stage performance carefully while continuing to grow. Together, these forces created a clear need to rethink collections by shifting toward a more scalable, efficient, and risk-aligned approach to customer engagement.
The Solution: How FICO Evolved Agent-Led Dialing with Intelligent Digital Engagement
As the business expanded, Octane set a strategic goal to improve early-stage collections with an intelligent digital-first approach. Customers were already interacting with Octane digitally during the prequalification and buying process, and the company saw an opportunity to extend that experience into collections. The team wanted a solution that would reach customers at the right time and on their preferred channel, personalize communication to risk and behavior, and reduce dependence on manual, agent-led workflows.
To bring this strategy to life, Octane turned to a partner they already trusted. The lender has partnered with FICO for originations and credit strategy, including using FICO® Auto Score 10. Extending the collaboration into intelligent digital engagement in collections was a natural next step. The team selected the FICO® Platform – Omni-Channel Engagement Capability for Collections (Customer Communication Services) to build, automate, and optimize their new collections strategy.
FICO's Customer Communications Capability enabled intelligent, automated, risk-aligned outreach across text, email, and voice, ensuring customers received timely reminders through the channels they prefer. Messages included embedded payment links and simple response options, making it easy for customers to act quickly without waiting for a phone call. The capability also reserved agent time for the highest-risk cases, improving focus where human engagement matters most.
Implementation moved quickly. Using FICO's no-code environment for designing and updating digital engagement strategies, Octane's servicing team configured the new approach in-house without relying on developers. The team built flexible workflows tied to risk tiers, payment behavior, and timing, then launched champion/challenger tests to begin optimizing immediately. The intelligent digital communications capability integrated smoothly with Octane's servicing systems, enabling automated case creation and real-time response handling across the entire portfolio.
The Results: 99% Digital Resolution, 2.4+ Million Monthly Automated Interactions, and a Scalable Collections Engine
FICO's intelligent digital communication capabilities have enabled Octane to shift from manual, agent-heavy outreach to a modern, data-driven collections capability that meets customers where they are, adapts quickly, and scales effortlessly as the business continues to grow. The result is a collections operation that performs more effectively, scales efficiently, evolves through rapid strategy refinement, and delivers a smoother, more supportive customer experience.
Improved Digital Resolution Performance
Using intelligent digital communications for early-stage collections, Octane’s in-house lender reaches customers quickly through their customers’ preferred communication channels, which has led to faster engagement, higher response rates, and more self-service resolutions. Automated reminders, embedded payment links, and simple response options enable customers to resolve their accounts with minimal friction.
This intelligent digital first approach delivers measurable improvements, including:
- 99% digital auto resolution rate
- 98.7% total digital containment across all cases, including:
- 32% digital payments submitted within 24 hours of communication
Clear Scalable Capacity
As Octane’s portfolio expanded, delinquent account volume increased. Digital communications allowed the team to absorb this growth seamlessly by automating outreach, streamlining workflows, and ensuring customers received reminders at the right time and on the right channel, without adding complexity or strain to the call center.
This intelligent, digital-first operating approach delivers clear scalability benefits, including:
- 2.4+ million automated interactions per month, supporting large-scale customer outreach
- Managed increased delinquent volume, while maintaining a stable collections team
- Majority of early-stage cases handled by automated digital outreach
- Agents are reserved for higher risk customers requiring human intervention
Ongoing Strategic Agility
Octane continually refines its digital engagement strategies to stay aligned with customer behavior and portfolio needs. Using FICO® Platform, the team can adjust messaging, timing, and channel mix quickly while running champion/challenger tests to identify the most effective approaches. This rapid, iterative approach ensures communication strategies remain current and continue improving over time.
This continuous test-and-learn approach delivers ongoing performance improvement, including:
- Major adjustments implemented every 4–6 weeks
- Ability to deploy new or revised engagement flows without developer support
- Improved effectiveness across scripts, channels, and timing sequences
- Faster adaptation to shifting customer behavior or market conditions
Improved Customer Experience
Octane’s borrowers, many of whom are financing a meaningful lifestyle purchase, benefit firsthand from the simple, digital-first communications experience. Customers receive timely reminders through their preferred channels and can resolve their accounts quickly through embedded links and intuitive self-service flows.
This experience-focused design delivers a great customer experience, including:
- Higher digital self-service across email, SMS, and voice
- Faster, lower-friction resolutions via embedded payment links
- Consistent, risk-aligned communication across all customer segments
What’s Next for Octane: Expanding Digital Engagement and Intelligence
Octane continues to build on its digital-first collections foundation, with a focus on expanding both the reach and sophistication of its engagement strategies. The team is actively exploring new ways to enhance communication channels, strengthen response rates, and further reduce reliance on manual processes.
Octane plans to incorporate more advanced, AI-driven capabilities into its digital communications strategy. These enhancements are expected to enable more dynamic, personalized interactions and help the team respond more intelligently to customer behavior in real time. In parallel, Octane is exploring ways to extend digital engagement into later stages of delinquency for select segments, as well as integrating collections strategies with broader customer assistance programs. This includes evaluating options such as payment flexibility and loan assistance offerings to better support customers who may be experiencing ongoing financial challenges.
Learn More About FICO's Collections Solutions
- Download the full Octane and FICO case study
- Read the case study to see how one company is saving $5 million annually in write-offs thanks to FICO’s collections analytics
- Learn more about the empathy paradox in collections and how it leads to increased revenue
- Learn more about FICO’s Collections solutions
Frequently Asked Questions
Reaching customers through a single channel is often not enough. By coordinating timing and sequencing across SMS, email, voice, and digital touchpoints, omni-channel communications solutions increase the likelihood that messages are seen, understood, and acted on. This helps drive engagement, improve resolution rates, and reduce the need for agent intervention.
The most effective approach is to reserve agent time for the highest-risk cases where human intervention matters most, while automating outreach for the majority of early-stage cases. This ensures that agent capacity is focused where it has the greatest impact, while customers who are likely to self-serve receive timely, frictionless reminders through their preferred channels.
Effective personalization doesn't require manual effort. By building flexible workflows tied to risk tiers, payment behavior, and timing, lenders can ensure that each customer receives the right message, on the right channel, at the right moment, all through automated, intelligent outreach. Embedded payment links and simple response options further reduce friction and make it easy for customers to act quickly.
The key is building a continuous test-and-learn capability into the collections strategy. Using a no-code environment, teams can adjust messaging, timing, and channel mix quickly without relying on developers, while running champion/challenger tests to identify the most effective approaches. This allows major strategy adjustments to be implemented every 4–6 weeks, ensuring communication strategies remain current and continue improving over time.

Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.